The number on the sign at a Summerlin model complex is a base price: the least expensive plan, on the least expensive lot, with the standard finishes. In the fourth episode of our Las Vegas Playbook, host Daniel Pittman asks Stacey Tyler, a Las Vegas agent since 2003 who raised her family in Summerlin, the question every out-of-state buyer asks first: do you have to pay sticker price? Her answer is no, and the rest of the conversation is about everything the sticker leaves out: lot premiums, upgrades, the dirt backyard, the master association, the village association and the special improvement district that shows up on the tax bill.
This guide turns that conversation into a sourced cost stack. We checked every layer against a primary record on September 28, 2026: builder pages for base prices and incentive terms, the Las Vegas MLS for what new Summerlin homes actually sold for and what their associations charge, the City of Las Vegas special-assessment records for eight Summerlin West neighborhoods, and the Clark County Treasurer for the tax rates. It is a companion to our land-price analysis of Summerlin new construction, which explains why the base price is high in the first place; this one explains what gets added on top.
A Summerlin new build costs its base price plus the lot premium and options, which put two Ashland Summits $258,000 to $285,000 above today's base price, plus a backyard. Monthly, add the $69 Summerlin West master fee, neighborhood dues that mostly ran $65 to $199 on September 28, 2026, and a City of Las Vegas SID billed twice a year at $222 to $832. Compare total monthly cost.
- Of 193 Summerlin new builds with MLS sale dates from October 2025 to July 2026, 85% sold below list.
- The Summerlin West master association charges $69 a month in 2026; village dues come on top.
- City SIDs 815, 816 and 817 added $37 to $139 a month in eight neighborhoods we checked.
- City of Las Vegas lots pay $3.2782 per $100 assessed; the Summerlin Town district pays $2.9328.
- Taylor Morrison's 4.50% and 5.49% offers cover conforming loans only, up to $832,750 in 2026.
What Does a Summerlin Builder's Base Price Actually Include?
A base price buys a plan, not a house. It is the builder's starting figure for the smallest version of a floor plan, on a standard homesite, with the standard feature list. Taylor Morrison says so directly in the disclaimer on its Las Vegas offers page, read September 28, 2026: "Prices may not include lot premiums, upgrades and options depending on stage of construction." That is why the first question at any sales office should be "what is standard on this plan, in writing?"
In the episode, Stacey lists what surprises her clients most. The lighting in a model is usually not part of the home: you get the structural element, the box in the ceiling, but not the fixture. The washer, dryer and refrigerator are often not included. Depending on the builder, "some of them make them grand with upgrades," and walking a bare-bones quick move-in after a decorated model is, in her words, "a night and day difference." She mentions touring Toll Brothers' Glenrock models as an example of how far a model can go. She also warns that a room you saw in the model may not exist in your house, because a wall or a bedroom is a structural option. The segment starts at 4:04 in the video.
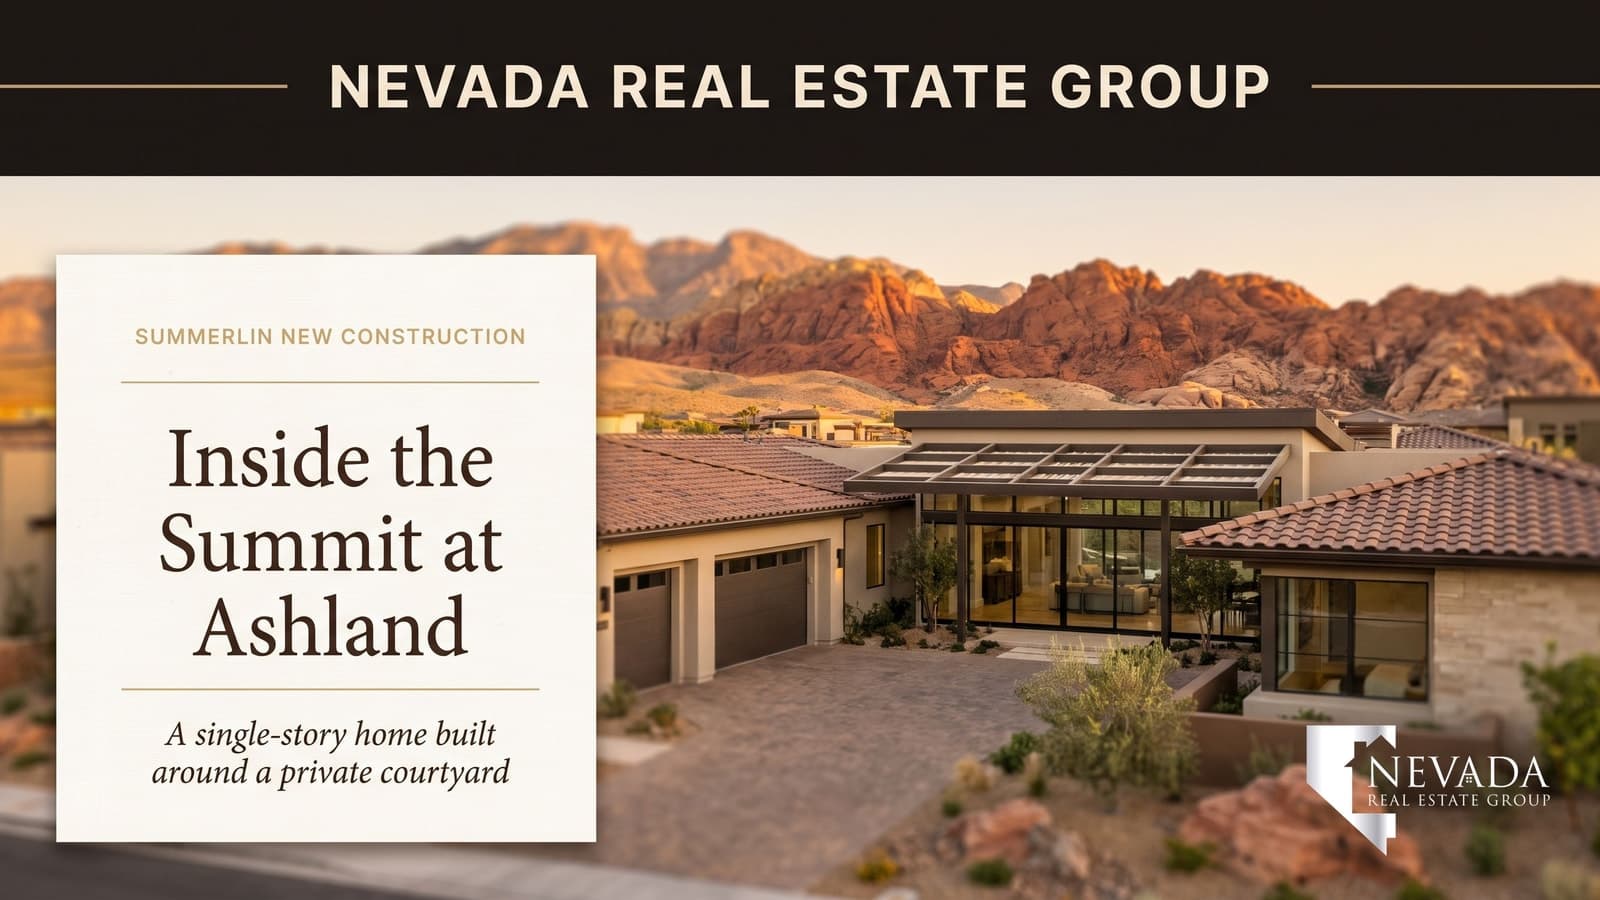
A builder's own standard list shows the pattern. On Taylor Morrison's Ashland at Summerlin page, the published standard kitchen names a GE wall oven, a GE gas cooktop, a GE vented hood, a GE dishwasher and a GE built-in microwave, with quartz counters and 42-inch upper cabinets. There is no refrigerator on that list, and there is no Wolf or Sub-Zero, even though the Summit model at Ashland shows both. We walked that model in a separate tour; our Summit at Ashland guide lines the published standard list up against what the model shows.
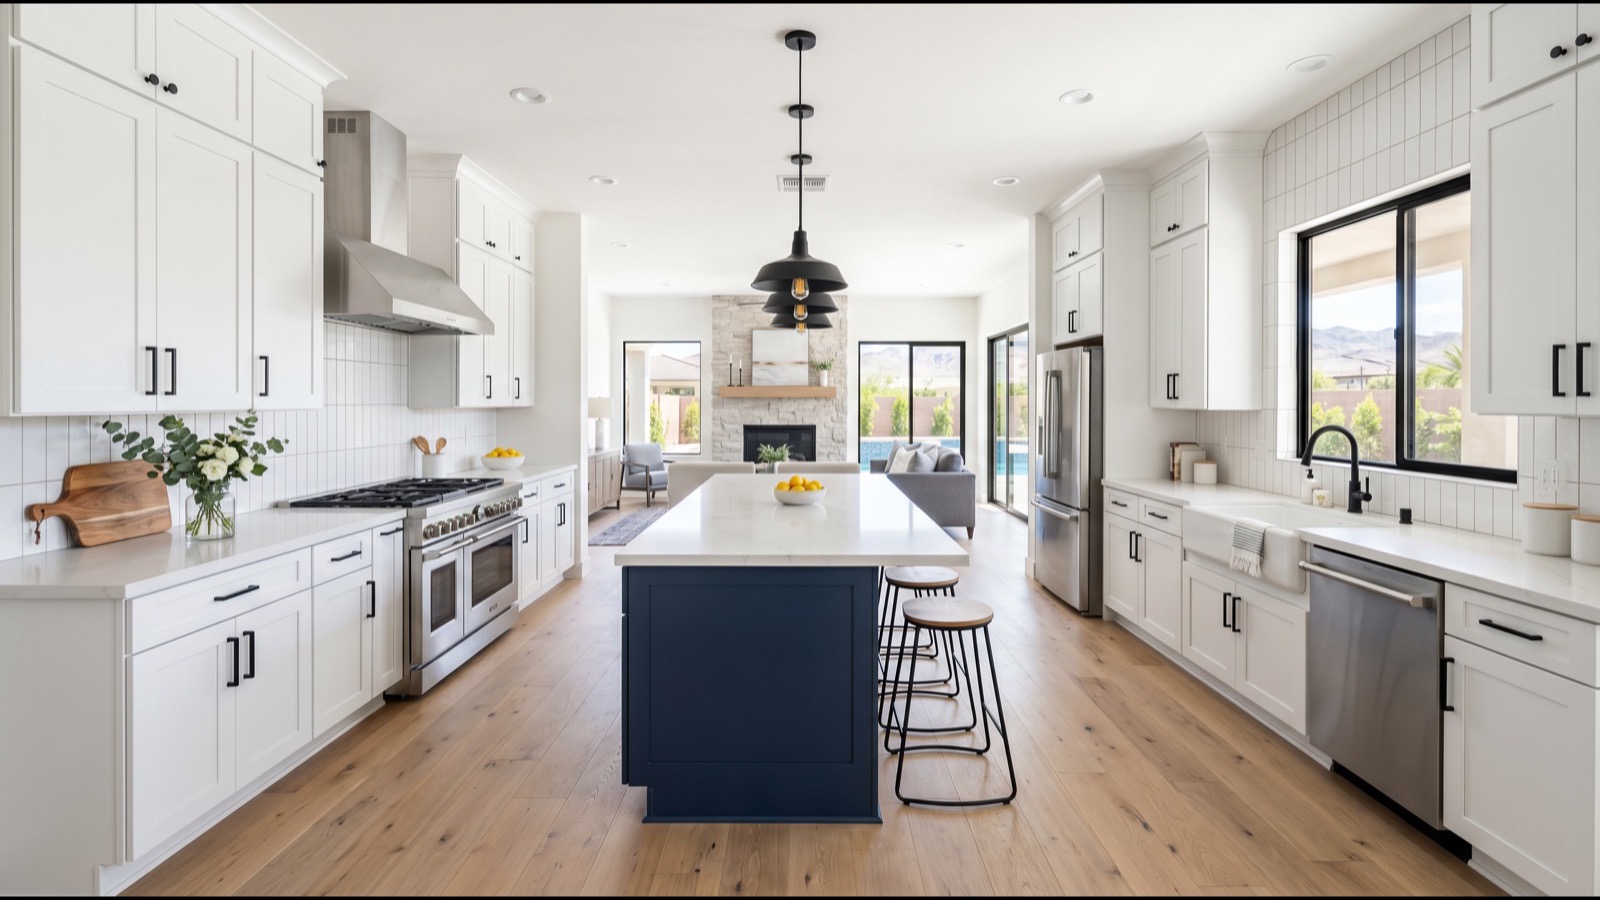
Our earlier walk-through of a Summerlin West plan in Dove Rock, on model-home upgrades that are not included, found the same gap; the rest of this guide puts dollar figures on it.
How Do Lot Premiums and Options Turn a Base Price Into a Contract Price?
Two things sit between the base price and the number on your contract: the homesite and the options. A lot premium is the extra a builder charges for a particular lot, for a view, a larger yard, a corner or cul-de-sac position, or no rear neighbors. Options are everything you add in the design center or through structural choices. Stacey's example is the drive-by buyer who sees "$800,000" on a sign and assumes that is the price, then learns the sign quotes the first of ten models, before the lot and upgrades. She says premiums for city-view lots in West Summerlin can run into the hundreds of thousands; builders do not publish premium schedules online, so treat her figure as one agent's observation and ask each sales office for its homesite price list. The segment starts at 7:56 in the video.
The MLS lets you measure the combined effect for one community. We pulled Las Vegas MLS data through Repliers on September 28, 2026 for Taylor Morrison's Ashland plat in Grand Park village and matched homes to the builder's current base prices on its Ashland page.
| Home and plan | Plan base price | Builder's "was" price | MLS original list | Current or sold price |
|---|---|---|---|---|
| 12218 Elderwood Street, Frontier, 2,662 sq ft | $1,099,990 | $1,226,967 | $1,335,401 | $1,179,900 listed |
| 525 Stowell Avenue, Liberty, 3,027 sq ft | $1,284,990 | $1,466,978 | $1,479,990 | $1,359,990 listed |
| 490 Carter House Avenue, Summit, 3,306 sq ft | $1,439,990 | Not shown | $1,790,310 | $1,698,173 sold |
| 598 Gilhaven Avenue, Summit, 3,306 sq ft | $1,439,990 | Not shown | $1,892,701 | $1,725,000 sold |
Read across each row. The Liberty on Stowell Avenue carried a "was" price $181,988 above its plan's base, 14% more, and the MLS original list was higher still. The two Summits closed $258,183 and $285,010 above today's base. Those gaps are the lot, the options and the builder's pricing of a finished home, and they are why the base price is a poor budget number. The two sold Summits closed on December 31, 2025 and February 25, 2026, the Gilhaven home having gone under contract on January 26, 2026; the Frontier and Liberty were still listed on September 28.
Notice also that the builder's "was" price and the MLS original list price are different numbers for the same house. A builder's "was" price is its own framing of a markdown; the MLS records every change from the first list price. Show both side by side before you judge a discount. For negotiating the lot itself, our lot premium negotiation guide covers which premiums have room to move.
Can You Negotiate on a New Build in Summerlin Right Now?
Stacey's answer is yes: "there's a lot of negotiation going on right now." The MLS supports her on completed homes. We pulled every home built in 2025 or later in the Summerlin ZIP codes (89138, 89135, 89144, 89134 and 89166) through Repliers on September 28, 2026 and kept the Summerlin plats. The counts below cover closed homes with an MLS sale date between October 1, 2025 and July 31, 2026 (usually the contract date; for about a third, the closing date). Sales in Caldwell Park, Cloudbreak and Nighthawk fall outside the 193 because their MLS neighborhood and association fields do not say Summerlin; including them gives 206 homes, 84.5% sold below original list at a median 95.0%.
| Segment | Count | Median sale or list price | Median sold as share of original list | Share below original list |
|---|---|---|---|---|
| All closed, MLS sale date October 2025 through July 2026 | 193 | $646,173 | 94.8% | 85% |
| Closed single-family homes only | 115 | $1,139,990 | 93.7% | 93% |
| Closed at $1,000,000 or more | 61 | Not applicable | 91.9% | Not applicable |
| Available on September 28, 2026 | 108 | $672,028 list | Not applicable | 56% with a price cut |
The median closed new build sold $44,392 below its original list price, and among homes that closed at $1 million or more the median gap was $165,388. Of the 108 available on September 28, 60 (56%) had been reduced, by a median of $37,430. Two cautions keep this honest. First, builders put mostly completed and quick move-in homes into the MLS; a home you contract to build from scratch is often never listed, so these figures describe inventory homes, where builders have the most reason to deal. Second, January 2026 is a heavy month in this window, and GLVAR closings recorded in August and September 2025 are under-reported, which is why we start in October. Without January's 35 sales, 83.5% of the remaining 158 sold below original list at a median 95.0%.
What this means in practice: negotiation on a Summerlin new build is less often a lower base price and more often a lower price on a finished home, a lot premium waived, or incentive money applied to options or the rate. A builder with finished inventory before a quarter-end has more room than one with a waiting list. In our experience, the strongest leverage is knowing which specific homes have been sitting, which is exactly what the MLS history shows. Our Summerlin new construction page shows what is available now.
What Monthly Fees Come With a Summerlin West New Build?
Stacey's second surprise for out-of-state buyers is the fee stack: a Summerlin master-plan fee, a separate association for your neighborhood, and an SID. The segment is at 10:05 in the video. Start with the master association, because every Summerlin home pays one. According to the Las Vegas Review-Journal's October 8, 2025 report, monthly master assessments rose on January 1, 2026 to $69 for Summerlin West (from $60), $74 for Summerlin North (from $65) and $76 for Summerlin South, and the Summerlin Council's share inside those assessments rose to $37 per household to fund parks, pools and programs.
The village or neighborhood association is where the range opens up. The MLS carries two association fields on most Summerlin new builds, and on September 28, 2026 the Summerlin West listings showed the $69 master fee almost everywhere, with a few stale entries still at the 2025 figure of $60.
| Neighborhood, as recorded in the MLS | Builder | Product | Summerlin West master fee | Second association fee in the MLS | Monthly total |
|---|---|---|---|---|---|
| Caldwell Park, Village 29 | KB Home | Single-family | $69 | $65 | $134 |
| Brantley, Village 25 Parcel KL | Pulte | Single-family | $69 | $70 | $139 |
| Sandpiper, Village 22 Parcel YZ | Lennar | Single-family | $69 | $83 | $152 |
| Cloudbreak | KB Home | Single-family | $69 | $87 | $156 |
| Ashland, Village 25 Parcels H and I | Taylor Morrison | Single-story, gated | $69 | $119 | $188 |
| Primrose Park, Village 29 Parcel J | Richmond American | Single-family | $69 | $119 | $188 |
| Edgewood, Village 25 Parcel M | Tri Pointe | Single-family | $69 | $160 | $229 |
| Caldwell Park, Village 29 | KB Home | Townhome | $69 | $175 | $244 |
| Lark Hill | Taylor Morrison | Townhome | $69 | $199 | $268 |
| Esplanade at Red Rock villas | Taylor Morrison | Resort-style villas and townhomes | $69 | $435 to $542 | $504 to $611 |
Three patterns stand out. Attached homes pay more than detached homes in the same village because the association maintains more, as the two Caldwell Park rows show. Amenity-heavy communities such as Esplanade carry the highest dues. And a gate does not automatically mean high dues: Ashland is gated at $119. Summerlin South runs higher at the master level, $76, and the MLS showed neighborhood fees of $255 to $307 on new homes in Village 17A. Ask for the association's current budget and reserve study, because the MLS figure is what the listing agent entered. Our Summerlin HOA fee guide covers resale neighborhoods.
What Are Special Improvement Districts, and What Do They Cost in Summerlin West?
An SID pays for the public infrastructure that made the lots buildable: roads, curbs, sidewalks and utilities. According to Assessment Management Group, which bills the City of Las Vegas districts, the municipality sells bonds for the improvements and every benefiting property repays its share, with principal and interest, in installments; the final payments on the districts below run to 2049 through 2053. It is not an association fee and it is not a property tax, even though Stacey rightly groups it with both. In Summerlin West the districts belong to the City of Las Vegas, and each lot's record is public. Under NRS 271.420, the assessment is secured by a lien on the lot, and NRS 271.415 leaves any prepayment privilege and premium to the district's ordinance; according to AMG, the City's assessments may be paid in full at any time.
We looked up one lot in each of eight Summerlin West neighborhoods on September 28, 2026. Every lot we checked in a given neighborhood carried the same or nearly the same original assessment, so these figures are a fair guide to each neighborhood, but request the payoff for your own lot.
| Neighborhood and district | Original assessment | Estimated installment due April 1, 2027 | Monthly equivalent | Final payment |
|---|---|---|---|---|
| Ashland, SID 815 | $23,253.51 | $831.99 | About $139 | October 1, 2049 |
| Brantley, SID 815 | $20,826.99 | $745.17 | About $124 | October 1, 2049 |
| Primrose Park, SID 817 | $18,282.58 | $728.64 | About $121 | April 1, 2053 |
| Edgewood, SID 815 | $17,649.93 | $631.50 | About $105 | October 1, 2049 |
| Caldwell Park, SID 817 | $8,539.33 | $340.33 | About $57 | April 1, 2053 |
| Sandpiper, SID 816 | $11,692.68 | $336.27 | About $56 | April 1, 2051 |
| Nighthawk at Kestrel, SID 816 | $9,358.85 | $269.15 | About $45 | April 1, 2051 |
| Lark Hill, SID 816 | $7,730.95 | $222.33 | About $37 | April 1, 2051 |
The spread is the lesson: the same master plan carries SIDs from about $37 to about $139 a month, depending on the district and the size of the parcel. Installments are billed twice a year, due April 1 and October 1, and payable to the City of Las Vegas, which is why a figure like Ashland's "$832" sounds like a monthly fee in conversation but is a semi-annual bill. According to Assessment Management Group's FAQ, the remaining balance transfers to the new owner when a home sells, the assessment can be paid in full at any time, and the payoff includes any prepayment penalty.
A Summerlin South street we searched in Village 17A, Rolling Vista Drive, returned no record in this City of Las Vegas database; ask the sales office in Summerlin South which district, if any, applies there. For the resale side of the same question, our SID and LID balance guide shows how to read a payoff before you buy a used home.
Why Does It Matter That Summerlin Is Not a City?
Stacey's first piece of education for relocating buyers is that "Summerlin's not a city." Summerlin is a master-planned community developed by Howard Hughes Holdings, as the Review-Journal's Grand Park report notes, spread across more than one jurisdiction. The Summerlin West neighborhoods in our SID table pay City of Las Vegas assessments, and the Ashland parcels we checked sit in the city's tax district; other parts of Summerlin sit in unincorporated Clark County. The mailing address says Las Vegas either way, which is why the conversation turns to buyers surprised by their first bill. The difference shows up in the property-tax rate.
According to the Clark County Treasurer's tax rates by district, the fiscal 2026-27 rate is $3.2782 per $100 of assessed value in district 200, the City of Las Vegas, and $2.9328 in district 421, Summerlin Town, an unincorporated town district. Under NRS 361.225, assessed value is 35% of taxable value, and under NRS 361.227 taxable value for a building is its replacement cost less depreciation plus the land, not the price you paid.
Here is what that means on a real Summerlin West parcel. The Summit model home at Ashland, 796 Windover Court, is in district 200. According to the Clark County Assessor's record, its fiscal 2026-27 assessed value is $515,261 on a taxable value of $1,472,174, after a recorded sale of $2,108,700 in January 2026. At the city rate, the gross tax before any abatement is about $16,891 a year. The same assessed value at the Summerlin Town rate would be about $15,112, roughly $1,780 a year less. Two houses of the same value can carry different bills because of a jurisdiction line you cannot see from the street, so check the tax district on the assessor's record for every lot you compare.
The first-year bill on new construction has its own rule. According to the Clark County Assessor's abatement page, new construction does not qualify for either tax cap in its first fiscal year and receives the 3% primary-residence cap or the cap of up to 8% starting the following fiscal year; the 3% cap applies to a primary residence you claim. Our Las Vegas property tax guide walks through the first bill on a new home.
What Do Builder Incentives Look Like in Summerlin Right Now?
Stacey calls incentives one of the big reasons buyers are looking at new construction: "they are offering interest rate packages." Her examples are illustrations, not quotes: one builder might offer 2% in year one and 3% in year two before a permanent rate near 5%, another "a 3.99 for seven years," another a lock at 4.99%. The episode's graphic labels those as a 2-1 buydown and long-term fixed-rate buydowns. The segment starts at 12:17 in the video. The honest way to evaluate them is to read the terms on the builder's own page, because every incentive has a deadline, a lender requirement and a loan-size limit.
Here is what two Summerlin builders published on September 28, 2026. According to the promotion terms on Taylor Morrison's Ashland page, its "$50K Flex Cash" is valid on contracts from August 1 to September 30, 2026 on select Las Vegas quick move-in homes that close by October 30, 2026; applied to options or the lot premium it is a price reduction available to any buyer, while using it for a buydown, points, closing costs, prepaids or up to a year of HOA dues requires Taylor Morrison Home Funding. According to Taylor Morrison's Las Vegas offers page, it offered a 4.50% fixed rate (4.57% APR) on select quick move-ins contracted September 16 to 30 and closed by October 23, and 5.49% (5.60% APR) with a nine-month lock on select to-be-built homes contracted in the same September 16 to 30 window and closing by June 30, 2027, both "available for conventional conforming loan limits." According to Toll Brothers' Raven Crest page, the builder advertised "5.25% (5.51% APR) 30-Year Fixed Limited Time Only on Select Homes" at its townhome community in Summerlin's Kestrel Commons, with townhomes starting at $630,000.
| Offer | Rate and APR | Applies to | Key limits |
|---|---|---|---|
| Taylor Morrison quick move-in fixed rate | 4.50%, 4.57% APR | Select Las Vegas quick move-ins | Contract September 16 to 30, close by October 23, 2026; conforming loans; builder's lender and closing agent |
| Taylor Morrison to-be-built rate lock | 5.49%, 5.60% APR | Select to-be-built homes | Contract September 16 to 30, 2026; nine-month lock; close by June 30, 2027; conforming loans; select communities |
| Taylor Morrison $50,000 flex cash | Not a rate; price reduction or finance credit | Select quick move-ins | Contract by September 30, close by October 30, 2026 |
| Toll Brothers, Raven Crest | 5.25%, 5.51% APR | Select homes | Terms from the sales office; townhomes from $630,000 |
| Freddie Mac 30-year average | 7.03% as of September 24, 2026 | National conventional benchmark | Not a quote |
The conforming limit matters in Summerlin more than almost anywhere in the valley. According to the Federal Housing Finance Agency, the 2026 one-unit conforming limit for most counties, including Clark, is $832,750. With 20% down, that caps the price at about $1,040,900 for a buyer who wants the builder's rate. Above that, the rate offer needs a larger down payment or does not apply. Our 2-1 buydown guide explains how temporary buydowns step up.
How Much Does a Builder Rate Save on a Real Summerlin Home?
A worked example makes the incentive concrete. Taylor Morrison's Lark Hill townhome at 1569 Song Lark Lane was listed on the builder's offers page on September 28, 2026 at $549,990, down from a "was" price of $571,082, with a ready date of August 22, 2026, and it appeared on that page among homes eligible for the builder's limited-time offers. The MLS showed the same $549,990 list price against an original list of $566,082. Confirm in writing that this home qualifies for the 4.50% rate: the offers page lists it as eligible, but the payment calculator on its own listing page did not show a promotional rate on September 28. It is a 1,796-square-foot townhome, and the MLS shows association dues of $69 and $199. The Lark Hill lots we checked carry City SID 816 with an estimated $222.33 installment due April 1, 2027. Taylor Morrison's own offer example happens to use a $550,000 price with 20% down, so a loan this size fits the offer's conforming requirement, provided you contract by September 30 and close by October 23, 2026.
For the benchmark we use Freddie Mac's Primary Mortgage Market Survey, which put the 30-year fixed average at 7.03% as of September 24, 2026, up from 6.95% a week earlier and 6.30% a year earlier. For tax and insurance we use the assumptions in Taylor Morrison's own calculator, 1.0% and 0.11% of the price a year. Your lender, credit score and loan type will change the result.
| Monthly line | At the 7.03% Freddie Mac average | At Taylor Morrison's 4.50% quick move-in rate |
|---|---|---|
| Loan amount | $439,992 | $439,992 |
| Principal and interest | $2,936 | $2,229 |
| Property tax, builder calculator at 1.0% | $458 | $458 |
| Insurance, builder calculator at 0.11% | $50 | $50 |
| Association dues, $69 plus $199 | $268 | $268 |
| SID 816, April 2027 installment spread monthly | $37 | $37 |
| Estimated monthly total | About $3,750 | About $3,043 |
The builder's rate saves about $707 a month on principal and interest, about $8,481 a year. Stacey's frame is the right one: it comes down to "payment sensitivity." If the monthly figure decides whether you can buy, a builder rate on an eligible quick move-in may be worth more than a lower price on a resale home. If you are paying cash or putting down a large share, a price cut or free options may be worth more. Ask for both versions in writing, and get a Loan Estimate from an outside lender. Run your own figures in our mortgage calculator.
Should You Choose a Quick Move-In or Build From Scratch?
The episode draws the line clearly. A quick move-in, which Stacey describes as "probably under 45 days" to close, is a home the builder has started or finished on spec; a to-be-built home is one you choose from the lot up. Builders build quick move-ins on purpose, she says, to have homes ready for buyers who need to move now. The two paths cost differently in ways that are easy to miss.
The quick move-in is where the deals are. Taylor Morrison's flex cash and its lowest published rate, 4.50%, were both limited to quick move-ins, and the MLS price cuts in our negotiation table are mostly on finished homes. You also see exactly what you are buying: the lot, the options, the view from the kitchen. The trade-off is that someone else chose the finishes, and a spec home with options you would not have picked is not a bargain if you replace them.
The to-be-built home gives you the plan, the lot and the finishes you want, and you avoid paying for someone else's choices. The costs are time, a design-center appointment where budgets expand, and fewer incentives. On September 28, 2026, Taylor Morrison's offer on select to-be-built homes contracted by September 30 was a 5.49% rate with a nine-month lock, almost a full point above its quick move-in rate, and its flex cash did not apply to homes that close after October 30. Our design center budget guide covers which options are worth buying from the builder and which to add later.
Choose a quick move-in if you need to move within a couple of months, if the rate matters most, or if you want to see the finished lot before you pay for it. Choose to build if the specific plan, lot and finishes matter more than the incentive, and you can wait. Either way, walk a finished, unfurnished home of the same builder before you sign, so you calibrate your eye against the model.
Why Do Model Homes Look So Different From the Home You Buy?
Because models are built to sell, and they carry most of what the options sheet offers. Stacey's list, lighting, appliances, the washer and dryer, an extra wall or room, is a short version of what the model includes and the base plan does not. The episode puts it as "model versus reality," and the numbers from one Summerlin community show how large that gap can be.
The Summit model home at Ashland, 796 Windover Court, closed on January 22, 2026 at $2,108,700, according to its MLS record, and the county recorded the sale at the same price in January 2026. The listing says the purchase included Taylor Morrison's model leaseback program. That home is the same 3,306-square-foot plan that Taylor Morrison listed from $1,439,990 on September 28, 2026. The difference, $668,710, is the most concrete measure we know of what "decorated model" means in Summerlin West: the lot, the options and finishes, the landscaping and the leaseback terms, on the same floor plan as the base-price home.
This is not a reason to avoid models. It is a reason to tour them with the included-features sheet in hand and to ask, room by room, "is this standard?" Take photos of what you like and ask for each item's option price. Ask whether the model is on a premium lot, because a view from the model's great room may cost six figures on your contract. And ask to see a finished quick move-in of the same plan with standard or near-standard finishes. Our tour of the Tiki villa at Esplanade found the same pattern at the other end of Taylor Morrison's Summerlin price range, where lighting and a refrigerator were among the items the base price did not include.
What Does a Backyard and Pool Add to a Summerlin New Build?
Stacey's rule of thumb is that Las Vegas new homes come with a dirt backyard, and Kimberly James says the same thing about Ashland in our Summit tour: "When you buy the home, it comes with dirt." Landscaping, a patio cover, pavers, turf, lighting and any pool are post-closing costs or builder options. We are not going to quote a single number for a backyard, because the range on a Summerlin lot runs from a basic desert package to a full outdoor kitchen and pool; the only reliable figure is two written bids for your lot. What we can pin down are the rules that shape the budget.
The biggest is the pool limit. According to the Southern Nevada Water Authority, a July 2022 SNWA resolution supports a 600-square-foot surface-area limit on new residential pools, which the Las Vegas Valley Water District and local jurisdictions adopted through rule and code changes; the average pool in Southern Nevada is about 470 square feet, and the average in-ground pool loses 48.6 gallons of water per square foot a year to evaporation. Stacey's point follows directly: if you want a big pool, "you're going to have to go resale," because an existing larger pool can stay.
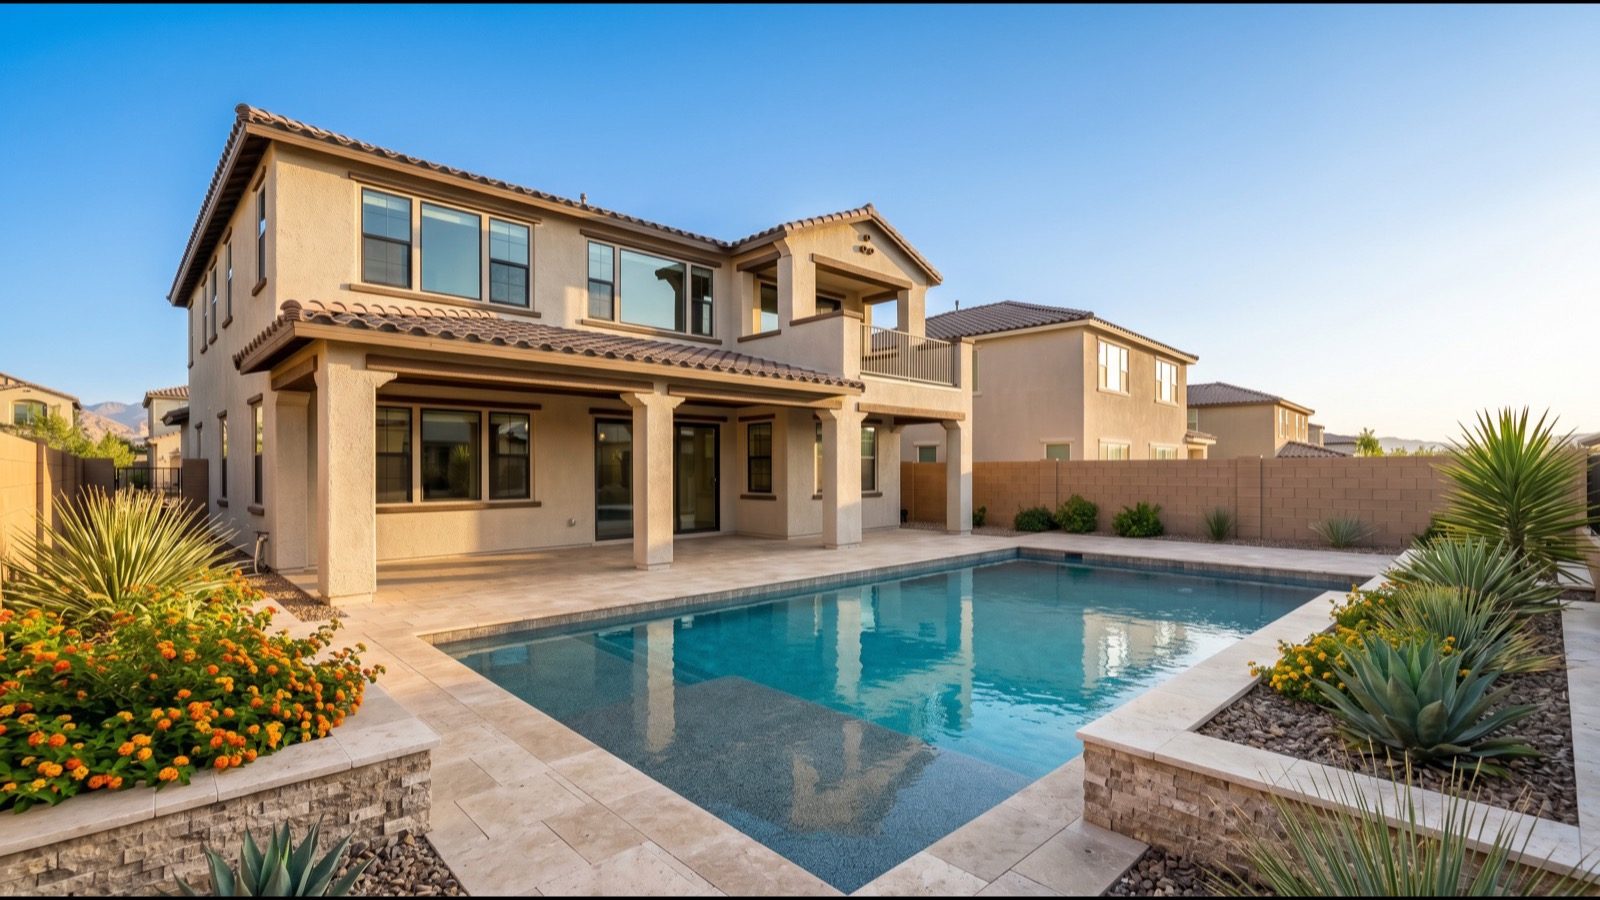
Two more constraints shape the plan. Your association's architectural review will approve the yard design, walls and gates, which can add weeks, so ask for the guidelines before you sign. And the builder's grading and drainage plan limits where a pool can go; ask for the plot plan before you choose a lot if a pool is a priority. Our Las Vegas pool cost guide covers build and upkeep costs, and our homes with pools search shows resale homes where the pool is already built.
Should You Buy New Construction or Resale in Summerlin?
Daniel says this is the question he wants to end on, and it is the one most buyers are really asking. Stacey's answer turns on rate and completeness. A resale home is finished, with the yard, the window coverings and possibly a pool already there, and it can be the "perfect pool" you cannot build new. It is financed at market rates, which Stacey put at "around seven and a quarter" at the time of the video, published September 26, 2026; Freddie Mac's survey had the 30-year average at 7.03% as of September 24, 2026. A new build comes with builder rate programs, and with the costs in this guide stacked on its base price. The segment starts at 11:14 in the video.
Add three differences the episode does not have time for. First, the SID: on a resale home, part of the balance may already be paid down, and the remaining balance transfers to you; on a new build you start near the full original assessment. Second, property tax: a sale does not reset a resale home's tax base, but the seller's 3% cap does not carry over to you; you must claim the 3% cap for your own primary residence, and until you do, the cap of up to 8% applies. A new build gets no cap in its first fiscal year. Third, the finish: a resale home's price already includes its landscaping and upgrades, so compare a new build's contract price plus backyard with the resale price, not base with resale.
The right answer is usually the one with the lower total monthly cost for the home you would actually live in. For a buyer who is payment-sensitive and can use an eligible quick move-in, the builder rate often wins. For a buyer who wants a large pool, mature landscaping or an established street, resale often wins. Our new construction versus resale guide sets out the full comparison.
Why Bring Your Own Agent Into a Builder's Sales Office?
Daniel asks the blunt version: why not just use the builder's sales representative? Stacey's answer is about loyalty: the sales agent "is getting paid by the builder," so "is that the person you want representing you?" She adds that problems can surface right before and after closing, and a buyer who does not know what is normal may accept something they should not. The segment starts at 5:58 in the video.
Builders say the same thing from their side. Taylor Morrison's FAQ on its Ashland page says "you do not need an agent to buy a home" and that its community sales manager "can walk you through the entire process." That is accurate, and it is also the point: the sales manager's job is to sell that builder's homes. Your agent's job is to compare them with other builders' homes and with resale, to pull the MLS history for the specific home you are looking at, to read the incentive terms, to check the SID payoff, and to push back at the walkthrough.
On commission, be precise. In the episode Stacey says the builders pay her fee in today's market. Whether a particular builder pays a buyer's-agent commission on a particular home is a term to confirm with that builder, not something to assume, and your buyer agreement should say what happens if it does not. Decide how you are represented before your first visit to a sales office, not after you have chosen a lot.
Frequently Asked Questions
What is not included in a Summerlin new build's base price?
The lot premium, design-center options, structural options and the backyard are the big ones. Taylor Morrison's disclaimer, read September 28, 2026, says "Prices may not include lot premiums, upgrades and options depending on stage of construction." Its standard kitchen list for Ashland names GE appliances and no refrigerator. In the episode, Stacey Tyler adds that model lighting fixtures and the washer and dryer are often extra. Ask for the included-features sheet for your plan, and treat anything not on it as an option to price.
How much are HOA fees on a new home in Summerlin West?
The Summerlin West master association charges $69 a month in 2026, up from $60, according to the Review-Journal's report on the 2026 budgets. Neighborhood dues come on top. In the MLS on September 28, 2026, available new homes showed neighborhood fees from $65 at Caldwell Park's single-family homes to $199 at Lark Hill's townhomes, and $435 to $542 at Esplanade at Red Rock, for monthly totals of $134 to $611. Ask for the association budget, because the MLS figure is what the listing agent entered.
What is an SID, and how much does it cost in Summerlin?
A special improvement district assessment repays bonds for streets, sewers and other public infrastructure, and it is a lien on the lot. In eight Summerlin West neighborhoods we checked in City of Las Vegas records on September 28, 2026, original assessments ran from $7,730.95 at Lark Hill to $23,253.51 at Ashland, with estimated April 1, 2027 installments of $222.33 to $831.99, billed twice a year, or about $37 to $139 a month. The balance can be paid off at any time and transfers to a buyer at resale.
Is Summerlin a city?
No. Summerlin is a master-planned community, and its address is Las Vegas. The Summerlin West new-construction neighborhoods we checked pay City of Las Vegas special assessments, and the Ashland parcels we checked are in tax district 200, the City of Las Vegas, where the fiscal 2026-27 rate is $3.2782 per $100 of assessed value. Other parts are in unincorporated Clark County, including the Summerlin Town district, 421, at $2.9328. Check the tax district on the Clark County Assessor's record for any lot you are comparing.
Can you negotiate the price of a new build in Summerlin?
Often, especially on finished homes. Of 193 Summerlin homes built in 2025 or later that closed with an MLS sale date between October 2025 and July 2026, 85% sold below their original MLS list price, at a median 94.8% of it. Of 108 available on September 28, 2026, 60 had been reduced, by a median of $37,430. Negotiation usually takes the form of a price cut on a finished home, a waived lot premium, or incentive money applied to options or the rate, not a lower base price.
Do builder rate incentives apply to expensive Summerlin homes?
Often not in full. Taylor Morrison's 4.50% quick move-in rate and 5.49% to-be-built rate, published September 28, 2026, are both limited to conventional conforming loans, and the 2026 conforming limit in Clark County is $832,750. With 20% down, that fits a price up to about $1,040,900. Above that, a buyer needs a larger down payment to use the builder's rate or a jumbo loan at market pricing. Read each builder's terms for the loan type, lender, closing deadline and credit assumptions.
Can I build a big pool on a new Summerlin lot?
Not a very big one. New residential pools in Southern Nevada are limited to 600 square feet of surface area under rules the Las Vegas Valley Water District and local jurisdictions adopted after the Southern Nevada Water Authority's July 2022 resolution. The average pool in the region is about 470 square feet, so most designs fit. If a larger pool is essential, a resale home with an existing pool is the practical route, and the backyard on a new build is usually delivered as dirt.
Ready to Price a Summerlin New Build With Nevada Real Estate Group?
Stacey's closing point is the one this guide is built on: "you don't know what you don't know." A Summerlin base price is honest about what it is, and the costs on top of it are all public: the builder's standard list and incentive terms, the MLS history of homes like yours, the association dues, the City of Las Vegas SID record for your lot, and the Clark County tax district. Putting them together before you sign is our job.
Nevada Real Estate Group is the #1 real estate team in Nevada, with 9,600+ closed transactions, $4.85B+ in total sales volume, 150+ agents, 16+ years in business and 9,061+ verified five-star reviews. In 2025, the team closed 789 homes and $440M+ in volume.
When you are ready, we will build a side-by-side cost stack for the Summerlin communities on your list: base price, lot premium, the options you actually want, backyard allowance, association dues, SID payoff and tax district, and the payment with and without each builder's incentive against an outside lender's Loan Estimate. We will add the MLS history for every comparable home that has sold in that neighborhood, and a resale alternative or two, so the decision rests on total monthly cost.
Call or text us at (702) 637-1759 or email info@nevadagroup.com. Tell us which villages you like, whether you need to move in the next few months, and what monthly payment works for you, and we will start from the homes actually available in Summerlin this week, including Taylor Morrison's communities on our builder page and the rest of Grand Park village on our Grand Park page.
Which Sources Inform This Summerlin New-Build Cost Guide?
- Taylor Morrison, Las Vegas offers page: price disclaimer, 4.50% and 5.49% rate terms and eligible homes, read September 28, 2026.
- Taylor Morrison, Ashland at Summerlin page: base prices, standard features, flex cash terms and FAQ, read September 28, 2026.
- Toll Brothers, Raven Crest: advertised rate and starting price, read September 28, 2026.
- Las Vegas Review-Journal, Summerlin 2026 HOA increases, October 8, 2025: master association rates for 2026.
- Assessment Management Group, SID parcel records: City of Las Vegas SIDs 815, 816 and 817, amounts as of September 28, 2026; individual records are linked in the SID table.
- Assessment Management Group, FAQ: prepayment and transfer at sale.
- Nevada Revised Statutes Chapter 271: special assessment liens and prepayment.
- Clark County Treasurer, tax rates by district: fiscal 2026-27 rates for districts 200 and 421.
- Nevada Revised Statutes Chapter 361: assessment ratio and taxable value.
- Clark County Assessor, 796 Windover Court parcel record: tax district, fiscal 2026-27 values and recorded sale.
- Clark County Assessor, tax abatement: the 3% and up-to-8% caps and the new-construction rule.
- Freddie Mac, Primary Mortgage Market Survey: 7.03% 30-year average as of September 24, 2026.
- Federal Housing Finance Agency, 2026 conforming loan limits: the $832,750 limit.
- Southern Nevada Water Authority, pools and spas: the 600-square-foot pool limit, average pool size and evaporation.
- Las Vegas MLS data pulled through Repliers on September 28, 2026 for homes built 2025 or later in Summerlin plats; see our market report for methodology. MLS figures are not official Las Vegas REALTORS statistics.
- Nevada Real Estate Group, Las Vegas Playbook episode on Summerlin new builds on YouTube, published September 26, 2026.