Moving to Summerlin works best when you test the house against your ordinary week before committing to the move. The same broad community name can describe different governing jurisdictions, association obligations and school assignments. A promising home still needs its own cost sheet, inspection record and realistic move-in plan.
Summerlin's five-ZIP corridor closed at a $635,000 median on 227 sales in September 2026, $200,000 above the Las Vegas MLS-city median, per our November 2026 market report. Summerlin West's 2026 master assessment is $69 a month, but that is one association's charge, not a full budget. Before committing, confirm the parcel's jurisdiction, every association and district charge, the school assignment and the closing timetable.
- Summerlin North and West are in Las Vegas; Summerlin South is unincorporated Clark County. Confirm the individual parcel.
- Association and improvement-district charges depend on the property; do not assume a universal two-fee total.
- Use CCSD's zoning search and enrollment instructions for the school year you need.
- Keep inspections, remote signing, moving delivery and possession dates coordinated.
- Budget cash retained after closing, and check Nevada DMV's 30-day new-resident requirements and exceptions.
This November 2026 review replaces the guide's earlier July market snapshot with figures from our November 2026 Summerlin market report and re-checks the rules cited below. For the broader area overview, use the Summerlin relocation guide; this page concentrates on the decisions between a shortlist and a workable move-in day.
Is Your Summerlin Address in Las Vegas or Unincorporated Clark County?
Summerlin is a master-planned community, not a separate incorporated city. According to the City of Las Vegas Ward 2 description, Summerlin North and West are within the city. According to Clark County's Summerlin South planning page, Summerlin South is an unincorporated town. A Las Vegas mailing address alone does not resolve which local government administers a particular parcel.
Start a property file with the street address, parcel number, jurisdiction and tax district. Match those identifiers across the listing, title materials and assessor record. Then use the appropriate government for questions about permits, proposed additions, home businesses or property use. An association's approval is a separate question from government permission. Neither a salesperson's village description nor a postal ZIP code replaces those checks.
This distinction matters before you spend money on a house you intend to alter. If a home office needs client visits, a garage will become living space, or a future rental is part of the plan, request the applicable requirements before relying on that use. Do not assume a rule from a nearby property applies across a jurisdictional boundary.
Keep your search geography equally precise. The Summerlin listings hub is useful for discovery, while Summerlin Centre provides a narrower starting point. For a finalist, the parcel and recorded documents carry more decision value than a marketing label. Save the dated records you actually used, so a lender, insurer or title officer can resolve discrepancies without reconstructing your search from screenshots.
What Do Homes Cost in Summerlin?
Our November 2026 Summerlin market report counted 227 closings in September 2026 at a $635,000 median, $305 per square foot and 29 median days from listing to contract. It found 1,146 homes listed on November 11, 2026 at a $674,450 median ask. Its figures come from the Las Vegas REALTORS MLS (GLVAR) via Repliers and cover five ZIP codes (89134, 89135, 89138, 89144 and 89145): a corridor that includes some homes outside the master plan and misses a few inside it.
The Las Vegas edition of the same series put the MLS city of Las Vegas at a $435,000 September median on 1,437 closings. The $200,000 gap is about 46% of the city figure, but the two groups overlap, because the Summerlin ZIPs sit inside the MLS city, and they mix houses and condos differently. The gap does not establish what an otherwise identical house costs in Summerlin, prove a location premium, or predict a seller's current negotiating position.
| Report scope | Active listings, Nov 11, 2026 | Median asking price | September 2026 median closed |
|---|---|---|---|
| Summerlin corridor, five ZIPs | 1,146 | $674,450 | $635,000 on 227 closings |
| Henderson | 2,299 | $534,997 | $505,000 on 470 closings |
| North Las Vegas | 972 | $425,000 | $410,000 on 259 closings |
| Las Vegas, MLS city | 8,144 | $450,000 | $435,000 on 1,437 closings |
The Henderson and North Las Vegas rows come from the Henderson and North Las Vegas editions. The newest month's counts can still rise slightly as late closings post, so treat these as dated reference points, then replace them with current comparable properties for an offer. Match housing type, approximate size, condition and association obligations; examine closed sales separately from asking prices. A community-wide median cannot value a specific floor plan. The Summerlin home-cost guide explains the budget categories to carry forward. For your own decision, record when the comparable search was run and which properties were included, rather than treating an undated portal number as a complete appraisal.
Can You Still Build a Search Around a $600,000 Limit?
A maximum price is a useful search filter, but current availability must be checked anew. The November 2026 report does not publish a count of Summerlin listings under $600,000, so this guide no longer gives one. It does split the market by type: on November 11, 2026 the median attached home asked $429,900 and the median house $795,000, and September's closings ran $403,000 for condos and townhomes against $695,000 for houses. A $600,000 ceiling therefore points toward attached homes or below-median houses.
The same report counted 428 listings asking $850,000 or more on November 11, 229 of them above $1.5 million, and 89135 (Summerlin South and The Ridges) carried the highest ZIP median at $847,000 on 48 September closings. Those figures explain why the overall median can hide a broad mix. They do not assign a price tier to every village or establish that a particular attached home is good value.
For a present search, begin with Summerlin condos and townhomes and detached properties within the same total monthly ceiling. New construction is another reference point: Howard Hughes's October 19, 2026 neighborhood update lists townhomes priced from the high $400,000s at Lark Hill by Taylor Morrison and from the mid-$500,000s at Vertex by Tri Pointe Homes. Those are the builders' advertised starting prices; ask each builder in writing what any lot premium or upgrade would add. Confirm the ownership form, parking, stairs, insurance responsibilities and assessments. An affordable asking price can be offset by obligations that a detached-home comparison does not include. Conversely, included exterior maintenance may be useful to someone relocating frequently, provided the association's finances and scope support that expectation.
Expand geography only after identifying the actual constraint. If the binding issue is monthly cost, compare specific Henderson homes and Las Vegas homes with equivalent financing and maintenance assumptions. If it is access to a workplace or school, price alone cannot decide. Keep a short written explanation of why each finalist qualifies, and remove homes that fail a requirement before investing in repeated remote tours.
How Should You Compare Established Villages With New Construction?
Compare the condition and delivery obligations of the actual home before deciding that one village category is better. According to the developer's Summerlin history, development of The Trails began in 1993. That history helps explain why an established neighborhood can have different infrastructure and replacement questions from a new release. It does not reveal the age or condition of every roof, cooling system or remodel within it.
For an established resale, request permits for meaningful alterations, maintenance records, equipment information and the inspection findings that affect immediate work. Visit the street when residents are home, and test the routes you will use. A mature landscape may be appealing, but its irrigation and maintenance obligations belong in the decision. The Trails, Paseos and Vistas pages can organize a shortlist without replacing the property review.
For Summerlin new construction, separate a model's presentation from the written purchase. Ask which finishes, appliances, landscaping and lot features are included; which are upgrades; and which remain the buyer's responsibility. Request the contract's delivery provisions, inspection opportunities and warranty documents. A construction estimate is not a possession guarantee, so retain enough flexibility in your temporary housing and mover arrangements for a changed completion date.
Do not pay for an amenity on the assumption that a rendering shows an operating facility. Verify its actual status, access conditions and funding separately. A useful comparison is a written list of what exists at each home now, what is contractually promised, and what remains planned. That is more reliable than assigning every newer village a fixed price range or every older village the same maintenance burden.
Which Association Fees Actually Apply to the Property?
According to Summerlink's resident guidance, the community has North, South, West and Centre master associations, with the Summerlin Council funded through participating associations. The same guidance identifies exceptions including Sun City Summerlin, Siena and Red Rock Country Club, which have their own master associations and are not Council members. A universal two-HOA formula does not describe every home.
One current, documented example is the Summerlin West assessment notice for 2026: $69 per month per unit. That is the West master assessment. It is not a quote for North, South, Centre, a neighborhood sub-association, club membership or the entire carrying cost of a home. Do not add a separate Council charge unless the property's documents actually require a separate payment.
Make a fee sheet with each payee's legal name, amount, billing frequency, included services and next known change. Ask whether the listing's displayed amount already combines assessments. Divide quarterly or annual charges into monthly equivalents for budgeting, but retain the actual due dates so the payment calendar remains accurate. Request written confirmation of special assessments, transfer charges and unpaid obligations rather than relying only on the ordinary recurring amount.
According to NRS 116.4109, applicable resale packages include governing documents, assessment information, financial materials, certain legal-action disclosures, fees and association insurance information. Review them with the purchase team while the relevant rights and deadlines remain available. A low monthly number is not enough to evaluate reserves, maintenance responsibilities or a planned expense. Use the documents to decide whether the obligations fit your budget and intended use.
How Do You Verify a SID Balance and the Property-Tax Bill?
Treat improvement-district assessments and property taxes as separate questions. According to Clark County's SID payment instructions, SID payments use the parcel number together with the SID district ID, and checks are payable to "Clark County Treasurer-SID." That county procedure does not establish the charges for every city-administered district or prove that a particular Summerlin home has an outstanding balance.
Ask the title or escrow team to identify any assessment affecting the parcel and obtain a current statement from its administrator. Record the installment, next due date, remaining balance and payoff terms. If a seller agrees to pay it at closing, have the agreement and closing statement reflect that treatment. Do not convert a general neighborhood description into an assumed annual bill or a promised number of years remaining.
According to Clark County's property-tax explanation, assessed value is taxable value multiplied by a .35 assessment ratio, and taxable value is generally the land's market value plus the improvements' replacement cost less statutory depreciation, a different measure from the purchase price. According to the county's tax-abatement guidance, a 3% cap applies to the tax bill on an owner's primary residence and a cap of up to 8% applies to residences that are not owner-occupied. A recorded ownership document removes the owner-occupied 3% abatement, so a buyer must claim it again, and new construction qualifies for no cap in its first fiscal year. Do not apply 3% to a price as an estimated annual tax.
Get a parcel-specific estimate that considers the existing bill, proposed ownership, primary-residence qualification and improvements. Confirm what the lender will escrow and what you must pay directly. That produces a usable cash calendar and avoids counting a charge twice. Keep the historical seller bill for context, but do not treat it as a guarantee of your future obligation or use a generic percentage of purchase price as a substitute for the actual assessment process.
What Would a Complete Monthly Budget Look Like?
Use a transparent example to check your spreadsheet, then replace every assumption with property-specific evidence. According to Freddie Mac's PMMS weekly history, the national average 30-year fixed mortgage rate was 7.32% on October 22, 2026 and 7.11% on November 12, 2026. It is a conventional mortgage benchmark, not a personal quote, an APR or a commitment from a lender. Credit, loan structure, points and other terms can change the rate available to you.
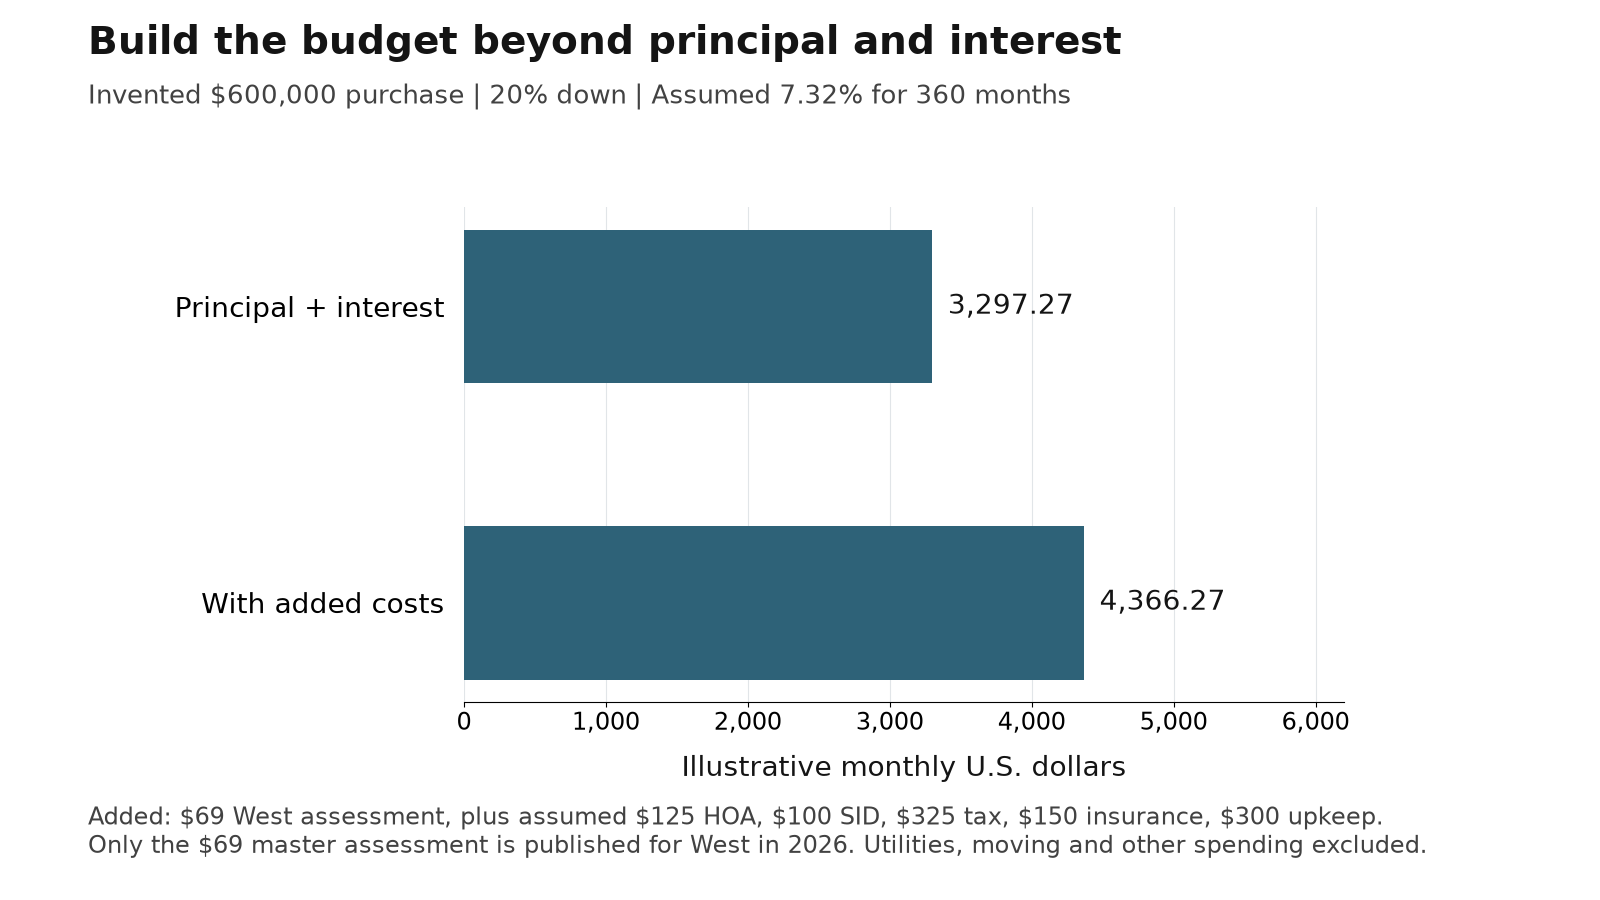
For an invented $600,000 purchase with 20% down, a $480,000 loan amortized over 360 monthly payments at an assumed 7.32% produces $3,297.27 monthly principal and interest. At the November 12 average of 7.11%, the same loan would cost $3,228.99, about $68 less. The example below keeps 7.32% and adds the documented West master assessment only to illustrate a West property, then assumes every other amount below. No actual listing, insurance policy, tax record or SID account supplies those assumed charges.
| Budget item | Monthly amount | Evidence to obtain for a real home |
|---|---|---|
| Principal and interest | $3,297.27 | Actual lender terms; $480,000 at assumed 7.32% here |
| West master assessment | $69 | Property association and current notice |
| Neighborhood assessment | $125 assumed | Applicable association statement |
| SID monthly equivalent | $100 assumed | Actual installment and balance; may not apply |
| Property tax | $325 assumed | Parcel-specific estimate and abatement status |
| Home insurance | $150 assumed | Written quote and exclusions |
| Maintenance allocation | $300 assumed | Inspection findings and household reserve plan |
| Illustrative total | $4,366.27 | Excludes utilities, moving and other household spending |
The $1,069 beyond principal and interest is not a measured Summerlin average. It shows why the loan payment alone cannot determine affordability. If a charge is already escrowed, count the underlying expense once. If a neighborhood assessment or SID does not apply, remove it using the written evidence. For a first purchase, the first-time buyer roadmap can help organize the steps, but the final budget should use your own loan and property rather than this illustration.
How Much Cash Should Remain After Closing and Moving?
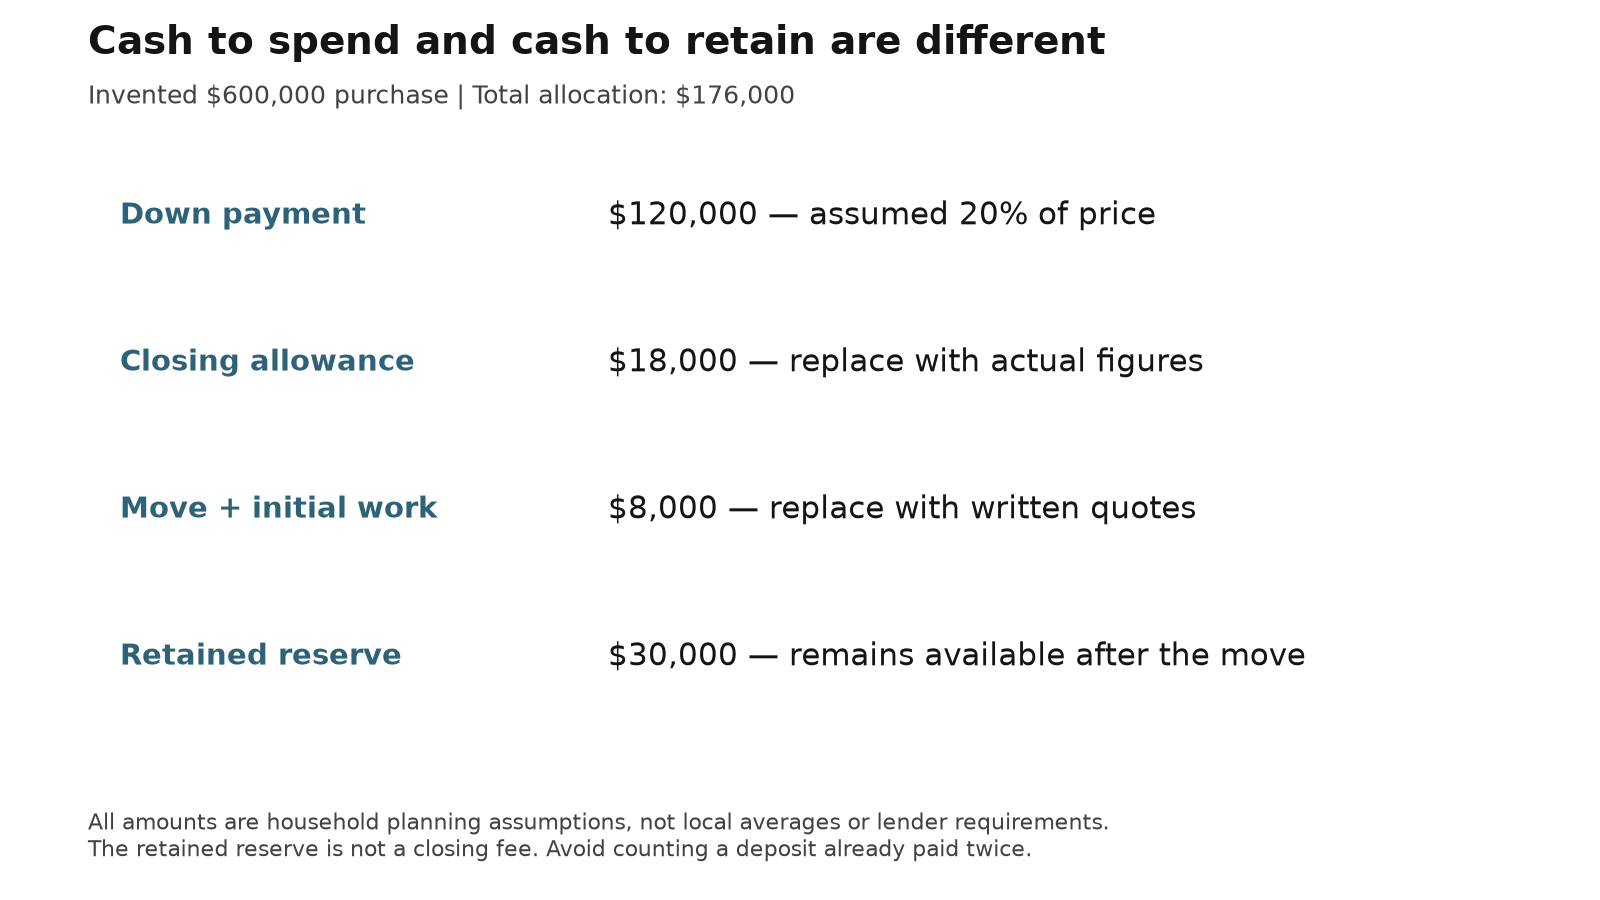
Plan the cash you will spend and the cash you intend to keep available as separate categories. For the invented $600,000 purchase above, the 20% down payment is $120,000. Add an assumed $18,000 closing allowance, $8,000 for moving and immediate work, and $30,000 retained after the move. The total allocation is $176,000. These are household planning assumptions, not Summerlin averages, service quotes or a lender's reserve requirement.
The distinction matters because the $30,000 retained reserve is not a closing fee. It remains your money for future needs. Closing costs, prepaid items, deposits, credits and funds already delivered must be reconciled against the lender and escrow figures so your spreadsheet does not treat the same dollars as both available savings and money already committed. A deposit already paid is not a second down payment at closing.
According to the CFPB's Closing Disclosure guide, the disclosure identifies cash to close and explains the loan's costs and terms. Use the actual document for a covered mortgage transaction. If an existing home sale supplies the purchase funds, coordinate its settlement and transfer timing rather than scheduling a mover on the assumption that sale proceeds are immediately usable.
Keep a separate allowance for temporary housing if the possession date changes, and price that contingency before it becomes urgent. Review any employer relocation reimbursement's timing and eligible expenses in the actual benefit documents. An expected reimbursement cannot pay a deposit before it arrives. The California-to-Summerlin guide can help frame a cross-state comparison, while your cash worksheet should remain tied to your own contracts, available funds and confirmed dates.
How Do You Confirm Schools Before Choosing a Home?
According to CCSD's zoning page, the district provides a Zoning Search for finding your school, along with zoning maps and open-enrollment information. Search with the complete proposed home address for the relevant school year, save the result and resolve uncertainty directly with the district. A village name, nearby campus or listing remark is not an enrollment confirmation. Check each child's grade and the actual start date, especially if your move spans school years.
Treat zoned assignment and an application-based program as different decisions. Do not assume buying nearby establishes admission to a magnet, charter or private school. Obtain the program's current application instructions, acceptance status and transportation arrangements before making a purchase depend on it. This guide does not state a magnet or open-enrollment application deadline or verify a particular household's eligibility.
According to CCSD's enrollment instructions, new families complete online registration and provide required documents to the zoned school. The published checklist covers parent identification, the child's identity, immunization documentation and acceptable proof of address. Its conditional process for a future-dated lease or sales contract requires additional address evidence within 30 days. Ask the school how your particular move and documentation fit that process instead of relying on an informal promise of a seat.
Also test the school-day logistics. Identify drop-off and pickup arrangements, after-school needs and the route from work. Ask about relevant services directly, without inferring quality or fit from a neighborhood's housing price. Compare schools using the programs and support your student needs. The purpose is a confirmed education plan, not a claim that every home in a more expensive village guarantees a better outcome or the same school assignment.
What Should a Remote Home Review Include?
A remote purchase needs several kinds of evidence because each reveals different things. Listing photography helps you identify possibilities. A live walkthrough can follow your questions through the layout. An independent inspection examines the property's condition within the inspector's scope. Disclosures, permits and specialist reports address questions that a video cannot settle. None of these substitutes for all the others.
Prepare the walkthrough in advance. Ask to see the approach, parking, entries, steps, storage and the rooms you will use for work or caregiving. Request views from the windows and outdoor spaces, and note what the camera cannot establish, such as intermittent noise, odors or conditions behind finishes. If a limitation matters, identify who can inspect it and when the answer is due. Do not label an unseen area satisfactory simply because it was absent from the footage.
Use the remote Las Vegas purchase guide to organize the process, then put the actual contract dates and requested reports into one checklist. Coordinate inspection access, report delivery, repair decisions and any contractual notices with your agent and appropriate advisers. A generic relocation timeline does not extend a contract deadline, and this article does not determine your cancellation rights for a specific transaction.
After an inspection, translate material findings into written repair estimates or clear acceptance decisions. Identify which work must occur before occupancy and which can wait. If an agreement calls for seller work, request the agreed documentation and verify completion at the appropriate time. A final walkthrough serves a different purpose from the original inspection: it helps check the property's agreed condition near possession, including whether negotiated work and included items match the contract.
How Do You Coordinate Closing and Protect the Funds?
Ask the lender and closing team to confirm the signing method, required identification, document delivery, funding sequence and possession terms early. Remote signing arrangements depend on the transaction and participants. Do not assume every document can be completed from any location, or that signing automatically means the home is ready for you to occupy. A seller's post-closing possession agreement, if present, needs its own clear dates and responsibilities.
According to the CFPB's Closing Disclosure guidance, borrowers receive that disclosure at least three business days before closing for covered mortgages. Compare it with the Loan Estimate and raise discrepancies with the lender. That requirement is not a universal three-day rule for every cash sale, and it does not supply a guaranteed closing date. Ask the lender how a material change affects your transaction's timetable.
According to the CFPB's closing-fraud guidance, buyers should establish trusted contact arrangements and independently confirm payment instructions. Use a phone number agreed on earlier or another trusted channel, rather than a number or link in a new message requesting a wire. An urgent-looking email, familiar logo or apparent reply in an existing conversation does not verify a changed destination for your funds.
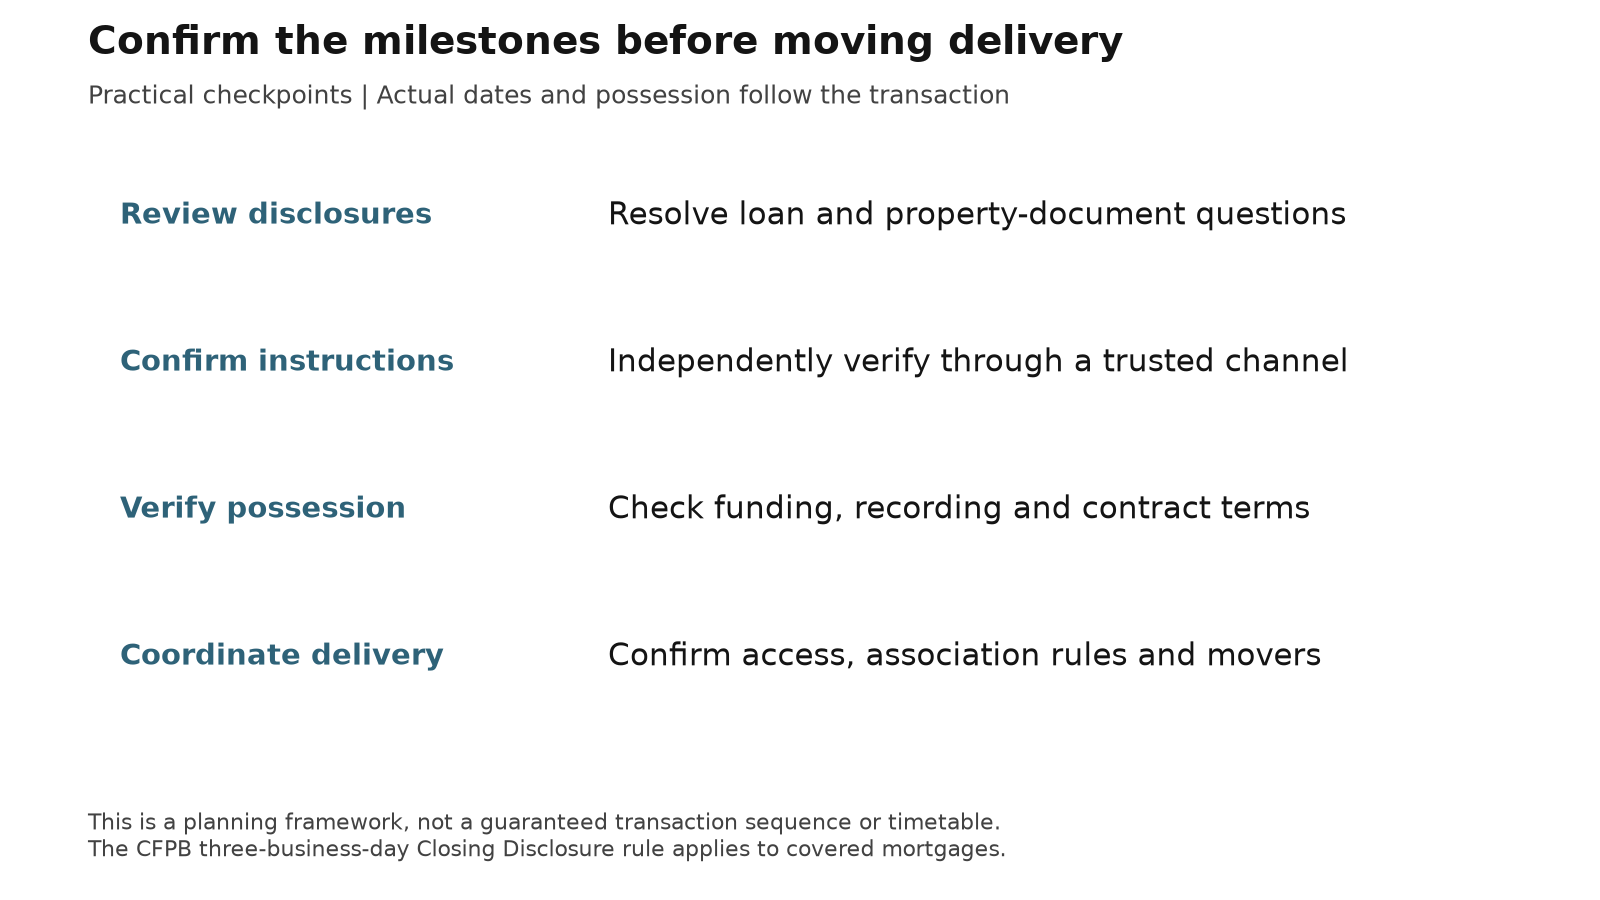
Keep signing, funding, recording, possession and moving delivery as distinct milestones on the shared calendar. Confirm the status with the responsible professional before acting on it. If the transaction needs legal interpretation, obtain appropriate legal advice rather than assuming the use of a title or escrow company answers every question. A workable remote closing is built from verified steps and clear responsibilities, not a promise that distance makes the process automatic.
How Should You Choose Movers and Schedule Delivery?
According to the Federal Trade Commission's moving-scam alert, interstate movers must be registered with the U.S. Department of Transportation, and households should check that registration, get written estimates from several movers, ask what each charges to insure goods and search the company's name for complaints. Also confirm which business will actually transport your belongings and which party is only quoting or arranging the service.
Compare estimates using the same inventory, origin and destination conditions. Disclose stairs, elevators, long carries, large furniture, fragile items and any storage need. Ask how packing, access restrictions, a changed delivery date or an inventory change affects the written agreement. A low headline estimate is not useful if it excludes services you know the move requires. Read the loss-and-damage terms carefully instead of assuming the word insurance means full replacement of every item.
For the destination, obtain the association's current moving-access instructions. Confirm truck parking, gate entry, elevator reservations if relevant, delivery hours and any deposit or certificate requirements. These are property-specific questions; this guide does not assert one moving rule for all Summerlin associations. Give the mover the verified instructions so an access problem does not become a surprise on arrival.
Plan delivery against possession, not merely a hoped-for closing date. Keep documents, medications, essential work equipment and immediate household supplies accessible during transit. If storage or temporary lodging is a realistic contingency, understand its costs and cancellation terms before booking. The same FTC alert says not to sign moving paperwork with blank spaces for prices, dates or signatures, and directs consumers to report interstate moving problems to the Department of Transportation. This article does not endorse a particular mover or claim to have checked a company's current registration on your behalf.
How Can You Test the Commute Without Trusting a Generic Drive Time?
Choose the exact destinations you will visit repeatedly: the workplace entrance, school drop-off, appointments, groceries and any regular airport trip. Test routes at the times you expect to use them, and distinguish a map estimate from an observed trip. A general promise of 20 minutes to the Strip or 25 minutes to the airport does not describe every Summerlin address, shift, road condition or parking arrangement.
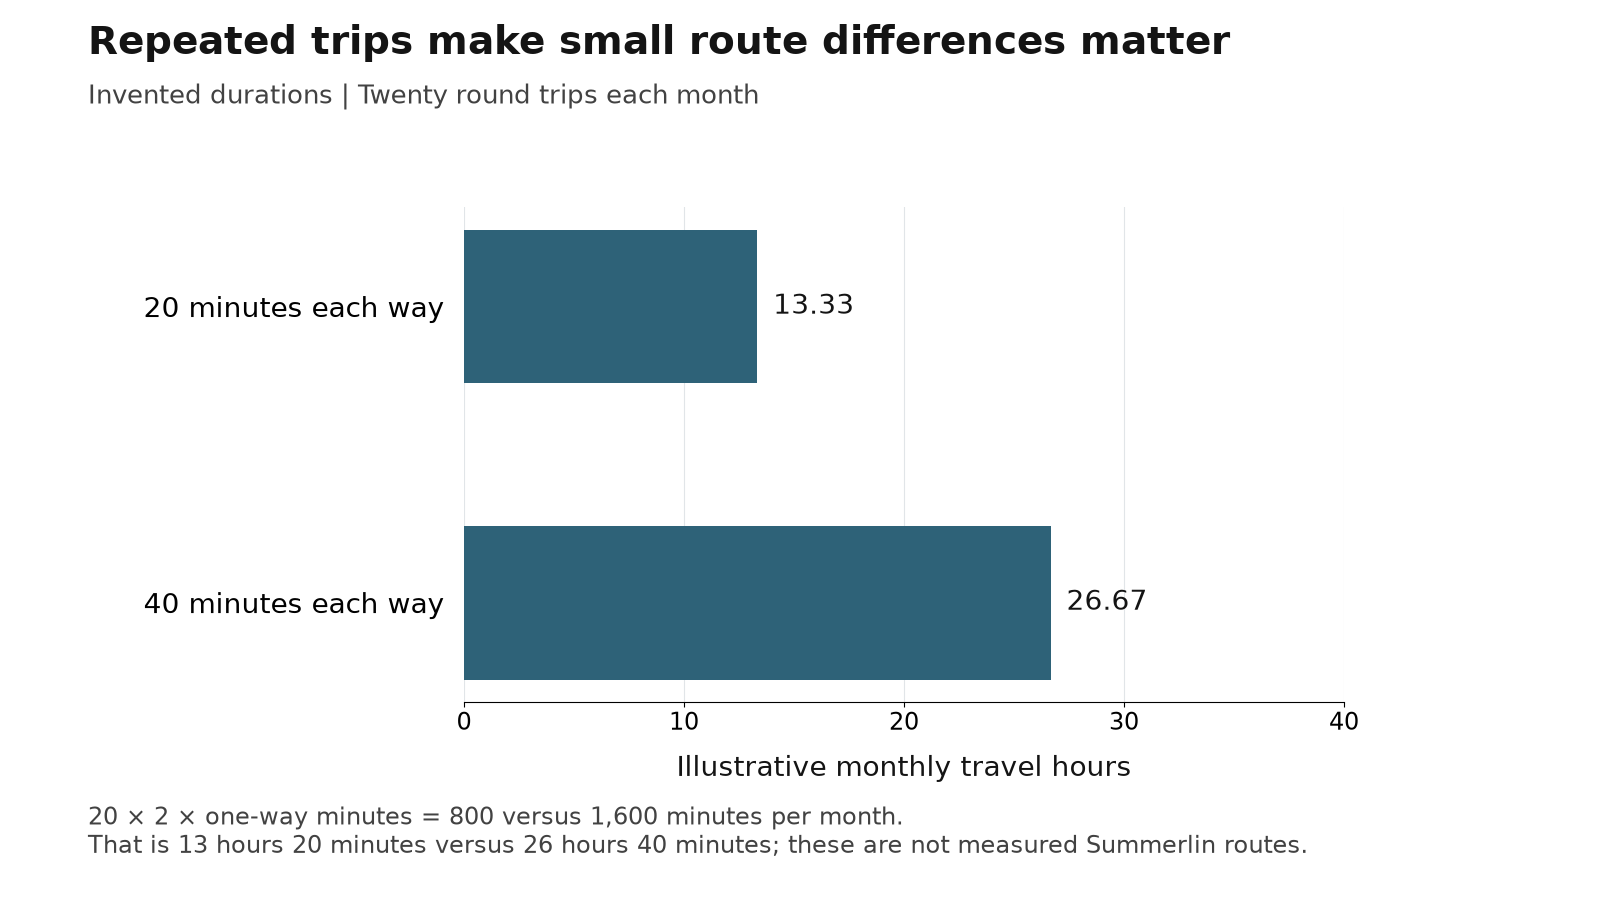
Use a simple calculation to understand repetition. Twenty monthly round trips at an invented 20 minutes each way total 800 minutes, or 13 hours 20 minutes. At an invented 40 minutes each way, they total 1,600 minutes, or 26 hours 40 minutes. The difference is 13 hours 20 minutes per month. These are assumed route durations, not measured Summerlin commutes or traffic forecasts. Replace them with your own timed observations and expected number of trips.
Account for the part beyond driving: walking from parking, a security entrance, an elevator, a shuttle or a school queue can alter the household schedule. If you work from home, verify internet service and workspace suitability at the address instead of automatically treating travel as your largest constraint. If two people have different destinations, compare both schedules rather than optimizing only the first commute discussed.
Use The Ridges, Kestrel or Reverence pages to organize geographically different candidates, then test the real routes. Note the date, departure time and conditions for each observation. A convenient showing-day drive is one data point. Repeating the test around the weekly activities that matter to you provides a more useful basis for choosing a home.
What Should You Check About Utilities, Weather and Daily Life?
Request the property's available utility history and ask what usage it represents. Occupancy, thermostat settings, pool equipment, irrigation and solar arrangements can affect the bills. A previous owner's spending is useful context, but it is not your guaranteed cost. Confirm the service providers for the address, account-transfer requirements and installation dates before assuming the house will support a work-from-home schedule immediately.
Have the cooling system evaluated within the inspection process, and clarify the condition of equipment and any limitations in the report. According to the National Weather Service's heat guidance, hot conditions increase cooling demand and require changes to outdoor activity. Plan a move's physical work around the forecast and suitable breaks. A mountain backdrop does not remove the need for reliable cooling or a practical plan if an essential service is unavailable.
This review does not substantiate a universal Summerlin temperature discount, a community-wide elevation band or a claim that winter snow always melts by noon. Use current forecasts for the actual location and inspect site conditions relevant to the home. Ask qualified inspectors about drainage, exterior wear and other property-specific issues rather than assuming a broad climate description establishes the condition of a lot or building.
Finally, test the daily activities that motivated the move. Visit the grocery store, park, medical office or recreation facility you expect to use, and confirm hours, access and any membership or appointment requirements directly. Check walking connections rather than assuming two nearby points are comfortably connected on foot. The Summerlin community guide gives broader context; your own routine should decide whether the chosen location serves you throughout the week, including the seasons you did not experience on a tour.
What Belongs on Your First-Month Checklist?
According to Nevada DMV's new-resident registration guidance, new residents must obtain their Nevada driver license and vehicle registration within 30 days, subject to the stated residency rules and exemptions. Do not use the moving-truck delivery date as an automatic legal determination of when your residency began. Check the applicable circumstances, especially for military households, students and other exempt situations.
According to DMV's New Resident Guide, preparation involves identity and address documentation, vehicle records, Nevada insurance, a VIN inspection and emissions testing when required. Review the current instructions before booking or visiting, and keep the records where you can access them during the move. School proof-of-address rules and DMV documentation rules are different checklists; satisfying one does not automatically satisfy the other.
| Task | Record to keep | Question to resolve |
|---|---|---|
| Possession and access | Closing confirmation, keys and access instructions | When may you occupy and schedule deliveries? |
| Utilities and internet | Service start and installation confirmations | Which essential services are actually active? |
| Associations and assessments | Account instructions and payment calendar | Which charges are direct, escrowed or paid at closing? |
| School enrollment | District confirmation and required records | What remains before the student's start date? |
| License and vehicle | DMV checklist and appointment details | Which residency deadline or exception applies? |
| Home condition | Inspection, repair receipts and warranty information | Which outstanding work needs scheduling? |
After arrival, reconcile the first bills with the cost sheet. An unfamiliar payee or unexpected amount deserves clarification before you assume it is included elsewhere. Set reminders for the actual association and district billing schedules, and verify any primary-residence tax paperwork with the assessor. Keep a shared list of unresolved items and the party responsible for each answer. That gives the household a practical handoff from purchase to ownership, rather than ending the relocation plan the moment the keys are delivered.
What Do Buyers Ask Before Moving to Summerlin?
Is Summerlin a separate city?
No. Summerlin is a master-planned community spanning municipal and unincorporated areas. The City of Las Vegas identifies North and West within its boundaries, while Clark County identifies Summerlin South as an unincorporated town. Confirm the particular parcel's jurisdiction rather than relying on a Las Vegas mailing address.
Does every Summerlin home have two HOA fees?
Do not assume that. Association structure and applicable charges vary by property, and Summerlink identifies separate master associations and exceptions. Obtain each association's written statement and verify whether the listing already combines charges. The published $69 monthly Summerlin West assessment for 2026 is not a complete cost for every home.
How current are the Summerlin prices in this guide?
The resale figures come from our November 2026 market report: a $635,000 median on 227 September 2026 closings and 1,146 listings on November 11, 2026, across five Summerlin-area ZIP codes. The new-construction starting prices come from Howard Hughes's October 19, 2026 neighborhood update. The newest month's counts can still rise slightly. Current availability and offer pricing require a fresh, property-specific comparison.
Can I choose a home based on the nearby school?
Check CCSD's zoning search for the relevant school year and confirm the enrollment requirements directly. Proximity and a village name do not establish assignment. Magnet, charter and private-school admission may require a separate process; do not make a purchase depend on an acceptance that has not been confirmed.
Can I buy remotely before moving to Nevada?
A remote transaction may be possible, but verify the lender's and closing team's arrangements for your purchase. Use a live walkthrough, appropriate inspections, written disclosures and clear contract dates. Confirm signing, funding and possession separately, and keep moving delivery flexible until the relevant milestones are established.
How much should I set aside beyond the mortgage payment?
Use actual taxes, insurance, association charges, any district assessments, utilities and maintenance needs. The invented example here adds $1,069 to $3,297.27 of principal and interest, producing $4,366.27 before utilities and other spending. It illustrates a method; the assumptions are not a measured Summerlin average or a quote.
Does signing the closing documents mean I can move in immediately?
Do not assume so. Confirm funding, recording and the contract's possession terms with the closing team. A separate seller-possession arrangement can affect timing. Schedule the mover against verified access to the home, and use trusted contact information to independently confirm any instructions for transferring closing funds.
How soon do new residents need a Nevada license and registration?
Nevada DMV publishes a 30-day requirement for new residents, with residency definitions and exemptions. Review the current guide for your circumstances and gather the necessary documents, insurance and vehicle checks early. School enrollment and association onboarding have separate requirements that a DMV appointment does not satisfy.
Which Sources and Next Steps Should Guide Your Move?
This November 2026 review separates three kinds of information: dated market figures from our November 2026 market reports (September 2026 closings and November 11, 2026 listings), rules and instructions checked with public authorities on November 14, 2026, and explicitly invented planning examples. Earlier versions carried a July 13, 2026 snapshot whose listing-level export was not kept; it could not be re-checked, so it has been removed. The calculations show their inputs and exclude costs stated in the relevant captions. They do not describe a quoted property, lender offer, observed commute or household case study.
The factual sources linked beside the relevant passages include the City of Las Vegas and Clark County for jurisdiction and taxes; Summerlink for association structure and the West assessment notice; Nevada's Legislature for applicable resale documents; CCSD for zoning and enrollment; DMV for relocation requirements; the FTC for interstate movers; CFPB for closing documents and fraud prevention; Freddie Mac for the dated rate benchmarks; and the National Weather Service for heat guidance. The developer's Summerlin pages supply village history and builder starting prices; they are an affiliated account, not independent evidence of a price premium. No open-enrollment or magnet deadline is asserted.
Nevada Real Estate Group's 150+ agents have closed 9,600+ Nevada transactions worth more than $4.85 billion. The checklists in this guide are general guidance drawn from the public sources above, not a measurement of those transactions or of how often any problem occurs.
Bring a shortlist, your recurring destinations and the monthly and cash limits you want to maintain. Then compare each home using its current documents, inspections and confirmed move-in requirements. For help organizing that comparison, contact Nevada Real Estate Group at (702) 637-1759 or review available Summerlin homes. The next useful result is a verified property file and feasible move calendar for your household.