Two words stand between most Nevada renters and a serious home search, and almost everyone mixes them up. A pre-qualification is usually a lender's estimate of what you might afford, based on numbers you report. A pre-approval usually means the lender has checked your credit, reviewed your pay stubs, bank statements and tax documents, and issued a letter saying it is tentatively willing to lend a specific amount. The difference matters because, according to the Consumer Financial Protection Bureau, sellers frequently require a preapproval letter before accepting an offer.
This guide covers what the lender pulls and verifies at each stage, how to qualify for a home loan in Las Vegas, what the letter does and does not commit anyone to, the 2026 conforming and FHA loan limits in Clark and Washoe counties, what a credit inquiry costs and the shopping window that lets you compare lenders, what "conditional approval" and "underwriting approval" mean, and the self-inflicted moves that can undo an approval between the letter and the keys. Whether you are shopping Las Vegas, Henderson or Reno, this is a first step worth getting right.
As of November 2026, a pre-qualification is usually a lender's estimate from numbers you report, while a pre-approval usually means the lender checked your credit and verified your finances before naming an amount in writing. Neither is a guaranteed loan offer, and lenders use the terms differently, so ask what was verified. The 2026 conforming limit is $832,750 in Clark and Washoe counties; the FHA limit is $541,287 in Clark and $638,250 in Washoe.
- Pre-qualification can rest on unverified numbers; pre-approval usually means credit checked and finances documented.
- The 2026 conforming limit is $832,750 in Clark and Washoe; FHA is $541,287 and $638,250.
- FICO's newest models count mortgage inquiries inside 45 days as one; one inquiry costs most people under five points.
- Fannie Mae caps debt-to-income at 50% through Desktop Underwriter and ages credit documents out at four months.
- New debt, a job change or an unsourced large deposit can change an approved file before closing.
| Factor | Pre-qualification | Pre-approval | Underwritten pre-approval |
|---|---|---|---|
| Credit checked | Sometimes | Typically yes | Yes |
| Income, assets and debts | Usually as you report them | Verified by the lender | Reviewed by an underwriter |
| Loan Estimate | Not until the lender has all six application items | Same rule; needs a property address | Same rule; needs a property address |
| Guaranteed loan offer | No | No | No |
| What can still fail | Everything, because little was checked | Underwriting review, appraisal, title | Mostly the property |
What Is a Pre-Qualification in Nevada, Really?
The difference is verification: a pre-qualification usually rests on what you tell the lender, and a pre-approval usually rests on what the lender has checked. A pre-qualification is a conversation with math attached. You tell a lender your income, your rough debts and what you have saved, and it hands back an estimate. Often nothing is verified.
According to the Consumer Financial Protection Bureau, lenders use the terms "prequalification" and "preapproval" differently. Some issue a prequalification on unverified information you report, and a preapproval only after verifying it, which means the label on the letterhead tells you less than the process behind it. Lenders may check your credit for either letter. The CFPB is plain about the ceiling on both documents: a letter "is not a guaranteed loan offer." Ask your lender which one it ran and what it actually checked.
There is a second, more technical line, and it applies to both letters. According to the CFPB's Regulation Z definition at section 1026.2(a)(3)(ii), a mortgage "application" exists once the lender has six items: your name, your income, your Social Security number to obtain a credit report, the property address, an estimate of the property's value, and the loan amount sought. If you haven't chosen a home, there is no property address, so no Loan Estimate is due and you receive no standardized disclosure of rate, fees or cash to close.
That makes pre-qualification a fine first step and a weak final one. It answers the private question of whether you are roughly in the game, and at what price range. It suits someone twelve months out, still saving or repairing credit. It is weak support for an offer, because a listing agent who sees one knows the numbers may never have been checked.
What Does a Lender Pull and Verify for a Pre-Approval?
A pre-approval differs from a pre-qualification in one way that matters: the lender stops taking your word for it. You hand over documents, the lender typically checks your credit and verifies what you reported, and then it issues a letter stating the amount it is tentatively willing to lend, subject to the property and final conditions. Once you supply all six Regulation Z items, including a property address, the clock starts. According to the Consumer Financial Protection Bureau, "the lender must provide you a Loan Estimate within three business days of receiving your application." That three-page form lets you compare rate, fees and cash to close across lenders.
According to Freddie Mac, lenders evaluate the file on four C's — capacity, capital, collateral and credit. On capacity, "one of the ways lenders verify your income is by reviewing several years of your federal income tax returns and W-2's, along with current pay stubs." On capital, "lenders may also look at the last two months of statements for your checking and savings accounts, money market accounts, or investment accounts." Collateral — the appraisal — comes later, after you are under contract, which is precisely why no pre-approval can be final.
| Category | What you provide | What they confirm |
|---|---|---|
| Credit | Authorization for a hard pull | Scores, payment history, open trade lines |
| Income | Pay stubs (30 days), W-2s (2 years) | Stable, sufficient, likely to continue |
| Self-employment | Tax returns (2 years), year-to-date profit and loss | Net income after write-offs |
| Assets | Bank and retirement statements (2 months) | Down payment, closing costs, reserves |
| Debts | Pulled from the credit report | Debt-to-income ratio fits the program |
| Collateral | Nothing yet — no property | Verified later by appraisal, not now |
The arithmetic gate is the debt-to-income ratio. According to Fannie Mae's Selling Guide section B3-6-02, dated April 2, 2025, the maximum is 50% for loan files run through Desktop Underwriter, while manually underwritten loans start at 36% and can reach 45% when credit score and reserve requirements are met. That 50% is a ceiling, not a target. Timing and any fee vary by lender, so ask both when you apply.
How Do You Qualify for a Home Loan in Las Vegas?
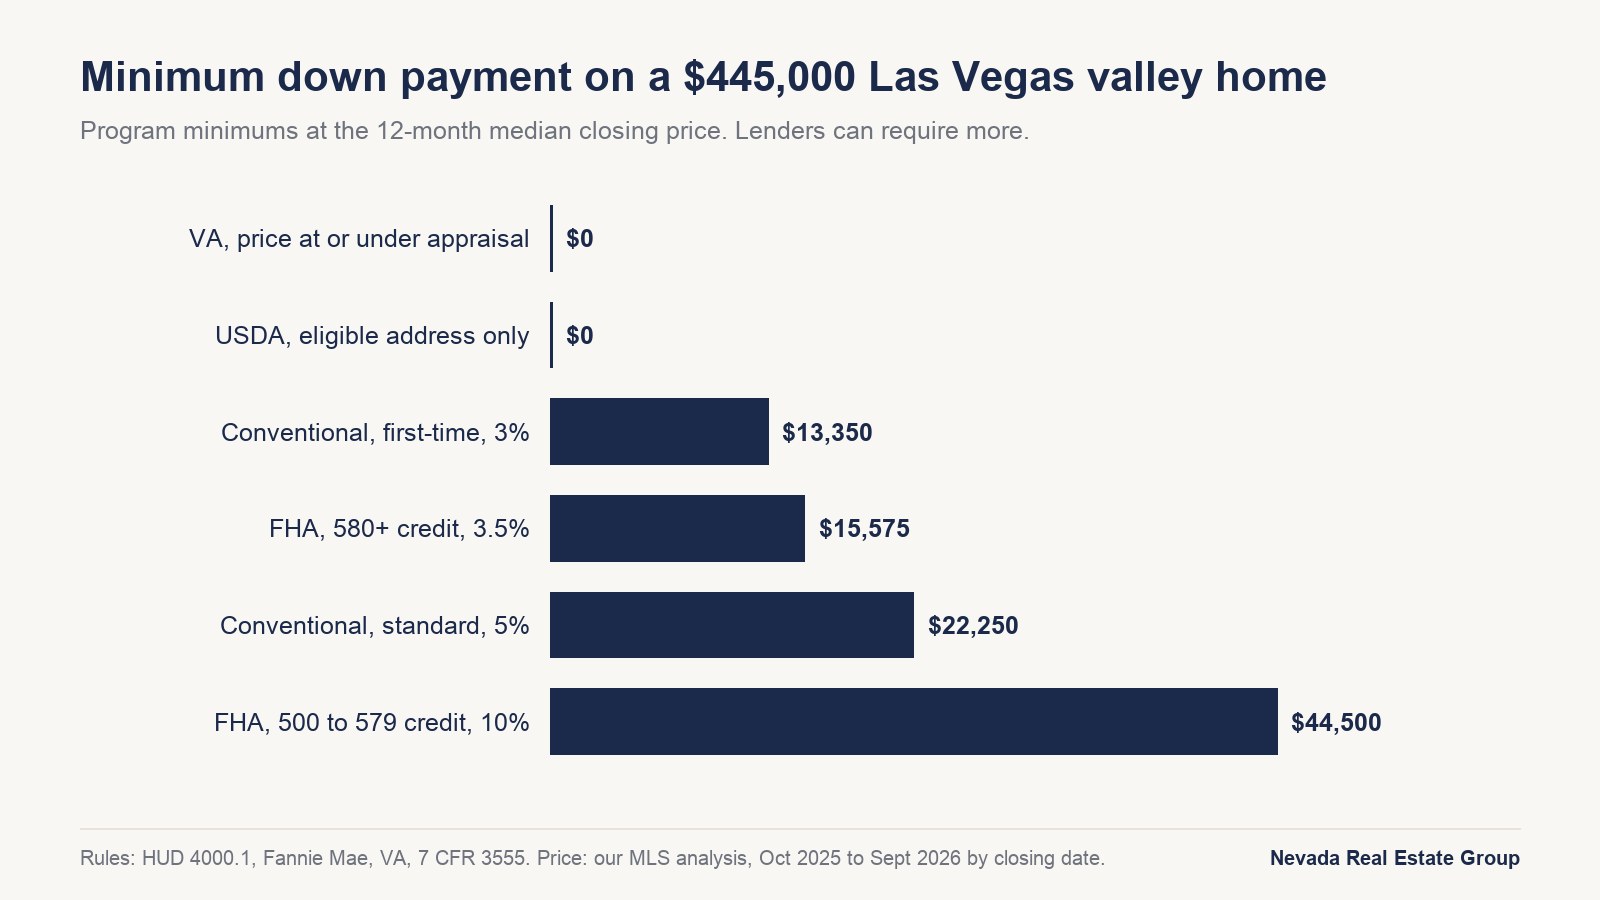
To qualify for a home loan in Las Vegas, you need four things a lender can document: acceptable credit, stable income, a debt-to-income ratio inside your loan's limit, and the cash for your down payment and closing costs. Las Vegas has no qualifying rules of its own. The rules below come from the loan programs, they were read November 1, 2026, and any lender can set stricter ones.
| Loan | Minimum down | Credit score | Debt-to-income | 2026 Clark County limit |
|---|---|---|---|---|
| FHA | 3.5% at 580 or higher; 10% at 500 to 579 | Below 500 is not eligible | Manual approvals run 31/43 up to 40/50 with compensating factors; higher takes an automated approval | $541,287 loan limit |
| Conventional (Fannie Mae) | 3% for first-time or HomeReady buyers; otherwise 5% | No fixed minimum in Desktop Underwriter; 620 on manual fixed-rate loans | 36% manual, up to 45% with credit and reserves; 50% in Desktop Underwriter | $832,750 loan limit |
| VA | $0 when the price is not above the appraised value | VA sets no minimum; lenders may | 41% is a guide; residual income comes first | No VA limit with full entitlement |
| USDA guaranteed | $0 when the loan fits the appraised value and costs | Regulation sets no number; lenders and USDA's system decide | 29/41, with exceptions for compensating factors | Income limit and an eligible address; Las Vegas, Henderson and North Las Vegas are not eligible |
The sources are HUD Handbook 4000.1 and Mortgagee Letter 2026-11, Fannie Mae's credit score and down payment pages, VA's Lenders Handbook, chapter 4, VA's loan limits page, and USDA's 7 CFR 3555.103 and 7 CFR 3555.151. The USDA address note comes from our October 12 map check, so confirm your address on USDA's tool.
Income is the next test. Lenders generally want about two years of history: W-2s and pay stubs for employees, and two years of returns plus year-to-date figures for self-employed and tipped buyers. On the $445,000 median closing price below, 3.5% down is $15,575 and 5% down is $22,250, and closing costs come on top. The table sets floors, so it can't tell you which loan is cheapest or what you personally qualify for. Our FHA vs conventional guide compares the costs, and a pre-approval gives you your own answer. Jumbo and bank-statement loans follow lender rules that aren't covered here.
What Do Conditional Approval and Underwriting Approval Actually Mean?
Buyers hear four different phrases and assume they are synonyms. They are lender terms rather than regulated ones, so ask what each letter means. A pre-qualification is an estimate. A pre-approval usually means a loan officer verified your file. A conditional approval means an actual underwriter reviewed the file and issued a written approval subject to a list of outstanding conditions — sometimes trivial ones such as a missing statement page, sometimes substantive ones such as sourcing a deposit or documenting a gap in employment. A fully underwritten pre-approval, which some lenders brand "certified," "verified" or "commitment" approval, is a conditional approval obtained before you shop, where the remaining conditions are essentially just the property: appraisal, title and insurance.
The table near the top of this guide sets the three side by side, and the row worth reading twice is the one describing what can still fail. With a pre-qualification, everything can still fail, because little was checked. With a standard pre-approval, your file has usually been reviewed by a loan officer but not yet cleared by an underwriter, so a surprise such as an unusual income structure or a disputed collection account can still surface late. With an underwritten pre-approval, the underwriter has already reviewed you, and the main open question is the house.
Every step up that ladder moves risk away from the seller. National data shows why a seller might care. According to the National Association of REALTORS' September 2026 REALTORS Confidence Index, published October 13, 2026, 7% of contracts were terminated in the preceding three months, 16% had delayed settlements, and 5% were delayed by appraisal issues. A seller who accepts your offer takes the home off the market for the length of escrow against those odds.
A fully underwritten pre-approval takes more work up front, because your complete file goes to an underwriter before you shop. Ask the lender how long that takes and whether it costs anything, because both vary.
A basic pre-approval letter may contain hedge language such as "subject to verification of income and assets," which tells a listing agent the documents have not been through underwriting. A conditional approval lists the open conditions, so the agent can see what is still unresolved.
In a multiple-offer situation, an underwritten buyer may be able to shorten the financing contingency and close faster, which speaks to reliability rather than price. We covered the full offer in our bidding-war playbook. If you expect competition on well-priced homes in Henderson or Sparks, ask about underwriting up front before you start touring.
What Are the 2026 Conforming and FHA Loan Limits in Clark and Washoe Counties?
A pre-approval cannot exceed the program's ceiling, so the loan limits set the outer boundary of your search before any lender opens a file. According to the Federal Housing Finance Agency's announcement of November 25, 2025, the 2026 baseline conforming loan limit for one-unit properties is $832,750, up $26,250 from $806,500 in 2025 — an increase that matches the 3.26% rise in FHFA's house price index. Both Clark and Washoe counties sit at that baseline for 2026; neither gets the $1,249,125 high-cost ceiling.
FHA is where the two counties diverge sharply. According to HUD's announcement of December 11, 2025, the 2026 FHA floor for one-unit properties is $541,287 and the ceiling is $1,249,125, with county limits derived from local median sale prices. HUD's published CY2026 limit file puts Clark County at the national floor, because the $462,000 median HUD used produces a calculated limit below it. Washoe County lands above the floor on a $555,000 median.
| Limit | Clark County | Washoe County |
|---|---|---|
| Conforming, 1 unit | $832,750 | $832,750 |
| Conforming, 2 units | $1,066,250 | $1,066,250 |
| Conforming, 4 units | $1,601,750 | $1,601,750 |
| FHA, 1 unit | $541,287 | $638,250 |
| FHA, 2 units | $693,050 | $817,050 |
| FHA, 4 units | $1,041,125 | $1,227,400 |
| Median HUD used | $462,000 | $555,000 |
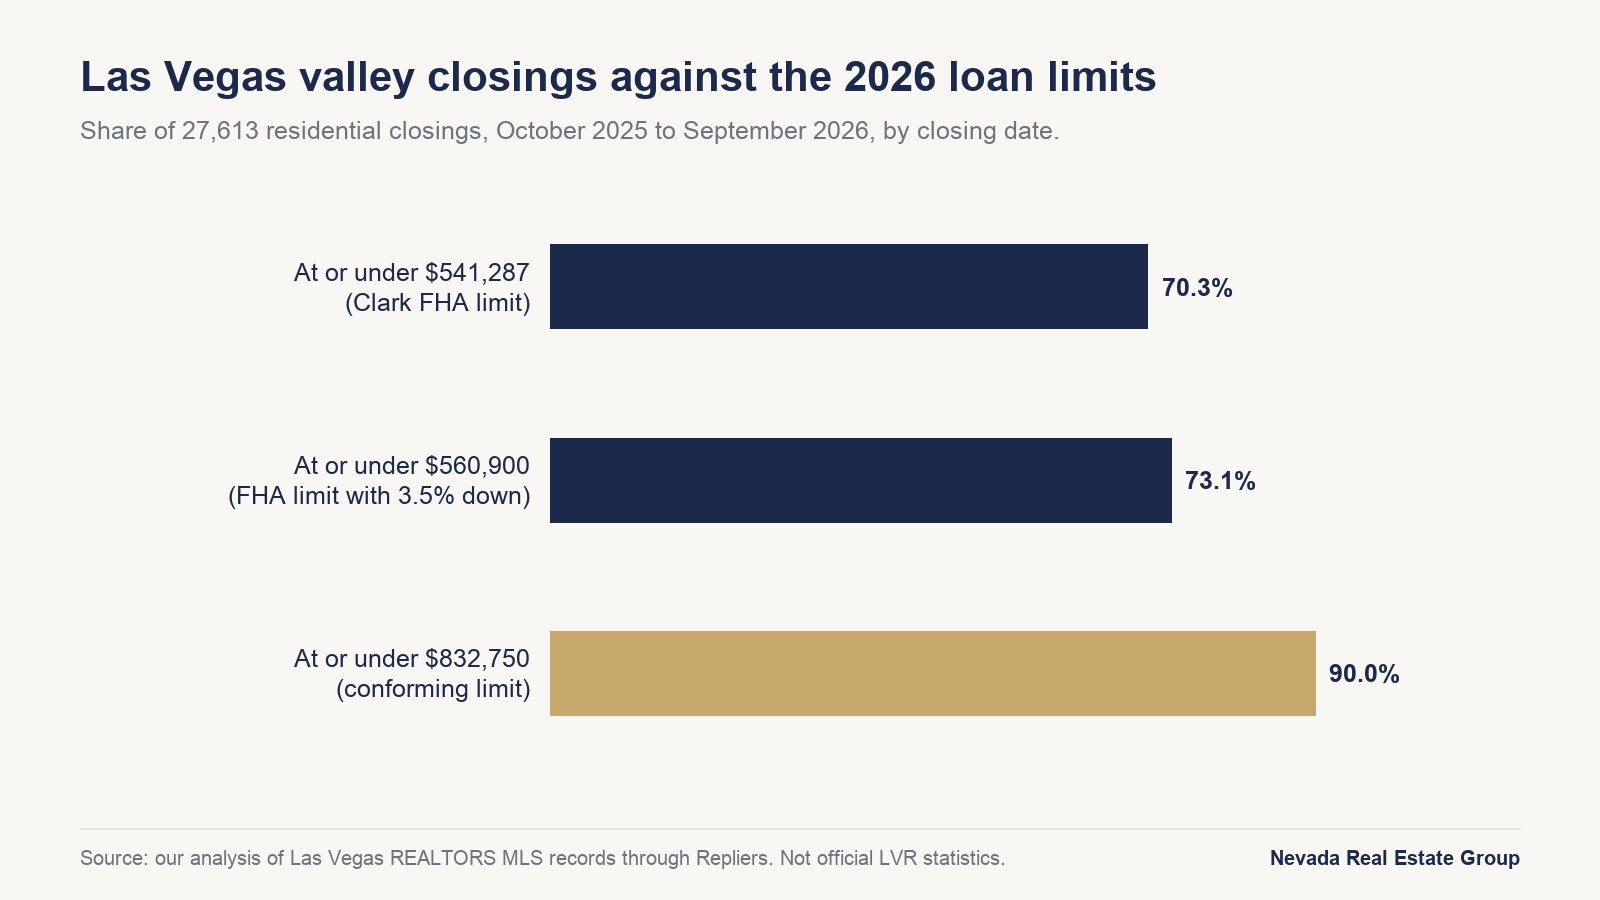
The practical translation for a Southern Nevada buyer: FHA covers most of the market but not the top of it. Of the 27,613 residential closings in Las Vegas, Henderson, North Las Vegas and Boulder City from October 2025 through September 2026, counted by closing date in our analysis of MLS records through Repliers, 70.3% closed at or below $541,287 and 90.0% closed at or below $832,750. With 3.5% down, a buyer's base loan reaches the FHA limit at a price of about $560,900, and 73.1% closed at or below that. A Washoe County buyer gets $96,963 more FHA room than a Clark County buyer, which matters in Reno, where the median closing was $580,955 over the same 12 months. Above the conforming line you are in jumbo territory, where each lender sets its own standards.
What Does a Pre-Approval Amount Mean for Your Real Nevada Budget?
A letter gives you a number, but what does it look like in cash and monthly payment? According to Freddie Mac's Primary Mortgage Market Survey, the 30-year fixed-rate average was 7.24% and the 15-year average was 6.60% for the week of October 29, 2026. The table below runs three Nevada price points at that 30-year average. These are worked examples from published averages, not a quote and not a forecast. We are a brokerage, not a lender, and your actual rate comes from your lender's lock.
| Metric | $445,000 valley median | $560,900 FHA limit at 3.5% down | $581,000 Reno median |
|---|---|---|---|
| 3.5% down (FHA) | $15,575 | $19,632 | $20,335 |
| 20% down (conventional) | $89,000 | $112,180 | $116,200 |
| Base loan at 3.5% down | $429,425 | $541,269 | $560,665 |
| Principal and interest, 3.5% down | about $2,927 | about $3,689 | about $3,821 |
| Principal and interest, 20% down | about $2,426 | about $3,058 | about $3,168 |
| Gross income at 45% DTI with $800 other debts | about $99,400 | about $119,700 | about $123,200 |
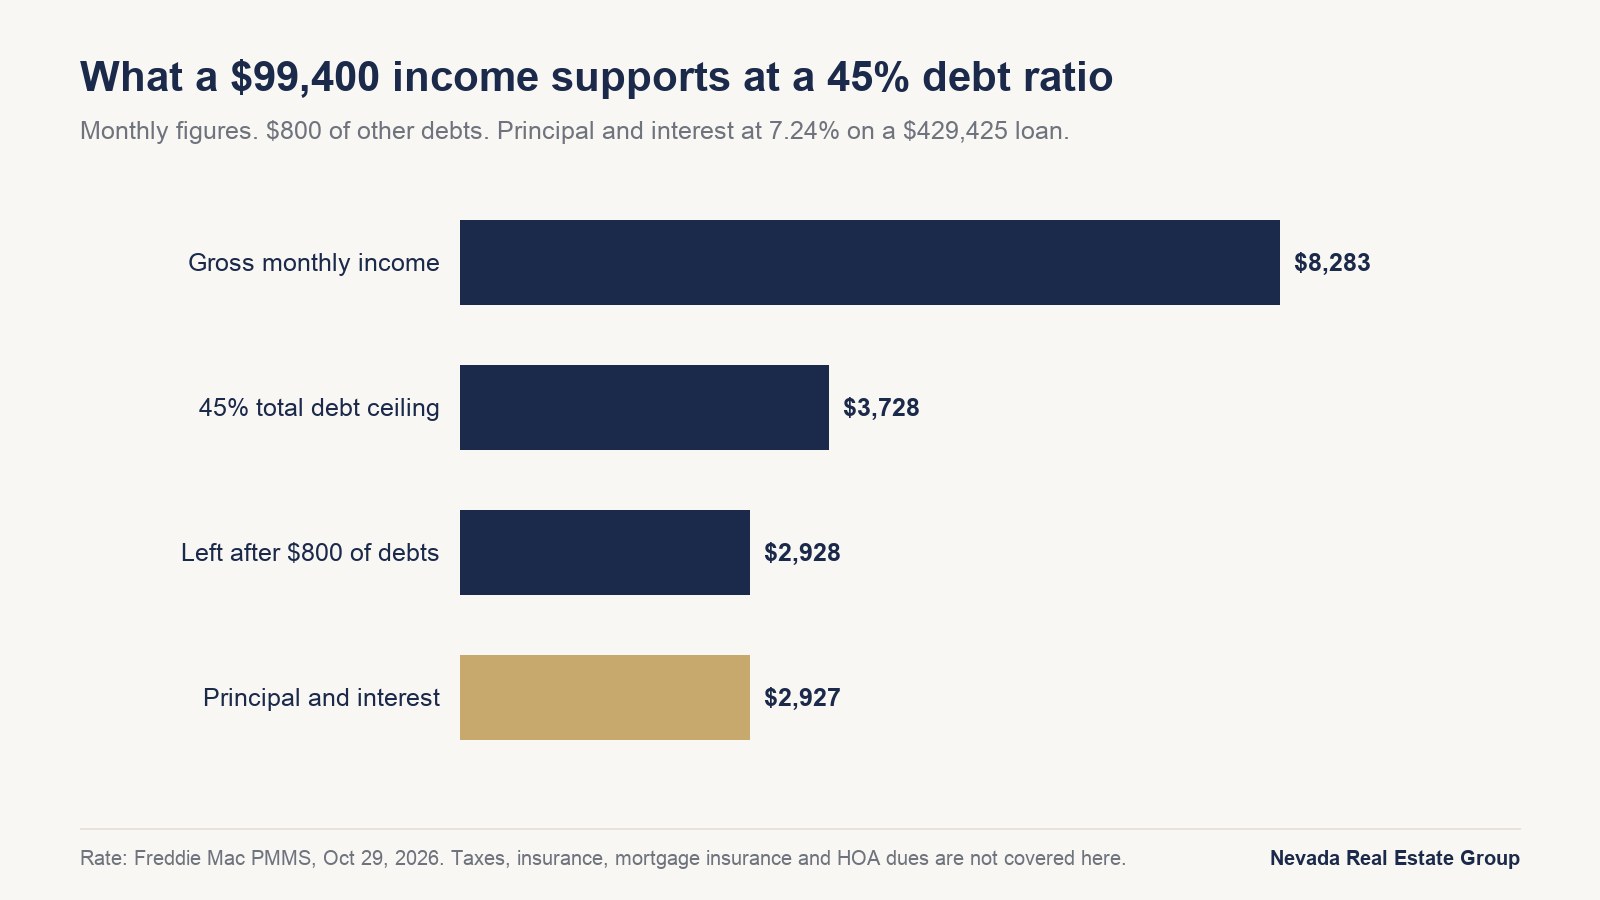
Walk one example through. A household earning $99,400 a year grosses about $8,283 a month. At a 45% debt-to-income ceiling that is roughly $3,728 of total monthly debt capacity. Subtract $800 of other debts and about $2,928 is left, which is the principal and interest on a $429,425 loan at 7.24%, the median valley home with 3.5% down. Nothing in that figure covers taxes, insurance, mortgage insurance or HOA dues, which is why the approved number and the livable number are different.
Nevada property tax is worth understanding rather than guessing. According to the Clark County Assessor, assessed value equals 35% of taxable value, and the tax is the assessed value multiplied by the district rate per hundred dollars. The Assessor's worked example applies a rate of 3.2782 to a $70,000 assessed value for $2,294.74 a year. Taxable value is not the same as your purchase price, and a sale does not reset the tax. Nevada caps the yearly increase at 3% on a primary residence and up to 8% on other property, and Clark County warns that any recorded ownership document removes the 3% abatement, so a new owner has to claim it. Pull the actual parcel record before you budget.
Two rules of thumb. The approved maximum is the ceiling, not the target: with 3.5% down at 7.24%, shopping at $410,000 instead of $445,000 keeps about $230 a month of room. And remember the cash beyond the down payment. According to the CFPB, closing costs typically run 2% to 5% of the purchase price, roughly $8,900 to $22,250 on the median home, plus the earnest deposit, which must be liquid on day one.
Does Getting Pre-Approved Hurt Your Credit Score?
Barely, for most people. According to FICO, "for most people, one additional credit inquiry will take less than five points off their FICO Scores," hard inquiries "stay on the report for up to two years, but they only affect the FICO Scores for a year," and for loans that commonly involve rate shopping — mortgage, auto and student — "FICO Scores ignore inquiries made in the 30 days prior to scoring."
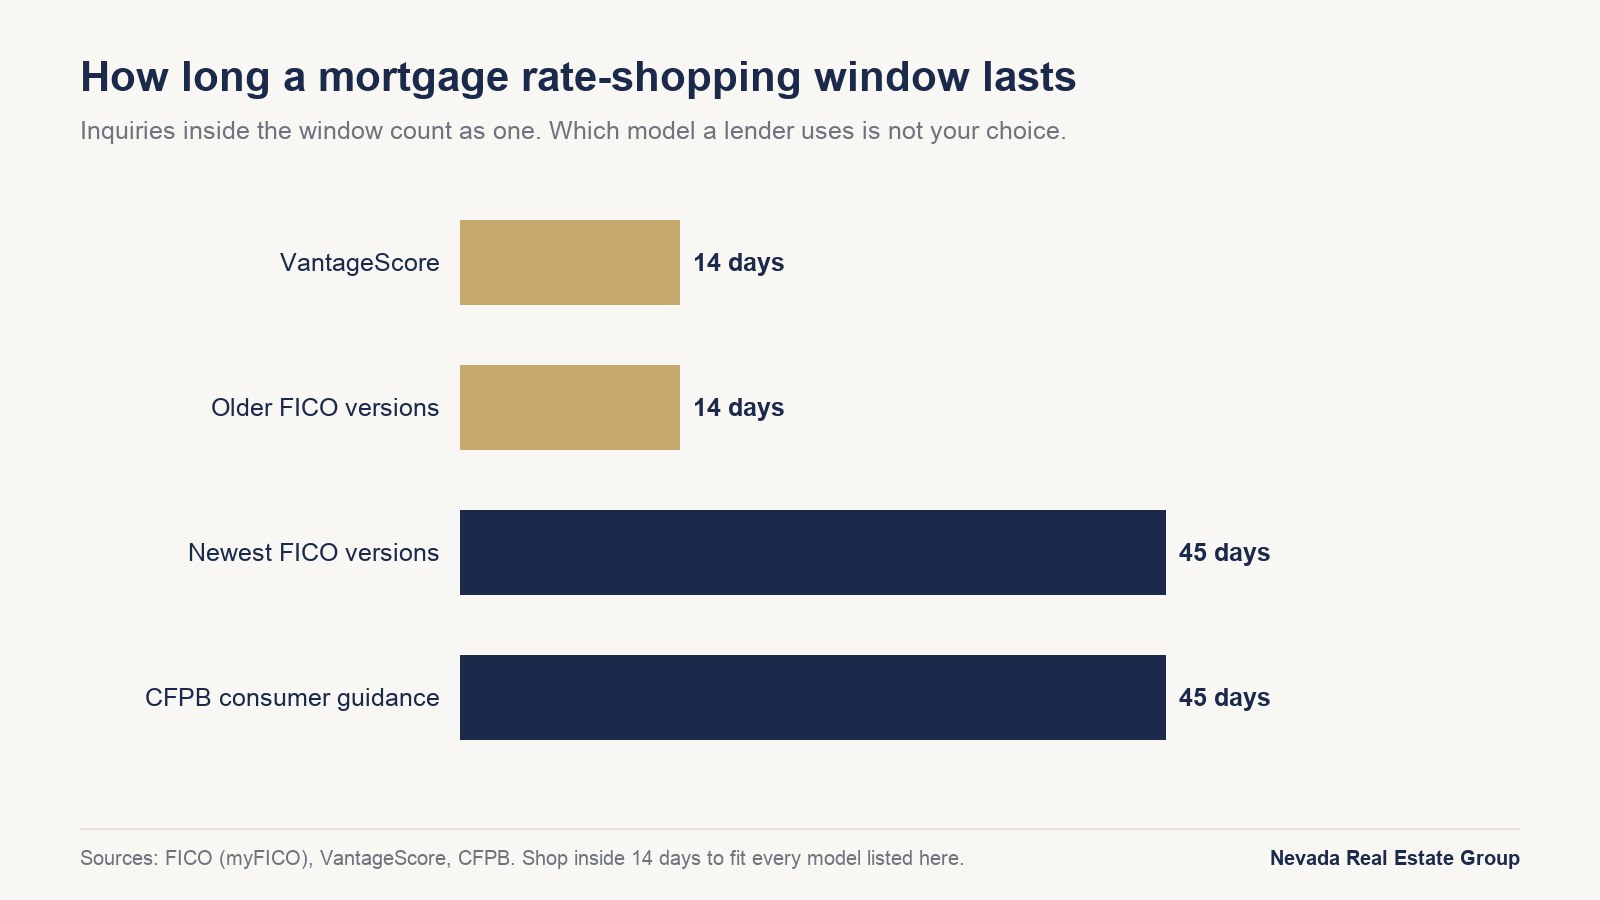
The shopping window is the part most articles get wrong by stating a single number. According to FICO, the deduplication period depends on which version of the model a lender runs: "for FICO Scores calculated from older versions of the scoring formula, this shopping period is any 14-day span. For FICO Scores calculated from the newest versions of the scoring formula, this shopping period is any 45-day span." VantageScore uses a 14-day rolling window for mortgage and auto inquiries. The Consumer Financial Protection Bureau states the consumer version plainly: "Within a 45-day window, multiple credit checks from mortgage lenders are recorded on your credit report as a single inquiry," because "other lenders realize that you are only going to buy one home."
The safe rule, given that you cannot control which model version your lender pulls: cluster every mortgage inquiry inside 14 days, and you fit both the old and new windows. Do not spread your lender shopping across six weeks.
So get pre-approved, and compare more than one lender while you are at it. Rates, fees, and lock and float-down terms vary by lender, as we covered in the rate-strategy guide. The real caution is timing everything else: the months around a mortgage application are the wrong time to open a credit card, finance furniture or take a car loan, because new debt raises your debt-to-income ratio. According to the FTC, you can pull your own reports for free at AnnualCreditReport.com, so check them and dispute any errors first.
How Long Does a Pre-Approval Last, and What Invalidates It?
A pre-approval letter is perishable, and the expiration is shorter than most buyers assume. According to the Consumer Financial Protection Bureau, a preapproval letter can have "an expiration date on it (typically 30 to 60 days)." Check the date on yours, because an expired letter on an offer helps no one.
Underneath the letter's own date sits a harder deadline set by the investor. According to Fannie Mae's Selling Guide section B1-1-03, dated April 2, 2025, "the credit documents must be no more than four months old on the note date." That clock covers credit reports and employment, income and asset documents alike. If your search runs long, plan on sending updated pay stubs and statements.
The more dangerous failure is the self-inflicted kind: the approval that dies between the letter and the closing. According to Fannie Mae's Selling Guide section B3-6-01, "if the borrower discloses, or the lender discovers, additional liabilities after the underwriting decision has been made, up to and concurrent with closing, the lender must recalculate the borrower's debt-to-income ratio." That single sentence is why a financed car at week three of escrow is not a small problem.
Large deposits get the same treatment, and the threshold is specific. According to Fannie Mae's Selling Guide section B3-4.2-02, a large deposit is "a single deposit that exceeds 50% of the total monthly qualifying income for the loan," and on a purchase the lender must document the source of any such funds used for the down payment, closing costs or reserves. On a $99,400 household income, that trigger is roughly $4,142. A single transfer, a gift or a lump-sum side payment can cross it. The rule from letter to keys is simple: change nothing. Same job, same accounts, same debts, no new anything, and document any deposit before it lands. Buy the furniture after you close.
What Documents Do You Need, and How Do You Vet the Lender?
Gather the file in advance. The standard W-2 employee package: 30 days of pay stubs, two years of W-2s, two months of statements for every account funding the purchase, two months of retirement or investment statements if those funds count toward reserves, and a photo ID. Self-employed buyers add two years of personal and business tax returns plus a year-to-date profit-and-loss statement. Veterans add the Certificate of Eligibility; according to the U.S. Department of Veterans Affairs, a COE "confirms for your lender that you qualify for the VA home loan benefit," and "your lender may be able to use an online system (called Web LGY) to get your COE."
Two practical tips. First, send complete documents the first time: every page of every statement, including the blank ones. Second, be upfront about wrinkles such as an employment gap, a past short sale, alimony or side income you want counted, because underwriting will find them anyway.
Then vet the lender itself. According to the Nevada Division of Mortgage Lending, the Division provides licensing and regulatory services for mortgage professionals. That covers mortgage companies and loan originators under NRS Chapter 645B. It takes consumer complaints and can be reached at 702-486-0782. Its licensee search page points consumers to NMLS Consumer Access for mortgage companies and mortgage loan originators. Ask for the NMLS ID, look it up, and keep the record.
How Do Self-Employed, Tipped and Commissioned Buyers Get Pre-Approved?
This is not an edge case in Southern Nevada. According to the U.S. Bureau of Labor Statistics, the Las Vegas-Henderson-North Las Vegas metro area had a preliminary 1,190.5 thousand nonfarm jobs in September 2026, of which 302.8 thousand were in leisure and hospitality, about 25% of all jobs.
The mechanics differ from a salaried file in three ways. First, variable income generally needs a documented history rather than a current pace. Second, self-employed borrowers are qualified on net income after business write-offs, not gross receipts — the aggressive deductions that lower your tax bill also lower your approval amount, and that trade-off has to be planned a tax year in advance, not discovered at application. Third, tipped income that is declared and reported on W-2s behaves very differently in underwriting from cash income that never appears on a return. Underwriters cannot count income they cannot document.
The operating advice is therefore timing. If you are self-employed, tipped or commission-paid and you intend to buy inside the next two years, talk to a lender before your next return is filed, so the write-off strategy and the approval strategy are set together rather than in conflict. Bring two years of returns, a year-to-date profit-and-loss statement, and the business license or 1099s to the first conversation.
Our deep-dive on self-employed and tipped income mortgages in Las Vegas covers the documentation and averaging rules. Start there if your income is variable, because the pre-approval process is the same but the evidence required is not.
Which Credential Should You Get, and When?
Map the credential to where you actually are in the process. Twelve or more months out, still saving or repairing credit: pre-qualify, learn your range, and work the plan, because there is no reason to start a four-month document clock this early. One to three months from shopping: get the full pre-approval, then interview agents and start touring with the letter in hand. Ready now, in a competitive segment: ask about a fully underwritten pre-approval.
The sequencing matters because of what the pre-approval unlocks. Your offer range becomes real. Your monthly payment becomes concrete, including how a seller-funded buydown or a rate lock might change it. And you learn early whether your file has a wrinkle that needs fixing, such as a disputed collection or a co-signed loan you forgot about, while there is still time.
Down-payment help fits the same timeline. The Nevada Housing Division runs its assistance through participating lenders, so an approved lender can review it in the same conversation; our Nevada assistance guide covers the programs. If you are buying new construction, a builder's affiliated lender may want its own pre-approval even when you arrive with an outside letter, so compare the two Loan Estimates side by side before you take the builder incentive. See our new construction overview for how those incentives are typically structured.
Does the Credential Matter More in Las Vegas or Northern Nevada?
It matters in both, for different reasons. The Las Vegas valley has more inventory, and northern markets have less. According to Las Vegas REALTORS' September 2026 report, as reported by FOX5, 7,995 single-family homes and 2,796 condos and townhomes were listed without offers at the end of the month, and LVR put the sales pace at about a five-month supply. Our MLS analysis counted 27,613 valley closings from October 2025 through September 2026 by closing date, with a median of $417,995 in North Las Vegas.
Northern Nevada has a thinner supply. Over those same 12 months, Northern Nevada Regional MLS records through Repliers show 4,125 Reno closings at a $580,955 median and 1,762 Sparks closings at a $535,000 median. On November 1, 2026 there were 815 Reno and 332 Sparks residential listings active and not under contract, or about 2.4 and 2.3 months at the 12-month closing pace. When the right house appears in a specific Sparks or Carson City pocket, a buyer who still needs to assemble a pre-approval starts behind one who has it.
Individual communities can behave like thin markets even in a large county, because a specific floor plan in Henderson or Summerlin may rarely list. The same order works everywhere: get the letter before the touring. You can watch the current numbers on our market report between now and the day you are ready.
What Mistakes Do Buyers Make With Pre-Approvals?
The recurring errors are each avoidable. Shopping with a pre-qualification when an offer needs more. Getting pre-approved by exactly one lender and never seeing other rates or terms; clustering the pulls inside 14 days fits the scoring windows above. Treating the approved maximum as the budget: a lender's limit, up to 50% in Desktop Underwriter, is what you can borrow, not what you should carry.
Timing the letter wrong so it expires mid-search, or letting the four-month document clock run out on the credit report. Making financial changes during escrow: the car, the card, the job change, the unsourced transfer from a relative. Hiding wrinkles from the loan officer that underwriting will find anyway.
Two more that cost quietly. First, not asking the lender to run your file across multiple programs: the same buyer can price differently on conventional, FHA and VA paths, and in Clark County the FHA limit of $541,287 versus the conforming $832,750 can change which houses are reachable. Second, not comparing Loan Estimates line by line. Each lender must send one within three business days of receiving your application, on a standardized three-page form, so the fees and points are easy to compare.
The letter is only useful if the offer around it works. Nevada Real Estate Group is the #1 real estate team in Nevada, with 9,600+ closings and $4.85B+ in total sales volume across a 150+ agent team, 789 homes closed in 2025 alone, and 9,097+ verified five-star reviews. We are a brokerage, not a lender: we do not originate loans, quote rates or predict them.
What we do is help you time the letter so it is current when the right home appears, read what it does and does not say, and line up the deposit, contingency periods and close date in your offer. If you are ready to trade estimates for real numbers in Las Vegas, North Las Vegas or Reno, call our Southern Nevada team at (702) 637-1759 or our Northern Nevada team at (775) 277-2120, or contact us here.
Frequently Asked Questions
What is the difference between pre-qualification and pre-approval?
Pre-qualification is usually an informal estimate based on numbers you report. Pre-approval usually means the lender checked your credit and verified your income, assets and debts, then put a specific amount in writing. According to the Consumer Financial Protection Bureau, lenders use these labels differently, so ask which process they ran and what they verified. Neither document is a guaranteed loan offer. Use a pre-approval rather than a pre-qualification when you write an offer.
Does a pre-approval guarantee I will get the mortgage?
No. The CFPB states plainly that a preapproval letter "is not a guaranteed loan offer," and that getting one does not commit you to that lender either. Final approval still requires an acceptable property, plus finances that have not changed. A financed car, new credit cards, a job change or an unsourced large deposit can change an approved file. A fully underwritten pre-approval deals with more of the file risk in advance, leaving mainly the property conditions.
How long is a pre-approval letter good for in Nevada?
According to the Consumer Financial Protection Bureau, preapproval letters can carry an expiration date, typically 30 to 60 days. A second clock matters just as much: Fannie Mae's Selling Guide requires that credit documents be no more than four months old on the note date, so credit reports, pay stubs and asset statements all age out. Calendar both dates and ask your lender what it needs to renew.
Does getting pre-approved hurt my credit score?
Barely. According to FICO, one additional inquiry takes less than five points off most scores, inquiries stay on the report up to two years but only affect scores for one, and inquiries in the 30 days before scoring are ignored for mortgages. Newer FICO versions count all mortgage inquiries in a 45-day span as one; older versions use 14 days, and VantageScore uses 14. So cluster every lender pull inside 14 days to fit those windows. The real danger is new debt during escrow.
What are the 2026 loan limits for Clark and Washoe counties?
According to the Federal Housing Finance Agency, the 2026 conforming limit for a one-unit property is $832,750, and both Clark and Washoe counties sit at that baseline. FHA differs: according to HUD's published 2026 limits, Clark County sits at the national floor of $541,287 while Washoe County is $638,250, because HUD's county median inputs were $462,000 and $555,000 respectively. Two-unit FHA limits are $693,050 in Clark and $817,050 in Washoe. Above the conforming line, you are shopping jumbo programs with tighter reserve and ratio requirements.
What is a fully underwritten pre-approval and is it worth it?
It is a pre-approval where an underwriter, not just a loan officer, reviews your complete file before you shop, leaving the property as the main open condition. Timing and cost vary by lender, so ask. It is most useful when you expect competition, because it may let you shorten the financing contingency and close faster. The National Association of REALTORS recorded 7% of contracts terminated in the three months through September 2026, which is the risk a seller is weighing.
How do tipped and self-employed Nevada buyers get pre-approved?
The process is identical; the evidence is not. Self-employed borrowers qualify on net income after write-offs, not gross receipts, and generally need two years of personal and business returns plus a year-to-date profit-and-loss statement. Tipped income has to be declared and documented to count. According to the Bureau of Labor Statistics, leisure and hospitality accounted for a preliminary 302.8 thousand of 1,190.5 thousand Las Vegas metro jobs in September 2026, so this is common here. Talk to a lender before your next return is filed, not after.
How do I confirm my Nevada lender is actually licensed?
Ask for the loan originator's NMLS number and look it up on NMLS Consumer Access, which the Nevada Division of Mortgage Lending points consumers to for mortgage companies and loan originators. The Division works under NRS Chapter 645B, accepts consumer complaints, and can be reached at 702-486-0782. Do it before you send anyone your pay stubs, bank statements and Social Security number.
Which Sources Inform This Pre-Approval Guide?
Nevada market figures are our analysis of Las Vegas REALTORS and Northern Nevada Regional MLS records through our Repliers feed, pulled November 1, 2026. Closings are residential sales in Las Vegas, Henderson, North Las Vegas and Boulder City, and in Reno and Sparks, from October 2025 through September 2026 by closing date, with medians computed from the records. Actives are Reno and Sparks residential listings on November 1, 2026, not under contract. These are not official board statistics. Two sites refused our fetch and stayed unread: USDA Rural Development, so USDA facts rest on federal regulations and notices, and NMLS Consumer Access, so we describe it only as the Nevada Division of Mortgage Lending does. Nevada Real Estate Group is a brokerage, not a mortgage lender; nothing here is a rate quote, a rate prediction, or an offer of credit. Confirm all program specifics with your licensed lender.
- Consumer Financial Protection Bureau — Prequalification vs preapproval letters — definitions and the "not a guaranteed loan offer" standard
- Consumer Financial Protection Bureau — Get a preapproval letter — typical 30 to 60 day expiration; sellers frequently require one
- Consumer Financial Protection Bureau — Figure out how much you want to spend — closing costs of 2% to 5%
- Consumer Financial Protection Bureau — What happens when a mortgage lender checks my credit — the 45-day single-inquiry window
- Consumer Financial Protection Bureau — Regulation Z section 1026.2 — the six items that constitute an application
- Consumer Financial Protection Bureau — What is a Loan Estimate — three-business-day delivery rule
- FICO — Credit checks and inquiries — inquiry impact, 14 vs 45 day windows, 30-day buffer
- VantageScore — Shop around for the best offer — 14-day rolling window
- Federal Housing Finance Agency — 2026 conforming loan limit values — $832,750 baseline, 3.26% index change
- FHFA — 2026 loan limit addendum — two-unit and four-unit limits
- HUD — FHA announces 2026 loan limits — $541,287 floor and $1,249,125 ceiling
- HUD — CY2026 FHA forward mortgage limits file — Clark and Washoe county limits and median inputs
- HUD Handbook 4000.1 — FHA credit, down payment and income rules (revised August 12, 2026)
- HUD Mortgagee Letter 2026-11 — FHA manual debt ratios
- Fannie Mae Selling Guide B3-5.1-01 — Credit scores — no Desktop Underwriter minimum; 620 on manual fixed-rate loans
- Fannie Mae Selling Guide B2-1.3-01 — Purchase transactions — first-time and HomeReady rules above 95% loan-to-value
- VA Lenders Handbook, chapter 4 — no minimum score, residual income, 41% guide
- VA — Loan limits — no limit with full entitlement
- 7 CFR 3555.103 — USDA maximum loan amount — appraised value plus the guarantee fee
- 7 CFR 3555.151 — USDA eligibility — 29/41 ratios and compensating factors
- Fannie Mae Selling Guide B3-6-02 — Debt-to-income ratios — 50% DU maximum
- Fannie Mae Selling Guide B1-1-03 — Allowable age of credit documents — four-month rule
- Fannie Mae Selling Guide B3-4.2-02 — Depository accounts — large deposit definition
- Fannie Mae Selling Guide B3-6-01 — General information on liabilities — recalculating DTI for new debt
- Freddie Mac — The 4 C's of qualifying for a mortgage — capacity, capital, collateral, credit
- Freddie Mac — Primary Mortgage Market Survey — 7.24% 30-year and 6.60% 15-year averages, October 29, 2026
- National Association of REALTORS — REALTORS Confidence Index — September 2026 termination and delay rates
- U.S. Bureau of Labor Statistics — Las Vegas-Henderson-North Las Vegas economic summary — September 2026 preliminary employment by sector
- Nevada Division of Mortgage Lending — licensing role and phone number
- Nevada Division of Mortgage Lending — Search licensees — licensee search and NMLS Consumer Access
- Nevada Division of Mortgage Lending — Submit a complaint
- FOX5: Las Vegas REALTORS September 2026 report — homes without offers and months of supply
- U.S. Department of Veterans Affairs — How to request a COE — Certificate of Eligibility and Web LGY
- Clark County Assessor — Real property — 35% assessment ratio and worked tax example
- Clark County Assessor — Tax abatement — 3% and up-to-8% caps and the effect of a recorded ownership document
- Nevada Housing Division — Get started — state homebuyer assistance through participating lenders
- FTC — Free credit reports — AnnualCreditReport.com