Many Las Vegas servers, dealers and contractors assume a mortgage is out of reach because their pay doesn't look like a salary. That assumption is often wrong, and it is wrong in a specific and fixable way.
Lenders can count tips, 1099 income and self-employment income when it is documented and reasonably likely to continue. What changes is what you have to produce and how far in advance you have to think about it.
Yes. A self-employed or tipped Las Vegas buyer can qualify for a conventional, FHA or VA loan, generally with about two years of documented income. As of November 2026, Fannie Mae and FHA count reported tips and net self-employment income, so write-offs lower what you qualify on: at 7.24%, a $34,000 deduction can cost roughly $135,000 to $160,000 of purchase price. Bank statement loans are the alternative when returns understate income.
- Reported tips count as income; unreported cash can't be used, however consistent it is.
- FHA uses the lesser of the two-year and one-year averages, so a strong year gets diluted.
- Schedule C deductions cut qualifying income, though Fannie Mae adds back depreciation and business use of a home.
- Bank statement loans read deposits rather than returns; price a conventional or FHA loan first.
- Talk to a lender 12 to 24 months before buying, while next April's return can still change.
Why Is Las Vegas Different From Other Mortgage Markets?
Because of what the local economy is made of, not because the loan rules change here.
According to the U.S. Bureau of Labor Statistics, leisure and hospitality was the largest employment sector in the Las Vegas-Henderson-North Las Vegas metro in September 2026, with a preliminary 302.8 thousand of 1,190.5 thousand nonfarm jobs, about 25%. Construction added another preliminary 82.7 thousand. Add rideshare, entertainment and the service businesses around a 24-hour tourism city, and a lot of households earn in ways a pay stub doesn't fully describe.
The practical consequence is that the lender you pick matters. Ask how often a loan officer underwrites tipped and self-employed income before you hand over a file, and how they would treat your own mix of W-2, tip and 1099 income.
There is a Nevada wrinkle that helps. The Nevada Constitution bars an income tax on the wages or personal income of individuals (Article 10, Section 1), so there is no state personal return to reconcile with the federal one. Your federal return, including any Schedule C and W-2 tip income, is the income record. It also means there is nowhere else for unreported income to show up, which is the other half of the same fact.
How Do Lenders Actually Treat Tipped Income?
They count it, with one hard condition and one soft one.
The hard condition: it has to be reported. Tips on your W-2 or your tax return are income a lender can use. Fannie Mae's tip income rule looks for a paystub and two years of W-2s, and if your employer doesn't report the tips, two years of personal returns with IRS Form 4137. Cash tips that never reached either document are, for underwriting purposes, invisible. Under IRS rules, an employee who receives $20 or more in cash tips in a month must report them to the employer.
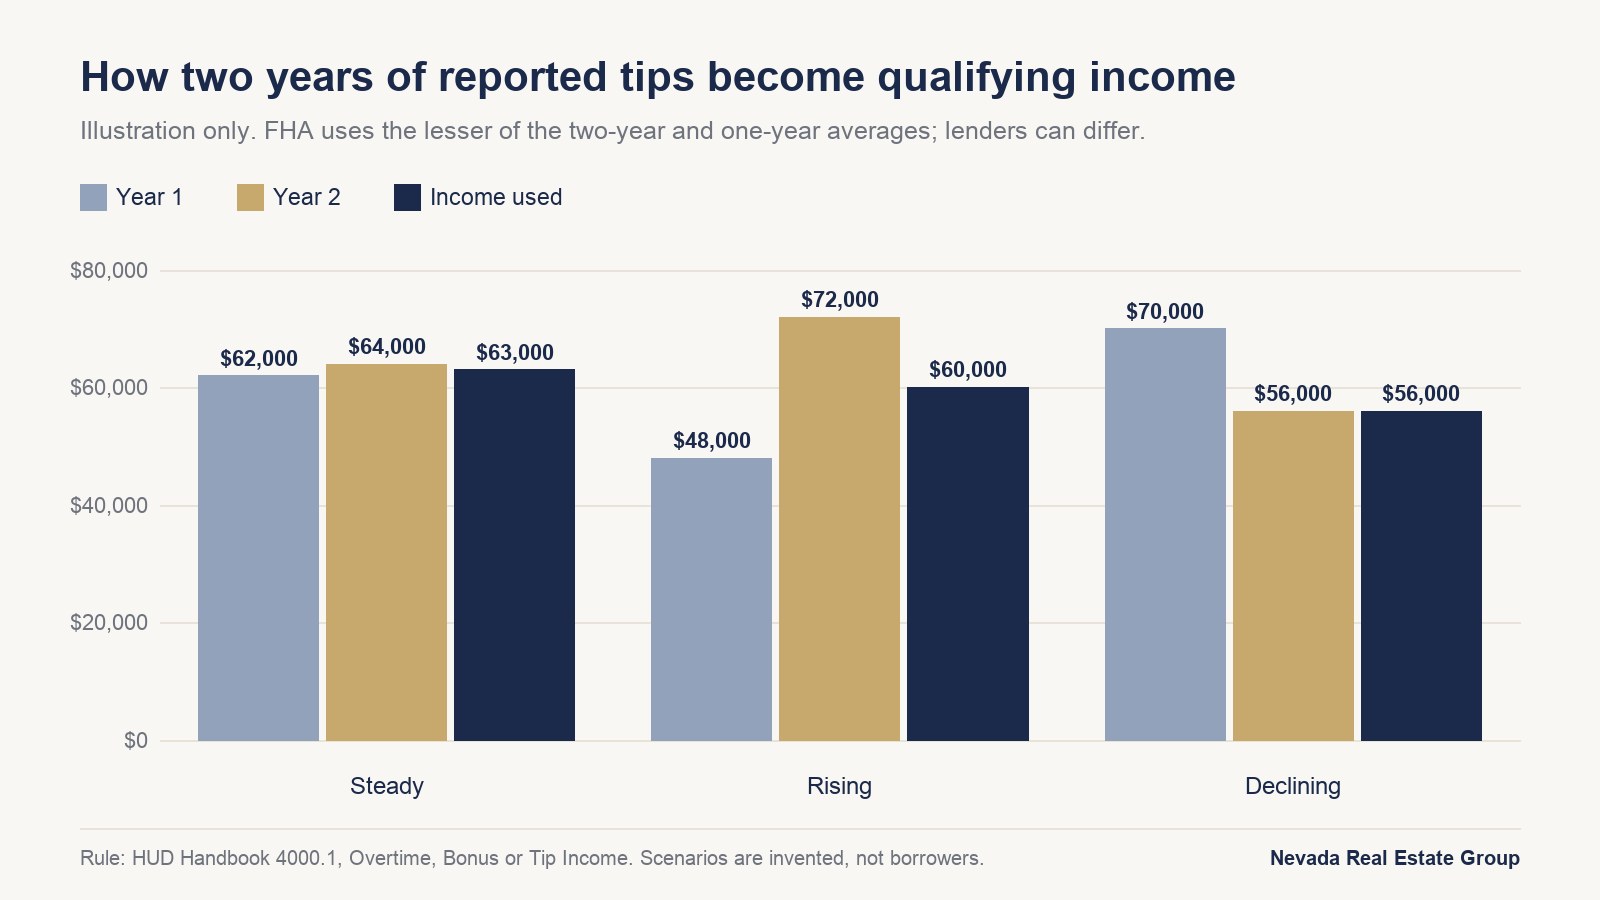
The soft condition: it has to look stable. Fannie Mae recommends a two-year history and accepts at least 12 months when positive factors offset the shorter record. HUD Handbook 4000.1 wants two years, or at least one year of consistent earnings that the lender documents, and uses the lesser of the two-year average and the most recent year's average. So rising tips get averaged down, and a falling year stays in the number.
| Scenario | Year 1 | Year 2 | Lender uses | Why |
|---|---|---|---|---|
| Steady | $62,000 | $64,000 | $63,000 | Two-year average is the lesser figure |
| Rising | $48,000 | $72,000 | $60,000 | Average, not the recent year |
| Declining | $70,000 | $56,000 | $56,000 | Recent year is lower; Fannie Mae also wants the income to have stabilized |
| One strong year only | — | $80,000 | Up to $80,000 | Only if 12 months is documented and accepted; shorter histories generally don't count |
Look at the "rising" row. A bartender who moves from a neighborhood bar to a Strip property and earns more is qualified on $60,000, not $72,000. Nothing is wrong; averaging is just doing what averaging does. It is also why the timing advice later in this guide matters.
What Is the Write-Off Trap for Self-Employed Buyers?
A lender starts from your net income after business deductions, not your gross receipts, so most deductions that lower your tax bill also lower the income an underwriter uses.
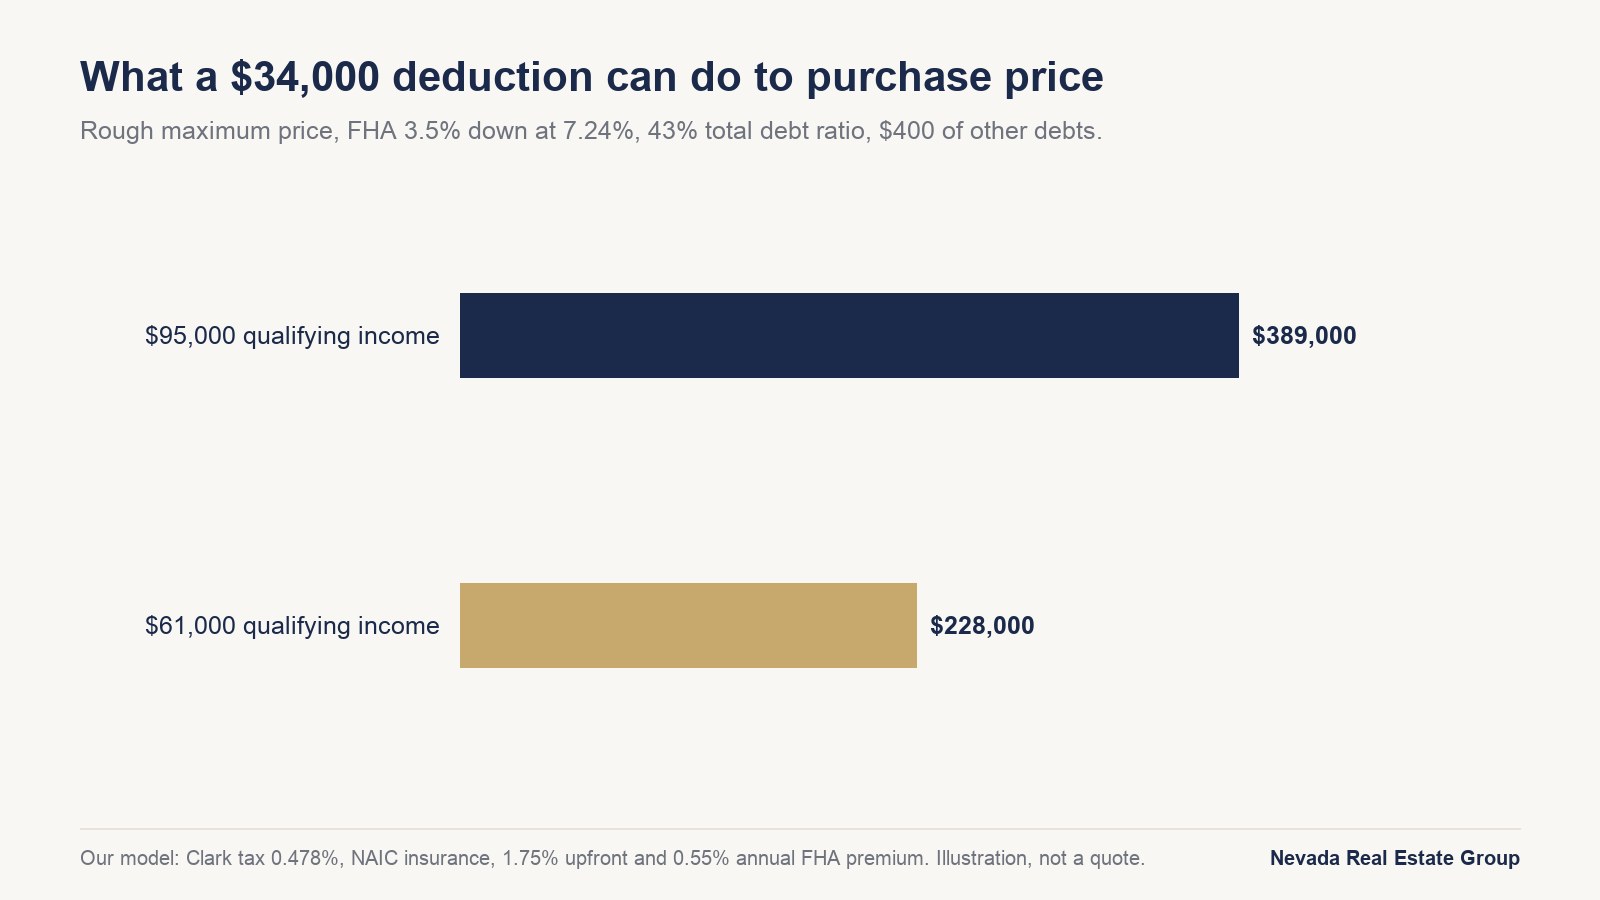
Work an example with invented numbers. A rideshare driver and part-time contractor grosses $95,000. Their accountant, doing the right job, deducts $34,000 in vehicle, phone and equipment expenses. Net profit is $61,000, and the tax saving is real.
But the lender starts from about $61,000, not $95,000. At 7.24%, Freddie Mac's October 29, 2026 average, that $34,000 gap is worth about $135,000 to $160,000 of purchase price in our model: FHA with 3.5% down, $400 of other monthly debts, and total debt ratios of 36% to 43%. At 43%, the price falls from about $389,000 to about $228,000.
Neither professional is wrong. They are optimizing different things. The point is not to stop deducting legitimate expenses; it is to know the trade you are making in the two years before you buy.
Some deductions get added back. Fannie Mae's Schedule C rule adds back depreciation, depletion, business use of a home, amortization and casualty losses, and VA's Lenders Handbook lets depreciation count in effective income. Ask your loan officer to show you each add-back on the income worksheet.
Which Loan Types Work for This Income?
Yes, a self-employed buyer can qualify for a mortgage in Las Vegas, usually on the same conventional, FHA or VA loans a salaried buyer uses. Fannie Mae, FHA and VA generally want about two years of self-employment history, and each allows less in limited cases. These are program rules read November 1, 2026, not an approval, and any lender can add its own.
| Loan | Income proof | Time self-employed | Minimum down |
|---|---|---|---|
| Conventional (Fannie Mae) | Two years of personal returns with all schedules; business returns in some cases | Two years; 12 months on the latest returns with prior same-field income | 3% to 5% |
| FHA | Two years of personal returns; business returns unless exceptions apply; year-to-date profit and loss | Two years; one to two with two prior years in the same line of work | 3.5% |
| VA | Two years of returns, year-to-date profit and loss, and a balance sheet | Two years; less only with related work or training | 0% |
| Bank statement (non-QM) | 12 or 24 months of statements | Set by each lender | Set by each lender; one published program goes to 10% |
The sources are Fannie Mae's self-employed rule, HUD Handbook 4000.1 and VA's Lenders Handbook, chapter 4. Our pre-approval guide has the credit-score and debt-ratio floors for each loan. Try the first three rows first: there is no separate, harder program you have to go find if your returns already show enough income.
Medical professionals comparing specialized financing should separately review physician home-loan options in Nevada with a lender who can confirm program eligibility.
The bottom row exists for the buyer whose tax returns genuinely understate what they earn. According to the Consumer Financial Protection Bureau, lenders must make a good-faith effort to determine that you can repay, and a Qualified Mortgage is assumed to meet that rule. Bank statement loans are usually sold as non-QM products, which is a different category rather than a lesser loan. The mistake is landing there because nobody checked whether a standard loan would have worked.
How Do Bank Statement Loans Work?
The lender reads your deposits instead of your tax returns.
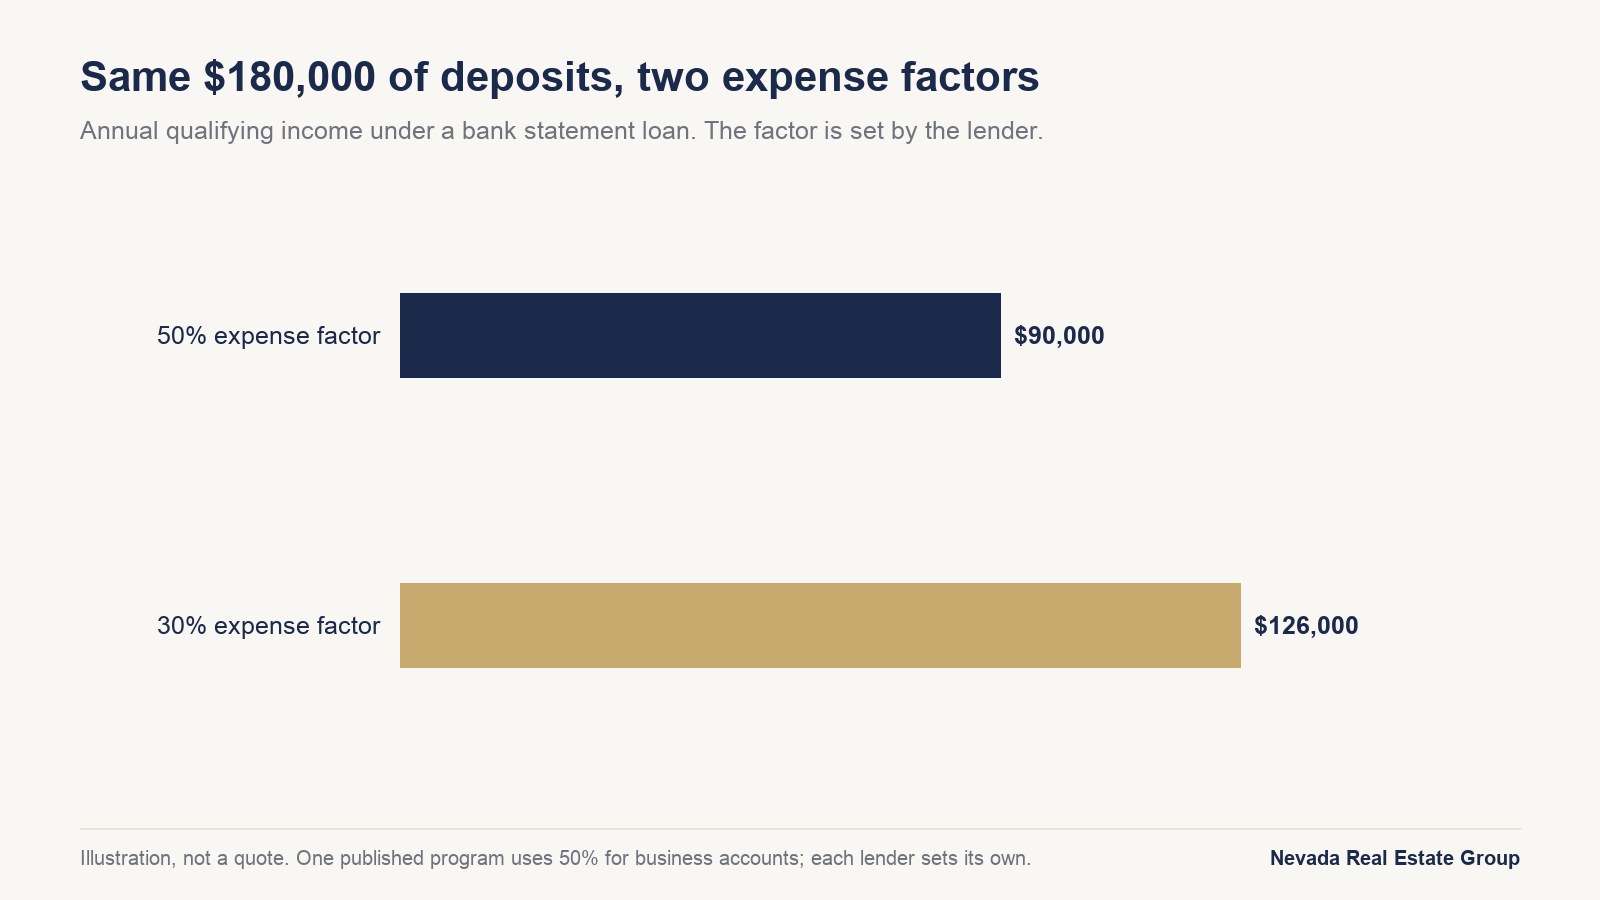
You provide 12 or 24 months of bank statements. The lender totals qualifying deposits, applies an expense factor to business accounts, and treats the result as income. Terms are set by each lender rather than by a government rule. One published program, read November 1, 2026, uses a 50% standard expense ratio for business statements, goes up to 90% combined loan-to-value on a purchase, takes a 620 score or no score, and asks for three months of reserves.
The trade is rate and down payment. These loans generally cost more than a standard loan, but I found no official benchmark for the premium, so get it as a side-by-side quote. As a scale: on a $400,000 loan, a rate one point above 7.24% adds about $276 a month.
When that trade can make sense: a business owner whose returns show $58,000 after legitimate deductions, while $180,000 a year moves through the account. A standard loan qualifies them for a small amount, and a bank statement loan reads the deposits instead.
When it doesn't: a W-2 employee with reported tips who simply assumed they wouldn't qualify. They should price a conventional or FHA loan first.
Two cautions. Ask how the lender treats cash deposits, because a cash-heavy operator with no invoice trail may not get credit for them. And not every lender offers these, so you may have to look beyond the nearest one.
Ask which expense factor the lender applies before you send a single statement. On $180,000 of annual business deposits, the difference between a 50% factor and a 30% factor is $36,000 of qualifying income, $90,000 against $126,000. The published program above says a third-party expense letter or profit and loss statement can lower its factor.
What Credit and Down Payment Do You Actually Need?
Lower than many people assume on both counts, though the floors below are not an approval.
According to HUD Handbook 4000.1, FHA's 96.5% maximum financing is available at credit scores of 580 and above, and scores of 500 to 579 are limited to 90%. Conventional programs go to 3% down for first-time or HomeReady buyers. According to the U.S. Department of Veterans Affairs, a VA purchase loan can have no down payment when the price isn't above the appraised value.
Nevada also runs down payment assistance that can pair with these loans. On a $470,000 FHA purchase, a 5% Home Is Possible award on the $461,487 note is about $23,074, which is more than the $16,450 minimum down payment. That help carries a higher rate than the first-time track, and it is a second mortgage you repay when you sell or refinance.
Credit also moves your rate. On October 29, 2026, the Optimal Blue index for conforming loans above 80% loan-to-value was 7.141% at a 740 score or higher and 7.564% at 680 to 699. Daily readings bounce: that gap of about 0.42 of a point was about 0.19 the day before, so treat it as a rough scale.
Debt ratios matter as much as either one. Fannie Mae allows up to 50% through Desktop Underwriter, and manual approvals start at 36%. A self-employed income figure flows straight into that ratio, so a lower net income tightens it.
What Documents Should You Have Ready?
More than a W-2 buyer, and the gap is the whole difficulty.
Most buyers bring: two months of bank statements for every account, photo ID, and a credit authorization.
Tipped W-2 employees add: two years of W-2s, 30 days of recent pay stubs, and a year-to-date figure showing tips separately from base wage. If your employer doesn't report your tips, add two years of personal returns with Form 4137.
Self-employed and 1099 borrowers add: two years of personal returns with all schedules, business returns if the lender requires them, a year-to-date profit and loss statement, 1099s, business bank statements, and proof the business still exists, such as a CPA letter or a current license lookup.
Everybody should also have: an explanation for any deposit that doesn't match the pattern. Under Fannie Mae's rule, a single deposit above 50% of monthly qualifying income must be sourced if the money goes toward the purchase. Expect to sign IRS Form 4506-C as well, which lets a lender get tax transcripts directly from the IRS. An amended or late-filed return can surface there, and a transcript that hasn't posted yet can slow a file. Our first-time buyer guide covers the general document list in more depth.
How Far Ahead Should You Start?
Twelve to twenty-four months, because the returns a lender reads are the ones you file before you apply.
If you buy in mid-2027, a lender will likely read your 2025 and 2026 tax returns. The 2026 return is the one you file next April. The deductions you take on it and the income you report are being decided now.
That gives you a window to use:
Twenty-four months out. Talk to a loan officer before you talk to your accountant about year-end deductions. Ask what income figure they would use from a draft return.
Twelve months out. Report your tips fully if you have not been. Decide what you can afford by area, since Summerlin and Henderson price differently from other parts of the valley, and knowing the target changes how much income you need to document. Keep business and personal accounts separate. Think hard before starting a new business, because it can restart the two-year clock.
Six months out. Stop opening credit. Leave your money where it is. Get pre-approved for real, with documents, not a rate quote off a website.
Sixty days out. Change nothing. No new car, no job change, no large unexplained deposits.
Extensions cut both ways. The IRS allows up to six more months to file, but Fannie Mae's timing table treats an application from April 15 through October 14 differently from one earlier in the year. In that window it recommends the newest return, and a file without it needs added IRS paperwork. If 2026 is your strongest year, file early, because a return only helps once it exists.
What Can Documented Income Buy in the Las Vegas Valley?
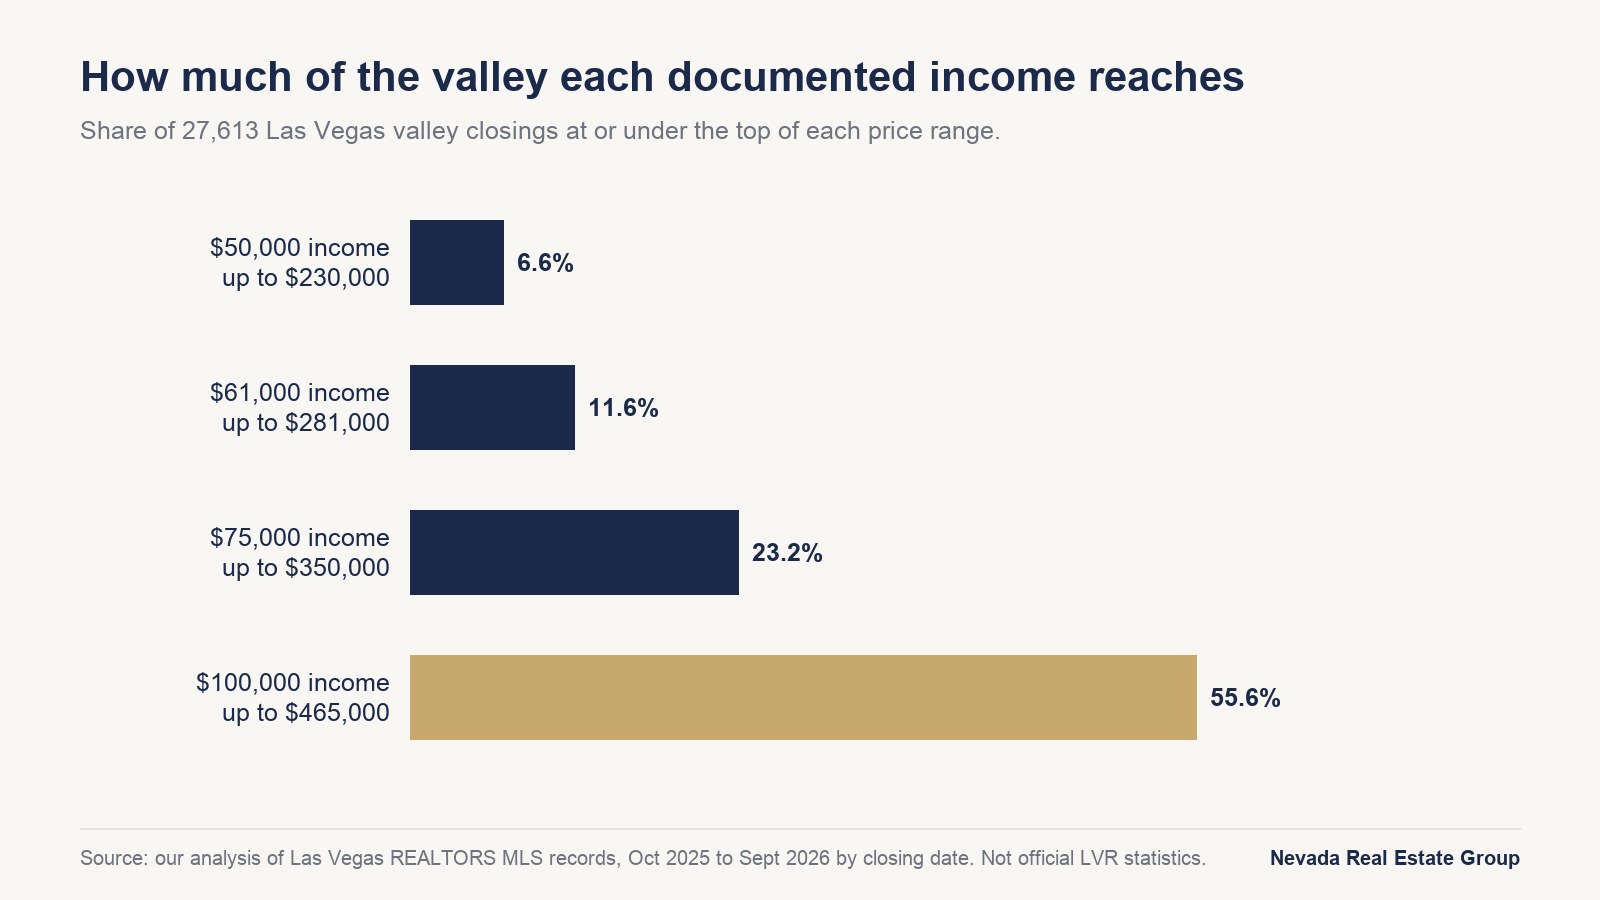
Once you know your qualifying number, you can test it against what actually closed. The table runs four incomes through the same model and compares them with 27,613 residential closings from October 2025 through September 2026, counted by closing date.
| Qualifying income | Rough maximum price | Closings at or under the top of that range | Houses among those closings |
|---|---|---|---|
| $50,000 | $176,000 to $229,000 | 6.6% (at or under $230,000) | 4% |
| $61,000 | $228,000 to $281,000 | 11.6% (at or under $281,000) | 9% |
| $75,000 | $295,000 to $348,000 | 23.2% (at or under $350,000) | 30% |
| $100,000 | $412,000 to $465,000 | 55.6% (at or under $465,000) | 63% |
The price range is an illustration: FHA with 3.5% down at 7.24%, a 43% total debt ratio, $400 of other monthly debts at the low end and none at the high end, the financed 1.75% upfront premium, a 0.55% annual premium, Clark County's 0.478% effective tax rate from Census data, and NAIC average insurance for the price band. HOA dues aren't included, and they matter here because most closings at the lower prices were condos and townhomes.
The top row is not failure. Below about $280,000, most of what closed was attached housing rather than houses. Of the 3,201 closings at or under $280,000, 2,712 had Las Vegas mailing addresses, and the most common ZIP codes were 89103, 89122, 89108, 89128 and 89121.
Documented income moves the range quickly. Going from $61,000 to $75,000 of qualifying income adds about $67,000 of price at the low end of this model. Because lenders average two years, it takes more than one good year to get all of it.
Set that against a market where the 12-month median closing was $445,000 across all residential sales, $485,000 for houses and $290,000 for condos and townhomes. Las Vegas REALTORS reported a $470,000 existing single-family median for September 2026, according to FOX5.
A tipped or self-employed buyer qualifying on $61,000 is looking at roughly $228,000 to $281,000 in this model. That range is mostly condos and townhomes: of the 3,201 closings at or under $280,000, only about 9% were houses.
Now take the same buyer who reports $95,000 instead of $61,000 for one tax year. Averaged over two years, that is $78,000, and the range becomes roughly $309,000 to $361,000. Of the 3,197 closings between $280,000 and $350,000, 51% were houses and 43% were condos or townhomes, with a median build year of 1997. Nothing about their actual earnings has to change if the money was already there. What changed is the number a lender is permitted to read.
Our pages on Spring Valley, East Las Vegas and Centennial Hills break down local detail, and our Las Vegas deals guide covers lower-priced inventory once you know your number.
What Actually Gets These Loans Denied?
These are the file problems that can stop a tipped or self-employed buyer.
Unreported income. What isn't on a W-2 or a return doesn't exist to an underwriter, and it is the hardest one to fix quickly.
Declining income. FHA requires a manual review when self-employment income falls more than 20% over the analysis period, and VA requires the lender to analyze why it fell. For tips, Fannie Mae wants a decline to have stabilized before counting the income.
A brand-new business. Under two years usually means no usable self-employment income, with narrow exceptions for someone who stayed in the same field. Fannie Mae needs at least 12 months on the returns, and VA says less than one year can rarely qualify.
Commingled accounts. Personal and business money in one account makes deposits harder to analyze on a bank statement loan.
Undisclosed debt. According to Fannie Mae's liabilities rule, debts discovered after the underwriting decision and up to closing force a new debt-to-income calculation. If you personally owe or guarantee a business loan or vehicle, tell the lender early.
Changing anything mid-process. A new car in week three is the classic self-inflicted problem.
That is why it pays to talk to a lender long before you are shopping. For a tipped or self-employed buyer, a pre-approval is the last step of a preparation that started a year earlier.
Frequently Asked Questions
Can I get a mortgage in Las Vegas with tipped income?
Yes. Reported tips can count as qualifying income on conventional and FHA loans. Lenders generally want a two-year history and will average it, and shorter histories of at least 12 months can work in limited cases. The condition is that the tips are reported on a W-2 or a tax return. Unreported cash cannot be used no matter how consistent it is.
Do lenders count all of my self-employment income?
They start from net income after business deductions, not gross receipts. Fannie Mae adds back items such as depreciation, depletion and business use of a home. This is why a self-employed borrower's qualifying income is often far below what the business takes in, and why the conversation should happen before the tax return is filed rather than after.
What is a bank statement loan and should I use one?
It qualifies you on 12 or 24 months of bank deposits instead of tax returns, applying an expense factor to arrive at income. Terms vary by lender, and it generally costs more than a standard loan. Use it when your returns genuinely understate your income. Price a conventional or FHA loan first, because that premium is real money.
How long do I need to be self-employed to buy in Las Vegas?
Generally two years. Fannie Mae and FHA can accept less when you have at least a year of self-employment and prior work in the same field, and FHA wants two prior years in that line of work. VA says less than one year can rarely qualify.
Will my accountant's deductions stop me buying a house?
They can reduce what you qualify for substantially. At 7.24% in our model, a $34,000 deduction can cost roughly $135,000 to $160,000 of purchase price. Nobody is doing anything wrong; your accountant is minimizing tax and your lender is reading net income. The fix is talking to both before you file, not after.
How much down payment do I need as a self-employed buyer in Las Vegas?
On conventional or FHA, the same as anyone: 3% to 5% or 3.5%, and zero on VA for eligible borrowers. Bank statement programs are set by each lender; one published program goes to 10% down. Nevada down payment assistance can pair with standard loans, but it is usually a second mortgage you repay.
Should I report all my tips if I want to buy a home?
Reported tips are the only tips a lender can count, so under-reporting directly reduces what you can borrow. Beyond that, tip reporting is a tax obligation and a question for your accountant rather than your agent.
Which Sources Inform This Las Vegas Mortgage Guide?
This guide describes how conventional, FHA, VA and non-QM lenders treat tipped and self-employed income as of November 1, 2026. Underwriting standards vary by lender and change. The income scenarios are invented examples, not descriptions of borrowers. Price ranges are our own model at Freddie Mac's 7.24% average of October 29, 2026, not offers. Closing figures are our analysis of Las Vegas REALTORS MLS records through Repliers, pulled November 1, 2026, covering Las Vegas, Henderson, North Las Vegas and Boulder City by closing date, and they are not official LVR statistics. No client file or denial data was used. Nothing here is tax advice; discuss deductions with a licensed CPA.
- U.S. Bureau of Labor Statistics: Las Vegas metro employment by sector, September 2026 preliminary.
- Nevada Constitution, Article 10: no personal income tax.
- Fannie Mae B3-3.3-02: tip income.
- Fannie Mae B3-3.5-01: self-employed borrowers.
- Fannie Mae B3-3.6-03: Schedule C add-backs.
- Fannie Mae B1-1-03: age of tax returns.
- Fannie Mae B3-4.2-02: large deposits.
- Fannie Mae B3-6-01: liabilities found before closing.
- Fannie Mae B2-1.3-01: 3% down rules.
- HUD Handbook 4000.1: FHA tip income, self-employment and credit rules (revised August 12, 2026).
- VA Lenders Handbook, chapter 4: VA self-employment rules.
- U.S. Department of Veterans Affairs, purchase loans: no down payment condition.
- Consumer Financial Protection Bureau, Qualified Mortgage: ability to repay.
- IRS Tax Topic 761: reporting tips.
- IRS Tax Topic 304: extensions.
- AD Mortgage bank statement program: one lender's published terms, read November 1, 2026.
- Freddie Mac Primary Mortgage Market Survey: 7.24% on October 29, 2026.
- Optimal Blue indexes on FRED: rates by credit tier, October 29, 2026.
- FOX5 on Las Vegas REALTORS' September 2026 report: $470,000 single-family median.
Rates, programs and underwriting standards change continuously; contact Nevada Real Estate Group at (702) 637-1759 and speak with a licensed lender before making decisions. This is not tax, legal or lending advice. Information is believed accurate but not guaranteed. Nevada Real Estate Group | LPT Realty | License S.181401 | 8945 W Russell Rd, Suite 170, Las Vegas, NV 89148.
Been told you cannot qualify? Nevada Real Estate Group is Nevada's #1 real estate team with 150-plus agents, $4.85B-plus in closed sales volume, and 9,097-plus five-star reviews. Bring your numbers and we'll help you organize the questions for a lender.
Call or text (702) 637-1759 | Email info@nevadagroup.com | Search Las Vegas homes | Talk to an agent