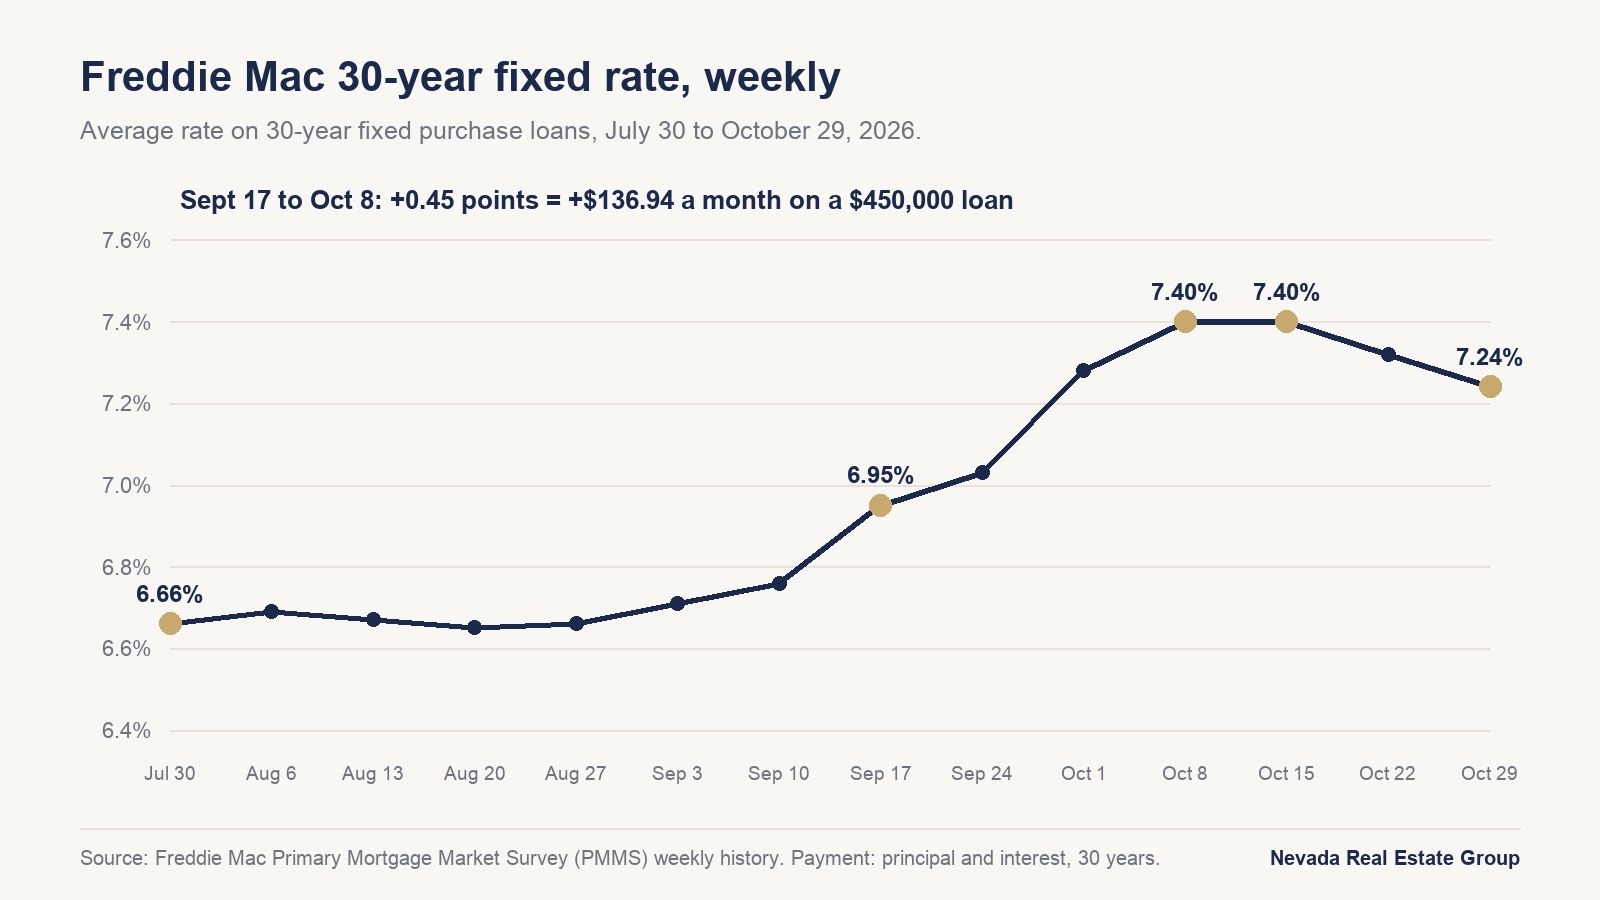
Every financed buyer in Nevada faces the same problem this fall: the monthly payment is the hardest number in the deal. According to Freddie Mac's Primary Mortgage Market Survey, the national average for a 30-year fixed mortgage was 7.24% in the October 29, 2026 release, down from 7.40% on October 8 and 15 and up from 6.95% on September 17; the 15-year average was 6.60%. Read that number for what it is. Freddie Mac describes the survey as rates on conventional, conforming purchase loans for owner-occupied single-family homes, borrowers with good-to-excellent credit and 20% down, published each Thursday. It is a published average on a date, not a quote, and Nevada Real Estate Group is a brokerage, not a lender. Your actual rate comes from your loan officer, in writing, on the day you lock it.
Every buyer also hears four tools pitched as solutions — buydown, points, lock, float-down — usually without the math. They do very different jobs. A temporary buydown gives you a year or two of relief that someone else usually pays for. Permanent points buy a lower rate for the life of the loan but take years to break even. A rate lock does not lower your rate at all; it protects the one you have from rising before closing. And the buydown a seller agrees to is capped by rules your lender enforces, so a deal can be written that the lender will not fund in full.
This guide prices all four on a $450,000, 30-year loan at a 7.24% note rate, Freddie Mac's October 29 average, used as an illustration throughout. That loan size sits in the middle of the Southern Nevada market: according to Las Vegas REALTORS, as reported by FOX5 on October 6, 2026, the median existing single-family home sold through its MLS in September 2026 was $470,000, the same as September 2025, and 5% down on that is $446,500 financed. The math scales the same way in Henderson or Reno, and a Northern Nevada resale is worked below on Washoe County's September median. If you are negotiating a builder's 2-1 offer on new construction, our builder buydown deep-dive covers that negotiation; this guide is the full rate-strategy picture.
A temporary buydown subsidizes your payments for up to three years without changing the note rate, discount points buy a lower rate for the life of the loan, and a rate lock only holds a quoted rate. On a $450,000, 30-year loan at 7.24%, Freddie Mac's October 29, 2026 average, a 2-1 buydown costs about $10,600 and a full percentage point off the rate saves about $299 monthly. Contribution limits decide what a seller can fund.
- A 2-1 buydown on a $450,000 loan at 7.24% is worth about $10,600 over two years.
- Seller and builder buydowns count as interested-party contributions, capped at 3% to 9% on conventional primary-home loans.
- Freddie Mac's 30-year average rose from 6.95% on September 17 to 7.40%, then eased to 7.24%.
- With 5% down on Washoe's $595,000 September median, a seller-paid 2-1 uses about $13,300 of the $17,850 cap.
- Conventional, FHA, VA and USDA loans qualify fixed-rate borrowers at the full note-rate payment.
- Under an assumed 0.25% cut, one point overtakes $4,230 more down in month 67.
| Tool | What it changes | How long it lasts | Who usually pays | Cost here |
|---|---|---|---|---|
| Temporary 2-1 buydown | Your payment, not the note rate | Two years | Seller or builder | About $10,600 |
| Discount points | The note rate | Life of the loan | Buyer, or a seller within limits | $4,500 per point |
| Rate lock | Nothing; it holds the quoted rate | Typically 30, 45 or 60 days | Varies by lender; ask | Set by the lender |
| Float-down | Lets a locked rate drop | Until the lender's deadline | Varies by lender | Set by the lender |
What Is a Rate Buydown, and How Does a 2-1 Buydown Actually Work?
A buydown uses upfront money either to subsidize early payments or to purchase a permanently lower interest rate. These are different arrangements. A temporary buydown funds an account that supplements your payments while your actual note rate stays the same. A 2-1 buydown calculates your payment portion using a rate 2 percentage points below the note rate in year one and 1 point below in year two; a 3-2-1 goes three years deep (3, 2, 1); a 1-0 covers just the first year.
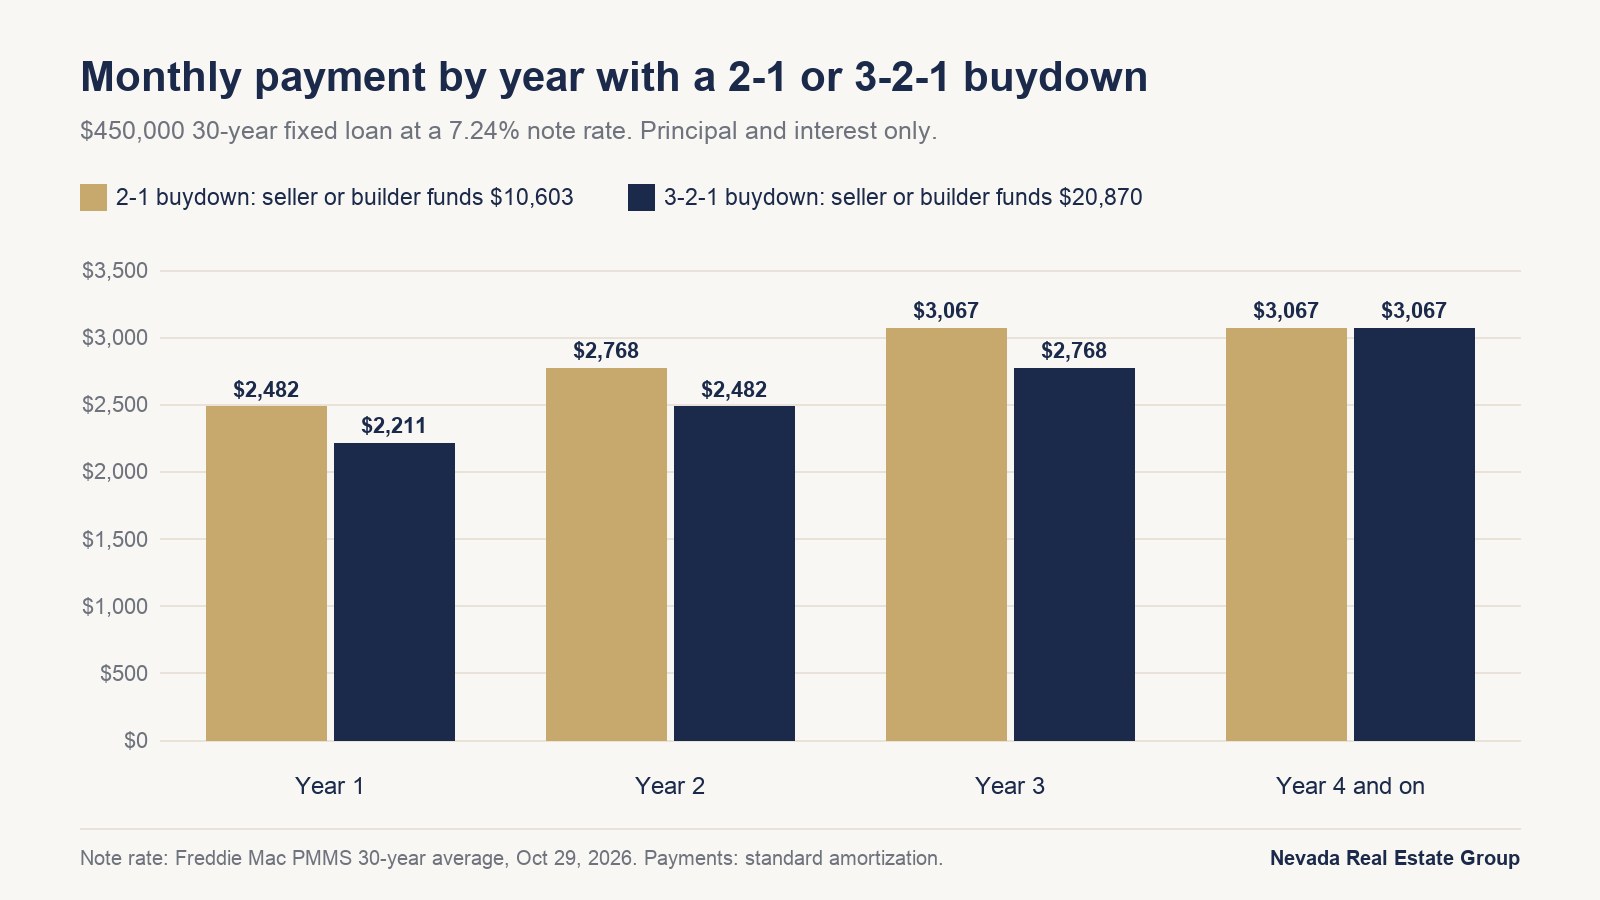
Here is the math on a $450,000 30-year loan at a 7.24% note rate, Freddie Mac's October 29, 2026 average, used as an illustration rather than a quote. At 7.24%, principal and interest run $3,067 a month. With a 2-1 buydown, year one is paid at 5.24%, $2,482, saving you $585 every month. Year two is paid at 6.24%, $2,768, saving $299 a month. From year three you pay the full $3,067. Total subsidy: about $10,600 ($10,603), which is what the buydown costs whoever funds it, because the money sits in escrow and draws down monthly. A 3-2-1 adds a 4.24% first year ($2,211, saving $856 a month) and costs about $20,900 over three years.
Now the part the pitch decks leave out. According to Freddie Mac research published July 31, 2023, temporary buydowns made up 2.8% of Freddie Mac-funded loans in June 2023, down from a peak of 7.6% in December 2022, and just 12 lenders accounted for 80% of temporary buydowns between June 2022 and June 2023. The same study found that borrowers who took a temporary buydown received rates averaging roughly 15 basis points higher. The subsidy is not always free money stacked on an unchanged rate; sometimes a slice of it is priced back into the loan. Treat those percentages as a 2023 snapshot rather than today's market. Freddie Mac noted these products were especially popular in new-home financing, where a headline buydown is easy to advertise and hard to price-check, so ask for the rate with and without it.
Who Actually Pays for a Temporary Buydown?
Here is the part that changes the whole calculation: you should almost never pay for a temporary buydown yourself. Temporary buydowns are usually structured as concessions: the home seller, the builder, or occasionally the lender funds the escrow account as part of the deal. Some programs let a buyer fund one, and VA's handbook describes that as a financial management tool, but it's the buyer's own cash either way.
Fannie Mae's Selling Guide topic B2-1.4-04, dated August 7, 2024, covers buydown funds from an interested party and from the lender, and when an interested party provides them, Fannie Mae's contribution limits apply. The same topic sets the guardrails on what any lender can offer you: the rate reduction cannot exceed 3%, the rate cannot rise more than 1% per year, and the buydown period cannot run longer than three years. Temporary buydowns are eligible on principal residences and second homes and ineligible on investment properties and cash-out refinances. Freddie Mac's rules for loans it buys match on the essentials: according to its temporary subsidy buydown page, the initial rate may not sit more than three percentage points below the note rate, the plan may not run past three years, and fixed-rate borrowers must be qualified at the note rate.
The qualification rule is the one buyers most often get backwards: Fannie Mae requires the lender to qualify you on the note rate, without consideration of the bought-down rate. A buydown buys breathing room; it never buys a bigger approval. And if the loan is paid off early, Fannie Mae says undistributed buydown funds are credited toward the payoff or returned to the borrower or the lender, as the buydown agreement specifies. Who gets that money back is a term in a document, so read it.
That structure makes buydowns a negotiation tool, not a product you shop for. A seller who won't cut the price may still agree to fund a buydown of a similar size, because the contract price stays intact while you get the payment relief. On new construction, whether the builder is genuinely paying or folding it into the price is its own analysis, covered clause by clause in our 2-1 builder buydown breakdown. On a resale, ask for the buydown as a concession the same way you would ask for closing costs.
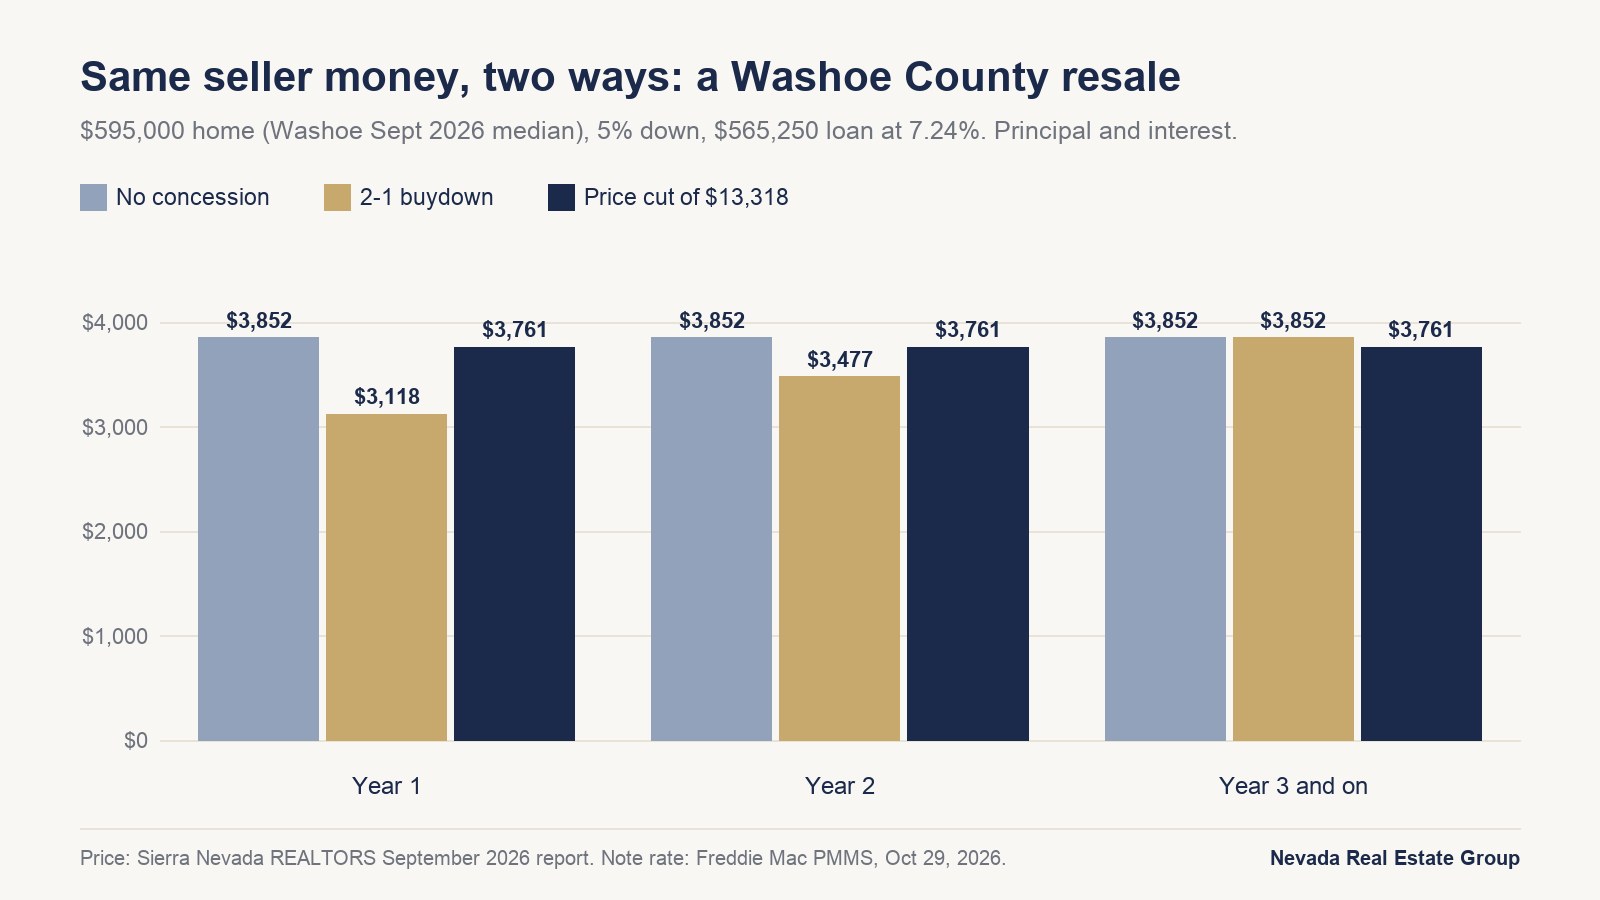
Here is how that pencils on a Northern Nevada resale. According to Sierra Nevada REALTORS' September 2026 Market Review, built on Northern Nevada Regional MLS data updated October 4, 2026, Washoe County's median sale across all residential property types was $595,000 on 487 closed sales, up 9.7% from September 2025. With 5% down that is a $565,250 loan, and at 7.24% principal and interest run $3,852 a month. A seller-paid 2-1 drops year one to $3,118 (5.24%, saving $734 a month) and year two to $3,477 (6.24%, saving $376), for an escrow deposit of about $13,300. At 95% LTV the conventional ceiling is 3% of the price, $17,850, so the seller can fund the buydown and still cover about $4,500 of your closing costs before you reach the cap. In Carson Valley the numbers scale up: the same report put Douglas County, which takes in Minden and Gardnerville along with the Lake Tahoe shore, at a $660,000 median on 79 sales, 12% below August, where a 2-1 on a 5%-down loan runs about $14,800 against a $19,800 ceiling. Our Carson Valley market guide covers that market in depth.
Will Your Lender Allow the Buydown You Negotiated?
Here is the constraint that can undo a deal at underwriting: when a seller or builder funds your buydown, that money is an interested-party contribution, and every loan program caps how much an interested party may contribute. The cap moves with your loan type, your occupancy, and, on conventional loans, your down payment. It is entirely possible to negotiate a buydown your lender will then refuse to fund in full.
According to Fannie Mae's Selling Guide topic B3-4.1-02, dated May 7, 2025, the conventional ceiling on a principal residence or second home is 3% when the LTV/CLTV is above 90%, 6% from 75.01% to 90%, and 9% at 75% or less, measured against the lower of the sales price or appraised value; investment property is capped at 2% at any ratio. Fannie Mae states that the cost of an interested-party-funded buydown must be included in that calculation, and that financing concessions over the limit are treated as sales concessions and deducted from the sales price, with the maximum LTV/CLTV recalculated on the reduced figure. If your loan is going to Freddie Mac instead, its Guide Section 5501.6 sets the same 3%, 6%, 9% and 2% tiers by LTV/TLTV ratio; ask your loan officer which agency's rules apply to your file.
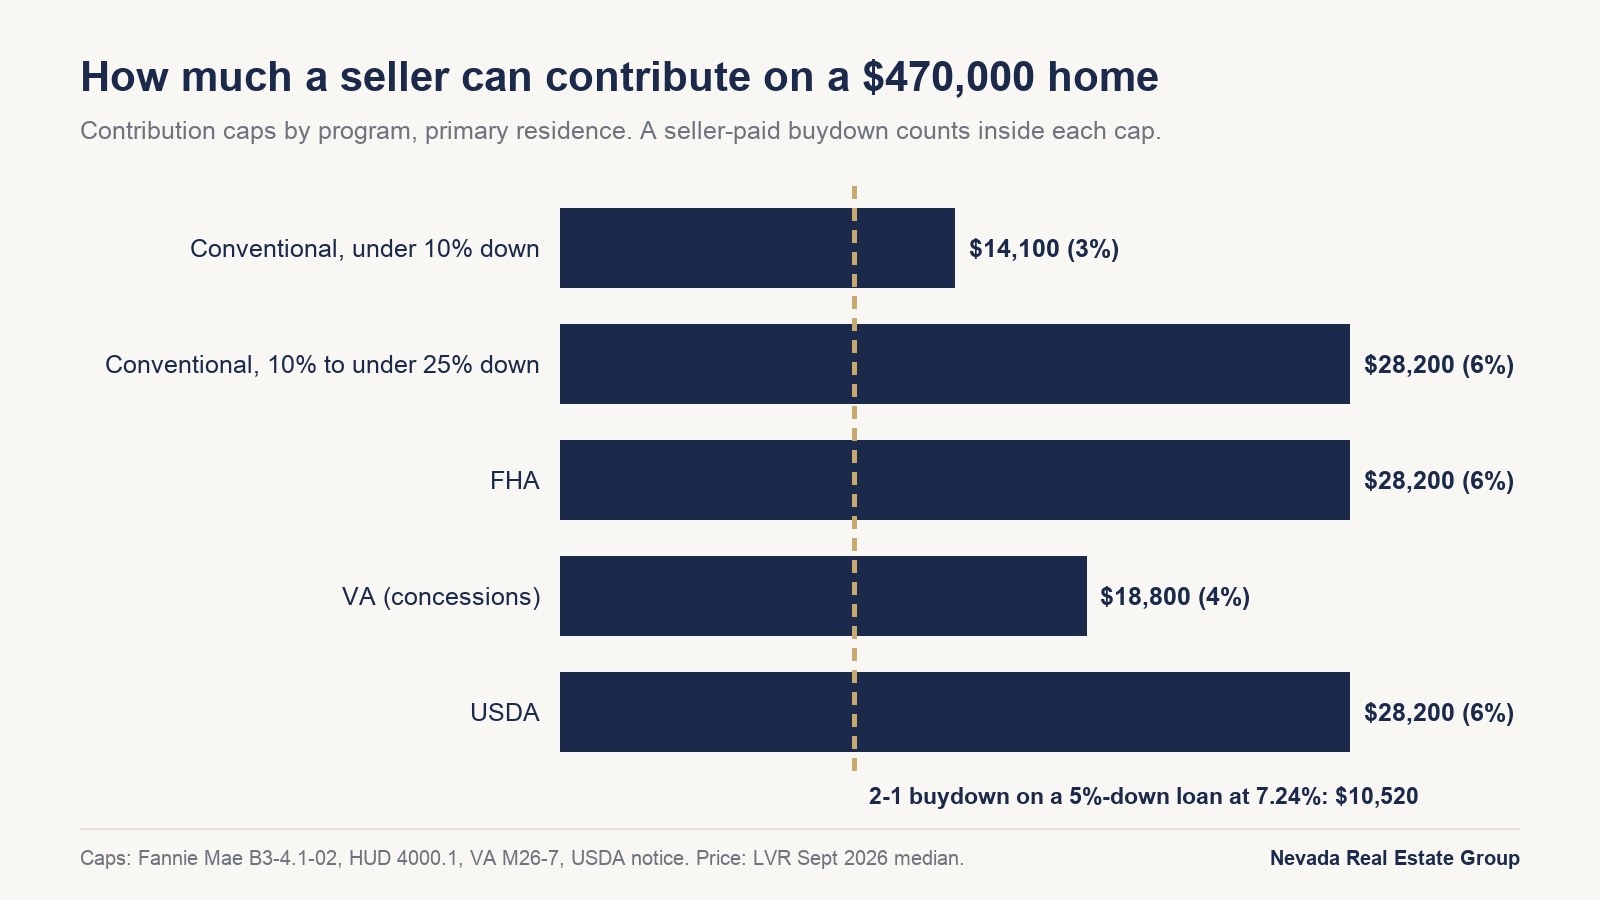
Work that through on a Las Vegas resale at the September median. On a $470,000 purchase with 5% down, the LTV is 95%, so the ceiling is 3%, $14,100 in total interested-party money. A 2-1 buydown on the $446,500 loan at 7.24% costs about $10,500; add $8,000 toward closing costs and you are at $18,500, about $4,400 over. Put 10% down instead and the ceiling jumps to 6%, $28,200; the 2-1 on the smaller $423,000 loan costs about $10,000, and the same $8,000 credit clears with room to spare. Down payment is not just an equity decision; it sets the size of the help the seller is allowed to give you.
Government programs draw the line differently. According to HUD's Single Family Housing Policy Handbook 4000.1, FHA interested parties may contribute up to 6% of the sales price, and that 6% expressly includes payments for permanent and temporary interest rate buydowns and payment of the upfront mortgage insurance premium. According to VA's Lender's Handbook (VA Pamphlet 26-7, Chapter 8, Topic 5), seller concessions above 4% of the established reasonable value are excessive, and "provision of escrowed funds to provide temporary interest rate buydowns" is on its list of concessions. USDA's April 20, 2026 proposed rule restates a 6% interested-party limit on its guaranteed loans, measured against the sales price.
| Loan type | Cap | Measured against | How a temporary buydown is treated |
|---|---|---|---|
| Conventional (Fannie Mae), primary or second home, LTV/CLTV above 90% | 3% | Lower of sales price or appraised value | Counts in full; at most 3 points below the note rate, 3 years |
| Conventional (Fannie Mae), primary or second home, 75.01% to 90% | 6% | Lower of sales price or appraised value | Counts in full |
| Conventional (Fannie Mae), primary or second home, 75% or less | 9% | Lower of sales price or appraised value | Counts in full |
| Conventional (Fannie Mae), investment property | 2% | Lower of sales price or appraised value | Temporary buydowns are ineligible |
| FHA | 6% | Sales price | Counts; not allowed on refinances or ARMs |
| VA | 4% | Established reasonable value | Seller or builder escrow counts; normal points and closing costs do not |
| USDA guaranteed | 6% | Sales price | Seller money counts; at most 2 points below the note rate, no borrower funds |
Price the entire concession package before the offer goes out. Ask the lender which charges count toward your program's limit, which customary seller-paid costs are excluded, and whether the proposed credit exceeds your eligible costs. A temporary buydown shares its ceiling with other contributions counted under that program, not automatically every dollar a seller pays. Fannie Mae excludes qualifying customary seller charges; VA separates ordinary closing costs from concessions. Our Las Vegas seller concessions guide explains the questions to put in writing. Prioritize the combination that fits your cash reserves and total cost, rather than automatically funding a buydown first.
Is a Buydown Better Than a Price Reduction?
This is the negotiation question, and the math has a clear short-term answer. Take the same $10,600 of seller money on the $450,000 loan at 7.24% and apply it two ways, keeping your cash down payment the same:
| Metric | 2-1 buydown (about $10,600) | $10,600 price cut |
|---|---|---|
| Year-one monthly savings | $585 | about $72 |
| Year-two monthly savings | $299 | about $72 |
| Savings after year two | $0 | about $72/month for the life of the loan |
| Lowers loan balance? | No | Yes, to about $439,400 |
| Benefit to compare | Temporary payment relief; full payment must remain affordable | Immediate principal reduction and lower payments throughout the loan |
The buydown delivers about eight times the monthly relief in year one, $585 versus about $72, because it concentrates the subsidy into two years. That payment comparison alone does not establish the better financial outcome. The price cut reduces principal immediately; include the remaining balance at sale or refinance, cash required, fees and any unused subsidy when comparing outcomes. The Washoe illustration similarly compares about $91 monthly from a price reduction with $734 of first-year subsidy. Those are payment differences, not a calculation of total wealth. Test both choices over your shortest, likely and longest holding periods, including a scenario in which refinancing never becomes attractive.
One caveat the table cannot show. A price cut lowers the contract price, which lowers the number the appraiser has to support and the number your LTV is calculated from. A buydown does neither, and it has to fit inside the contribution ceiling from the previous section. Market context decides which ask lands. According to Las Vegas REALTORS' September 2026 figures, as reported by FOX5, 7,995 single-family homes were listed without an offer at the end of the month, up 6.6% from a year earlier, against about a five-month supply, up from roughly four months a year earlier, and 2,169 existing homes, condos and townhomes sold. That is a market with enough standing inventory for buyers to negotiate, and a seller who would rather protect the headline price may still say yes to the buydown.
When Do Permanent Points Beat a Temporary Buydown?
A temporary buydown and discount points differ in what they change and how long it lasts. A temporary buydown uses escrowed money, usually the seller's or builder's, to lower your payments for up to three years while the note rate stays the same. Discount points are prepaid interest that lower the note rate itself for the life of the loan. You pay 1% of the loan amount per point, $4,500 on our loan, and the lender cuts your rate. There is no fixed exchange rate. According to the Consumer Financial Protection Bureau, the amount your rate drops "depends on the specific lender, the kind of loan, and the overall mortgage market," and "sometimes you receive a relatively large reduction in your interest rate for each point paid. Other times, the reduction in interest rate for each point paid could be smaller." The quarter-point-per-point figure below is an illustrative pricing assumption, not a rule or anyone's quote.
Under that assumption, dropping from 7.24% to 6.99% saves about $76 a month, and $4,500 ÷ $76 is about a 59-month breakeven. In this simplified example, holding the loan beyond about five years recovers the upfront points cost before considering opportunity cost or taxes. Compare the actual quotes rather than treating five years as a universal rule. Refinance or sell in year three and you spent $4,500 for about $2,730 of benefit. Two-point pricing may produce a different rate reduction and breakeven; so the right question for your loan officer is "show me zero, one and two points priced on the same day." Our mortgage calculator will run the payment side on your own numbers.
| Points paid | Upfront cost | Approx. rate | Monthly P&I | Breakeven |
|---|---|---|---|---|
| 0 | $0 | 7.24% | $3,067 | None |
| 1 | $4,500 | 6.99% | $2,991 | about 59 months |
| 2 | $9,000 | 6.74% | $2,916 | about 60 months |
The decision depends on actual loan pricing, reserves and holding period. The CFPB recommends comparing costs over the shortest, longest and most likely time you expect to keep the loan. Ask for a no-refinance scenario as well as any refinance scenario. A future refinance requires acceptable rates, equity, credit, income and new closing costs; it is not a dependable solution to an unaffordable full payment. A seller-funded subsidy can preserve early cash flow, while a price reduction or points can offer different long-term benefits. None is the default choice for every Nevada buyer.
And a tax wrinkle, stated carefully. According to IRS Publication 936 (2025 edition), you can fully deduct points in the year paid only if you meet all nine tests the publication lists, among them that the loan is secured by your main home, that paying points is an established business practice in the area, that the points were not more than generally charged there, that they were figured as a percentage of the principal, and that they are clearly shown on the settlement statement. Otherwise they are generally deducted ratably over the life of the loan. Ask your tax preparer before a deduction tilts a marginal point decision.
Should You Pay Discount Points or Put More Money Down?
Extra cash at closing can buy points or shrink the loan, and the two pay you back differently. Points are prepaid interest that lower the rate. A bigger down payment lowers the balance, and that money comes back as a lower payoff when you sell or refinance. So the fair test compares points with the down payment, not with doing nothing.
My worked example uses the $470,000 Las Vegas REALTORS September 2026 single-family median from earlier in this guide, with 10% down: $47,000 and a $423,000 loan, where one point is $4,230. Both options are priced at 7.24%, Freddie Mac's October 29, 2026 average, with the same 0.25%-per-point assumption as the table above. I hold the rate equal on both loans to isolate the trade, so ask whether a larger down payment changes your own quote. Mortgage insurance, which both loans carry above 80% loan-to-value, is left out.
| Metric | Pay one point | Put $4,230 more down |
|---|---|---|
| Cash for down payment and points | $51,230 | $51,230 |
| Loan amount | $423,000 | $418,770 |
| Note rate | 6.99% (assumed) | 7.24% |
| Monthly principal and interest | $2,811 | $2,854 |
| Saved vs. $2,883 with neither | $71 a month | $29 a month |
| Balance owed after five years | $398,134 | $395,189 |
| Break-even | About 59 months vs. no points; month 67 vs. the larger down payment | None; the $4,230 stays in the home as equity |
Per dollar, the point cuts the payment more, $71 against $29 a month. But the $4,230 spent on points is gone, while the $4,230 put down is still yours as a balance about $2,945 lower after five years. Counting payments made plus balance owed, the points loan is still about $394 behind at month 60 and pulls ahead only in month 67, later than its 59-month break-even against no points. That ignores taxes and what the cash could earn elsewhere.
| Cut per point | Rate | Monthly principal and interest | Saved vs. no points | Break-even vs. no points | Points overtake the larger down payment |
|---|---|---|---|---|---|
| 0.125% | 7.115% | $2,847 | $36 | About 118 months | Month 199 |
| 0.25% | 6.99% | $2,811 | $71 | About 59 months | Month 67 |
| 0.375% | 6.865% | $2,776 | $107 | About 40 months | Month 40 |
The extra $4,230 down saves $29 a month whatever the point pricing, so your lender's quote decides which row you are in.
Mortgage insurance can flip the answer. Fannie Mae's Selling Guide requires primary mortgage insurance on a conventional first mortgage with an LTV ratio greater than 80%, and Freddie Mac says PMI varies but runs approximately $30 to $70 a month per $100,000 borrowed. With 19% down on the same home, appraised at the price, you borrow $380,700 and pay about $114 to $266 a month of PMI. Another $4,700 reaches 20%: a $376,000 loan and no PMI requirement. Spent on points instead, the $4,700 buys about 1.23 points, roughly 6.93% under the quarter-point assumption, for principal and interest $47 below the 20%-down loan's $2,562 at the same 7.24% October 29 average, but with PMI on top. The CFPB says you can ask to cancel PMI when your balance is scheduled to reach 80% of the original value, if you meet its conditions, including a good payment history and no decline in value, and that servicers generally must end it at 78%; on the points loan those dates are about 15 and 40 months out. Even if you cancel at the first chance, the points loan catches up only after about 90 to 121 months across Freddie Mac's range, or 129 to 214 months if PMI runs to 78%.
FHA and VA work differently. The CFPB notes that every FHA loan requires mortgage insurance, so there is no 20% line. Instead, the premium table in Appendix 1.0 of HUD's Handbook 4000.1 charges 0.55% a year above 95% LTV and 0.50% at or below it on 30-year loans of $726,200 or less, and runs the annual premium for the full term above 90% LTV but 11 years at 90% or less. VA loans carry no monthly mortgage insurance, but VA's funding fee on a first-use purchase falls from 2.15% of the loan with less than 5% down to 1.5% at 5% and 1.25% at 10%, and veterans receiving VA disability compensation are exempt.
Two limits apply either way. This is a choice about your own cash: Fannie Mae does not permit interested-party contributions to make the borrower's down payment, so seller money cannot become a bigger down payment. And points pay only if you keep the loan past break-even; sell or refinance first and they are a cost you never recover. I can't tell you when rates will fall or whether you will qualify to refinance, so test both options over the shortest, likely and longest time you expect to keep the loan, and keep reserves after either. Our guide to how much to put down on a Las Vegas home covers the down payment side in depth.
How Much Does a One-Point Mortgage Rate Change Affect Your Payment?
A one-percentage-point change is 100 basis points: 7.24% to 6.24%, not a one-percent reduction of 7.24. On the same $450,000 balance with 360 monthly payments, principal and interest fall from $3,066.74 to $2,767.80, a $298.94 monthly difference. If the rate rises to 8.24%, the payment becomes $3,377.54, or $310.80 more. The two changes are not exactly symmetrical because the amortization formula is nonlinear.
| Illustrative rate | Monthly principal and interest | Difference from 7.24% |
|---|---|---|
| 6.24% | $2,767.80 | About $299 less |
| 7.24% | $3,066.74 | Baseline |
| 8.24% | $3,377.54 | About $311 more |
The calculation uses monthly rate divided into the standard amortizing-loan formula; taxes, insurance, association assessments and mortgage insurance are excluded. At $300,000 borrowed, multiply these payment differences by two-thirds. At $600,000, multiply them by four-thirds. That proportional scaling applies to the same rate and term, not to fees or loan eligibility. This is a useful way to test a Las Vegas condo and a Reno resale without pretending they have the same taxes or insurance costs.
A one-point market change is also different from buying one discount point. A discount point costs one percent of your loan amount, but the rate reduction it purchases varies. Ask for two written lender comparisons: the same purchase price at several available rates, and the same full monthly budget at several purchase prices. Do not count an unannounced rate drop as money you already have. A lower home price reduces principal today, while a hoped-for future rate has neither a guaranteed date nor a guaranteed refinance approval.
What Does a Rate Lock Actually Do?
A rate lock does not lower your rate; it freezes the rate you have been quoted so market moves cannot raise it between contract and closing. According to the Consumer Financial Protection Bureau, rate locks "are typically available for 30, 45, or 60 days, and sometimes longer," and it suggests asking lenders, "Is a shorter or longer rate lock available, and at what cost?" It also warns that "it may be expensive to extend if your transaction needs more time." On our $450,000 loan, a quarter-point rise from 7.24% to 7.49% adds about $77 a month, roughly $27,600 over thirty years. The lock is insurance against exactly that.
The CFPB is also clear about the limits of the protection: a locked rate can still change if your application changes, including your loan type, down payment, appraisal, credit score or documented income. A lock holds a price on a specific file as underwritten. Open a credit card, change jobs, or restructure your down payment mid-escrow and you can lose it. Your Loan Estimate will show whether your rate is locked, but the CFPB notes it will not show what an extension would cost, so ask. Our explanation of how Treasury yields affect mortgage rates helps put the daily moves in context.
This fall showed why locking matters. Between Freddie Mac's September 17 and October 8, 2026 releases, the national 30-year average climbed from 6.95% to 7.40%. On a $450,000 loan that is about $137 a month more, roughly $49,300 over thirty years, for a buyer whose quote moved with the average during those three weeks. It then eased to 7.24% by October 29, which is the case for a float-down. The PMMS is an average, not anyone's quote, but individual quotes move with the same market.
For a Las Vegas purchase, a sensible rule of thumb from the brokerage side of the table rather than anyone's rate desk: lock once you are under contract and know your closing date, because staying unlocked through escrow is a bet on your housing payment. The CFPB sets no timing rule; it says to make sure the lock lasts until closing. Make sure the lock period covers your realistic closing date, and ask for the extension cost the day you lock, not the week you need it. On new construction with a long build, ask the lender to price an extended lock explicitly before you sign. And get the lock terms in writing, the rate, the points and the expiration date, because a verbal "you're locked" is not a lock.
What Is a Float-Down, and Is It Worth Paying For?
A float-down answers every locked buyer's fear: what if rates drop after I lock? For a fee, or built into slightly worse pricing, a float-down provision lets you re-lock at a lower rate if the market falls before closing. Chase's explainer says one may require a minimum rate drop and can typically be used just once before closing. There is no published standard price; lenders structure and charge for float-downs differently and no agency publishes a benchmark, so treat the number below as an illustration and get your lender's written terms.
Whether it is worth it is probability math. If a lender charged a quarter point of the loan for a float-down on our $450,000 loan, that is about $1,125. If rates then fell 0.375%, from 7.24% to 6.865%, and you triggered it, you would save about $114 a month, a ten-month payback. If rates hold or rise, the fee bought nothing. It deserves a hard look on a long new-construction escrow, or when an escrow spans a stretch like this fall's.
Ask every lender you interview four things about its float-down: the trigger threshold, whether it is one-time or repeatable, the fee, and the deadline before closing after which it can no longer be exercised. Ask, too, whether a float-down is already built into the lock terms. None of those terms are ours to set or quote; they live on the lender's rate sheet, which is why it pays to interview more than one lender.
How Do You Choose the Right Rate Strategy for Your Nevada Purchase?
Strip away the jargon and the choice comes down to three questions: how long will you hold this loan, whose money is on the table, and how much contribution room does your loan program allow?
| Your situation | Strategy to price first | Why |
|---|---|---|
| Full payment affordable; early cash-flow relief valuable | Seller-funded 2-1 buydown plus a standard lock | Compare subsidy, closing credit and immediate principal reduction |
| Long-term hold, cash available, no refinance planned | Permanent points plus a standard lock | Durable savings once past the roughly five-year breakeven |
| Conventional loan within reach of 20% down | Price the larger down payment before points | At 80% LTV no PMI is required; in the 19%-down example, points took 90+ months to catch up |
| Volatile rates, 45 to 60 day escrow | Lock early plus a float-down | Protected if rates rise, still able to capture a drop |
| New construction, 6 to 12 month build | Extended lock with a float-down; negotiate the builder buydown | Long rate risk needs explicit coverage |
| Seller won't move on price | Ask for the buydown as the concession | It keeps the contract price intact |
| Low down payment, big concession ask | Compare the entire eligible concession package | The 3% conventional ceiling fills up fast |
Future rates are unknown. A seller-funded temporary buydown reduces scheduled borrower payments for a limited period, but its value must be compared with other concessions, the contract price and any refinance costs. Refinancing is subject to future eligibility and terms; it is not guaranteed. Use the full note-rate payment for long-term budgeting and ask the lender how unused subsidy funds are handled.
Two comparisons belong beside the table. First, weigh buyer-funded temporary relief against retaining cash, reducing the price, or buying permanent points; liquidity needs and the full loan terms matter. Second, some strategies can combine, subject to lender and program approval. An assumable loan may have a lower rate but require a substantial equity payment, assumption approval and possibly secondary financing. Compare total cash required and cost over your expected holding period with new-construction incentives and resale concessions.
One step belongs before all of it. Nevada licenses mortgage companies and mortgage loan originators under NRS Chapter 645B, and the Nevada Division of Mortgage Lending's licensee search page points consumers to NMLS Consumer Access. Run every loan officer you interview through it before you hand anyone a file.
How Do FHA and VA Loans Handle Buydowns and Points?
Government-backed loans follow the same broad rules with wrinkles worth knowing. The contribution ceilings are in the table above; the mechanics below are where files actually get stuck.
FHA is stricter than most buyers expect. According to HUD's Handbook 4000.1, the lender "must use the Note rate when calculating principal and interest for Mortgages that involve a temporary interest rate buydown," so the subsidy doesn't widen your approval. The handbook requires an escrow for the buydown, forbids the escrow agreement from letting undistributed funds revert to the provider if the property is sold or the loan is prepaid, and bars unexpended funds from being paid to the borrower in cash unless the borrower funded the account. If escrow payments are not received for any reason, the borrower owes the full payment in the note. Temporary buydowns are not permitted on FHA refinances or ARMs, and interested-party money may not be applied to the borrower's Minimum Required Investment, so the 3.5% minimum investment has to come from an acceptable source on your side. Our Nevada FHA loan guide covers the rest of the program.
VA draws the line in an unusual place. According to the VA Lender's Handbook (Chapter 8, Topic 5), a seller concession is anything of value added to the transaction "for which the buyer pays nothing additional and which the seller is not customarily expected or required to pay or provide," and concessions "do not include payment of the buyer's closing costs, or payment of points as appropriate to the market." Its own example: if the market dictates 7½% with two discount points, the seller paying those two points is not a concession; if the seller paid five, three would be. Escrowed funds for a temporary buydown are on the concession list, so a seller- or builder-funded 2-1 comes out of the 4% of established reasonable value, about $18,800 on a $470,000 home appraised at the price. Chapter 7, Topic 7 adds that VA buydowns are allowed only on fixed-rate loans, that the lender must determine the borrower can afford the full payment under the note without the escrow contributions (the buydown may count as a compensating factor), that escrow funds may not revert to whoever provided them, and that lenders may not fund a buydown by charging an above-market interest rate. The practical upshot: a seller can often pay normal closing costs and market-rate points outside the 4% and still fund a 2-1 inside it. Details are in our Nevada VA loan guide, and anyone shopping Sparks or Carson City on either loan should walk in with the ceiling already calculated.
USDA guaranteed loans add their own limits. Under 7 CFR 3555.151(h)(7), a funded buydown is underwritten at the note rate, can go no more than 2 percentage points below it, can rise no more than 1 point a year, and can't use the borrower's own or borrowed funds. That rules out a 3-2-1. USDA Rural Development's handbook refused our fetch, so we haven't read its detail; one lender's guide, Newrez's, dated January 30, 2025, also caps the period at 24 months, so ask your lender.
What Mistakes Do Buyers Make With Rate Strategies?
These are the common errors. Paying for a temporary buydown with buyer cash: it usually works as a concession; if the seller will not fund it, ask for the equivalent as a price cut or closing costs instead. Negotiating a concession package that exceeds the contribution ceiling: a 3% cap on a $470,000 purchase with 5% down is $14,100, and a buydown plus closing costs clears that faster than anyone expects. Buying points while planning to refinance: the roughly five-year breakeven and the "I'll refinance when rates drop" plan cannot both be true. Floating unlocked through escrow to gamble on a dip: a quarter-point move against you costs about $77 a month for thirty years on our loan, and the average moved 45 basis points in three weeks this fall. Letting a lock expire: calendar the expiration the day you lock. Qualifying math confusion: on a fixed-rate loan, Fannie Mae, Freddie Mac, FHA, VA and USDA lenders qualify you at the full note-rate payment. Taking the buydown headline at face value: Freddie Mac's 2023 research found buydown borrowers carried rates about 15 basis points higher on average, so ask for a quote with and without the buydown and compare the note rates, not just the payments. And not making lenders compete: lock terms, float-down provisions and point pricing are set lender by lender.
Do not forget the other half of rate shopping: your credit profile sets the baseline quote every strategy on this page starts from, so score work before you shop can matter as much as a buydown. Getting pre-approved early shows you where your file stands, a stronger file widens which first-time buyer programs you qualify for, and comparing your strategy against the full market at different price points sometimes shows that the best rate strategy is a slightly different house.
Why Work With Nevada Real Estate Group on Your Rate Strategy?
Because the rate strategy is negotiated in the purchase contract, not the loan application, and that is our table. To be plain about the division of labor: we are a brokerage, not a lender. We do not quote rates, price locks, or promise you a number. What we do is structure the concession that funds your rate relief, check that it fits the contribution ceiling your loan program allows before the offer goes out, and hold the timeline together so your lock does not expire.
Nevada Real Estate Group is the #1 real estate team in Nevada by RealTrends Verified, with 9,600+ closings statewide, and rate concessions are part of how we write offers: the seller-funded buydown that keeps your cash in reserves, the builder incentive package compared against the resale alternative, the closing timeline that fits inside a standard lock instead of forcing a paid extension, and the concession math run against the 3%, 6% or 9% ceiling that applies to your file. We will also push you to make several lenders compete on lock terms and float-down provisions, not just headline rates, whether you are buying in Las Vegas, Henderson, North Las Vegas or Reno. For a broader read on prices and inventory before you shop, our market report is updated on a monthly settled-data cycle.
Want to talk through your price point and timeline? Call our Las Vegas team at (702) 637-1759 or our Northern Nevada team at (775) 277-2120, or contact us here. Your loan officer confirms every binding rate figure in writing.
Frequently Asked Questions
What is the difference between a rate buydown and a rate lock?
A temporary buydown subsidizes your early payments without changing the note rate. Permanent points purchase a lower rate. A rate lock protects quoted terms for a specified period, subject to its conditions. They solve different problems and stack together: you can have a seller-funded buydown, a 45-day lock and a float-down on the same loan. Whether to add a buydown or points depends on who pays, how long you will hold the loan, and how much contribution room your program allows.
How much does a 2-1 buydown save on a typical Nevada loan?
On a $450,000 loan at a 7.24% note rate, Freddie Mac's October 29, 2026 average, a 2-1 buydown reduces the borrower's payment contribution to the amount calculated at 5.24% in year one, saving about $585 a month, and 6.24% in year two, saving about $299. The note rate remains 7.24%; escrow funds cover the difference. Total value: about $10,600, which is what the funding party deposits into the buydown escrow. On Washoe County's $595,000 September median with 5% down, the same structure saves about $734 and $376 a month and costs about $13,300. From year three you pay the full note-rate payment, and major programs qualify you at that full payment.
Can a seller agree to a buydown my lender will not allow?
Yes, and it happens. A seller-paid or builder-paid buydown is an interested-party contribution, and each program caps the total. According to Fannie Mae, conventional contributions on a primary residence or second home are capped at 3% above 90% LTV/CLTV, 6% from 75.01% to 90%, and 9% at 75% or less, with the buydown subsidy counted inside that ceiling. FHA allows 6% of the sales price, VA 4% of established reasonable value (normal points and closing costs excluded), and USDA 6% of the sales price. Confirm your ceiling with your loan officer before writing the offer.
Should I pay discount points in 2026?
Only if you will hold the loan past breakeven, roughly five years under the illustrative quarter-point-per-point pricing assumption, where one point costs $4,500 on a $450,000 loan and, at a 7.24% baseline, saves about $76 a month. The CFPB cautions that the rate reduction per point varies by lender, loan type and market, so get written pricing at zero, one and two points on the same day. If you refinance or sell before recovering their cost, the points may not pay back; compare the expected holding period, cash reserves and actual lender pricing. Per IRS Publication 936, deducting them all in the year paid requires meeting nine tests.
Is it better to pay points or put more money down?
Per dollar, a point cut the payment more at every pricing assumption tested here, but down payment money stays yours as equity. On a $470,000 home with 10% down at 7.24%, Freddie Mac's October 29, 2026 average, $4,230 buys one point worth about $71 a month under an assumed 0.25% cut, against $29 for the same cash put down, and the point pulls ahead only in month 67. If the cash takes a conventional loan to 20% down, dropping PMI can outweigh the points.
When should I lock my mortgage rate?
For a Las Vegas purchase, lock once you have a signed contract and a closing date your lock can cover, and get the rate, points and expiration in writing. That is a rule of thumb, not a regulation: the CFPB sets no timing rule, says locks typically run 30, 45 or 60 days and sometimes longer, and says to make sure yours lasts until closing. A quarter-point rise costs about $77 a month on a $450,000 loan at 7.24%, roughly $27,600 over thirty years. Freddie Mac's average rose 45 basis points between September 17 and October 8, 2026, then fell 16 by October 29, so an unlocked rate can move either way. On a long new-construction timeline, price an extended lock. A locked rate can still change if your loan type, down payment, appraisal, credit score or documented income changes.
What is a float-down and should I pay for one?
A float-down lets you re-lock at a lower rate if the market falls after you lock, and it may require a minimum drop and work only once. There is no published standard price; lenders structure and charge for it differently. Ask for the trigger threshold, the fee, whether it is repeatable, the deadline before closing, and whether one is already built into the lock terms. As an illustration, a quarter-point fee on a $450,000 loan is $1,125, repaid in about ten months if rates fall 0.375%. It is worth pricing on long new-construction escrows.
Is a seller-paid buydown better than the seller cutting the price?
It depends on the full comparison. In this $450,000, 30-year example at 7.24%, a roughly $10,600 subsidy provides about $585 of first-year monthly relief versus about $72 from an equal price reduction with unchanged cash down. The price reduction also lowers principal immediately. Compare remaining balance, cash required, payment savings, fees and unused subsidy over several holding periods. Do not rely on a future refinance to afford the full payment.
Which Sources Inform This Rate-Strategy Guide?
Payment figures are principal-and-interest calculations on 30-year fixed loans at the stated rates (standard amortization, taxes, insurance and HOA dues excluded), presented as illustrations rather than quotes. Nevada Real Estate Group is a real estate brokerage, not a mortgage lender; nothing here is a rate offer, a rate forecast, or tax advice, and every binding figure must come from your licensed loan officer. Program rules below were read against the current agency publications on November 1, 2026, and the mortgage-insurance and funding-fee sources on November 11, 2026, except USDA Rural Development's handbook, which refused our fetch; USDA points rest on federal regulations, a Federal Register proposed rule and a lender's published guide. Confirm current pricing and eligibility with your lender.
- Freddie Mac Primary Mortgage Market Survey and its weekly history file: weekly averages, 7.24% on October 29, 2026, 7.40% on October 8 and 15, and 6.95% on September 17
- Freddie Mac: About PMMS: what the survey measures
- Freddie Mac: Temporary Mortgage Rate Buydown Activity: buydown share and the 15-basis-point rate finding (July 31, 2023)
- Freddie Mac: Mortgages with Temporary Subsidy Buydown Plans: three-point and three-year limits, note-rate qualification
- Fannie Mae Selling Guide B2-1.4-04: Temporary Interest Rate Buydowns: funding sources, 3% and 1% limits, note-rate qualification
- Fannie Mae Selling Guide B3-4.1-02: Interested Party Contributions: the 2%, 3%, 6% and 9% contribution ceilings
- Freddie Mac Guide Section 5501.6: Interested Party Contributions: the same 3%, 6%, 9% and 2% financing-concession tiers (section effective July 1, 2026)
- HUD Single Family Housing Policy Handbook 4000.1: FHA 6% interested-party limit, buydown escrow, refinance and ARM restrictions (revised August 12, 2026)
- VA Lender's Handbook, Chapter 8: Topic 5, seller concessions and the 4% limit
- VA Lender's Handbook, Chapter 7: Topic 7, temporary buydown escrow and underwriting
- VA: Temporary Buydowns: funding sources and qualification on the full payment
- USDA Federal Register proposed rule, April 20, 2026: restates the 6% interested-party limit on guaranteed loans
- 7 CFR 3555.151: USDA's funded buydown rules
- Newrez USDA Underwriting Guide, January 30, 2025: a lender's published USDA buydown terms
- Chase: Float-down option: one lender's description of float-down terms
- Consumer Financial Protection Bureau: Discount Points: rate reduction per point varies by lender
- Consumer Financial Protection Bureau: Rate Locks: lock periods, extension cost, and what can still change a locked rate
- IRS Publication 936: the nine tests for deducting points in the year paid (2025 edition)
- Fannie Mae Selling Guide B7-1-01: Provision of Mortgage Insurance: mortgage insurance required above 80% LTV on conventional first mortgages (topic dated April 2, 2025)
- Freddie Mac: Breaking down PMI: approximately $30 to $70 a month per $100,000 borrowed
- Consumer Financial Protection Bureau: Removing PMI: cancellation on request at 80% of original value, automatic termination at 78% (reviewed August 28, 2026)
- Consumer Financial Protection Bureau: Mortgage insurance: FHA insurance on every loan; no monthly mortgage insurance on VA loans
- VA: Funding fee and closing costs: 2.15%, 1.5% and 1.25% first-use purchase fees by down payment (updated October 5, 2026)
- FOX5: Las Vegas REALTORS September 2026 report: $470,000 single-family median, 7,995 homes without offers, five-month supply, 2,169 sales (October 6, 2026)
- Sierra Nevada REALTORS September 2026 Market Review: Washoe County $595,000 median on 487 sales; Douglas County $660,000 on 79 sales (NNRMLS data updated October 4, 2026)
- Nevada Division of Mortgage Lending: Search Licensees: Nevada licensee search and NMLS Consumer Access
- Nevada Revised Statutes Chapter 645B: Nevada mortgage company and mortgage loan originator licensing law