Decide whether to sell your Las Vegas home by comparing the whole move: today's sale proceeds, the next housing arrangement, the cost of waiting and the outcomes you can afford if prices or rates move against you. A city median or a seasonal headline cannot answer all of those questions.
This guide was substantively updated October 21, 2026. It replaces expired spring listing windows and unsupported rate or local-price forecasts with dated market context and an explicit scenario worksheet. The historical company observations retained below are not a forecast for a current seller.
I have personally closed 5,000+ Las Vegas transactions and lead a 150+ agent team at Nevada Real Estate Group ($4.85B+ career volume, 9,600+ closings, 9,097+ five-star reviews). This guide is the working framework I use at the kitchen table to sort sellers into "list now" versus "wait" buckets — same six variables, same math.
Sell your Las Vegas home when the net proceeds and next housing plan support your timeline; wait when a specific unresolved constraint makes the move impractical. In an illustrative $550,000 sale with 6% assumed costs and a $300,000 payoff, proceeds are $217,000 before other adjustments. Compare that with several future-price scenarios, actual carrying costs and replacement housing rather than assuming appreciation or a rate cut.
- Evaluate the sale and next housing arrangement together.
- Use current comparable sales, an actual payoff and an itemized net sheet.
- Future price and rate scenarios are possibilities, not forecasts.
- Separate principal reduction, expenses and monthly cash flow.
- Compensation is negotiable; MLS concessions and broker payments have different rules.
What Should Decide Whether You Sell Now or Wait?
Start with the reason for moving and the date by which it matters. A relocation, a property that no longer works for your needs or an unsustainable carrying cost can make timing important independently of the market. A flexible owner may have more choices, but flexibility does not make waiting automatically profitable. Both paths require a complete cost comparison.
Write down six inputs: a supported current sale range, the actual payoff, estimated selling costs, the next housing cost, the required timeline and a cash reserve. Then identify which inputs are documented and which remain assumptions. A current lender demand and escrow estimate are stronger evidence than a mortgage-statement balance and a round percentage copied from an article.
Do not use equity percentage alone as the decision rule. A seller with substantial equity can still face an expensive replacement purchase, while a seller with less equity may have a compelling reason to move. The relevant question is whether the transaction and the next housing plan are workable, including any cash needed to close.
Our Las Vegas seller resources and closing-cost guide can help organize the numbers. The winter-selling discussion can frame practical seasonal preparation, but no calendar month guarantees a higher price. Choose a plan that addresses your circumstances and remains understandable when one assumption changes, rather than a categorical instruction that every owner should list or wait.
What Does the Current Las Vegas Market Snapshot Tell Sellers?
According to NREG's GLVAR/Repliers residential extract collected October 21, 2026, the MLS city field Las Vegas had 1,641 June closings at a $440,000 median, 1,460 July closings at $430,000 and 1,395 August closings at $440,000. These are all-residential records under the specified filters, not the board's existing-single-family median or a verified municipal-boundary study.
| Month | Closed records | Median sold price | Median DOM |
|---|---|---|---|
| June | 1,641 | $440,000 | 27 |
| July | 1,460 | $430,000 | 27 |
| August | 1,395 | $440,000 | 30 |
As of October 21, the separate active residential snapshot contained 9,009 records with a $458,063 median asking price. Active and sold medians describe different properties, so their difference is not a measured negotiation discount. The sample also does not establish an appreciation rate for the same house or a price change in every neighborhood.
The feed needs time for late closings to post. This analysis uses a 40-day settling rule, which means September is still preliminary on October 21. It is excluded from the settled table rather than presented as a sudden volume collapse. We do not derive growth from known incomplete August–September 2025 feed months or the anomalous January 2026 month.
For a seller, the next step is a narrower comparison: properties with similar condition, size, location and ownership costs. The Las Vegas market guide supplies broader context, while current comparable sales and active alternatives should support the price range for your actual home.
When Is Listing Soon the More Practical Choice?
Listing soon can be practical when a supported sale price and net sheet meet your needs, the property is ready and the next housing arrangement is workable. A firm move deadline may make preparation and execution more important than waiting for a favorable headline. That is a planning conclusion, not a claim that selling now always maximizes price.
First confirm that the proposed timeline is realistic. Include preparation, marketing, negotiated contract periods, funding, recording and possession. A cash buyer's requested date does not eliminate title or document requirements. A financed buyer's pre-approval is useful evidence but is not the same as a funded loan. Build a fallback for a delay if another transaction depends on the proceeds.
Next compare the cost of holding the home with the actual alternative. An empty property, a second housing payment or necessary maintenance can make waiting costly, but use your own bills and quotes. Do not infer the cost from a national average or assume every employer relocation package reimburses the same items. Read any applicable agreement before counting a reimbursement as available cash.
Finally, decide what evidence would change the plan. If an essential repair cannot be completed, the available sale range falls short or replacement housing becomes unavailable, reassess before making an irreversible commitment. Our seller resources can help structure that review without promising a particular number of showings or days to an offer.
When Is Waiting a Sensible Decision?
Waiting can be sensible when an identified problem has a realistic path to resolution: insufficient cash for the move, unfinished necessary work, uncertain replacement housing or a timeline that is still flexible. It does not require a belief that prices will rise. A useful pause has a specific objective and a review date, not just a hope that every market variable improves.
Obtain a net sheet before assuming low equity makes a sale impossible. The outcome depends on the payoff, costs, credits and any cash you can contribute. Conversely, do not assume a debt-free home makes holding free. Taxes, insurance, association charges, maintenance and the alternative use of the property still matter. Separate the monthly cash-flow requirement from the economic cost of waiting.
According to Freddie Mac's PMMS, the national 30-year fixed average was 7.40% on October 15, 2026. PMMS reports mortgage rates; it does not establish a Las Vegas appreciation forecast for 2027. This guide does not promise that waiting will produce a lower mortgage rate, a wider buyer pool or a particular recovery in your home's value.
If you wait, define the trigger for revisiting the decision. That could be completion of a repair, a reserve target, a replacement-home opportunity or a new set of relevant comparable sales. Keep a downside scenario beside the preferred one: what if prices are lower, the next home is more expensive or borrowing costs remain elevated? A plan that remains workable under those conditions is more useful than a single optimistic forecast presented with precise percentages.
How Should Seasonality Enter the Decision Without Becoming a Promise?
Seasonality can affect preparation, showing logistics and the competing inventory you encounter. It does not establish a guaranteed price difference between two future listing dates. For an October decision, advice to “list in May” is no longer actionable, and a past seasonal comparison should not be presented as a current opening that every seller can capture.
Across the 318 Q1 2026 NREG listings we've represented and the prior-year comparable seasonal cohort, May listings on the $400K–$700K band averaged $11,400 above the comparable August listings on the same comp set.
That historical company comparison is retained as an observation of the stated cohorts. It does not isolate season from condition, property mix, pricing, financing or other differences, and it should not be converted into a promised return from waiting. A current seller should compare the specific cost and benefit of moving the listing date, including what happens to replacement housing during the delay.
If waiting allows a necessary repair or a more complete document file, price that work and the carrying period explicitly. If the property is already ready, determine whether the expected benefit of delay is based on actual evidence or only on a calendar preference. Plan showing access and photography for the conditions that exist, rather than assuming presentation produces a fixed sale-price premium.
The best-time-to-sell guide provides additional considerations. Use it as a question framework and keep dated observations separate from the current property analysis. Your financial position and move requirements can outweigh a possible seasonal advantage that has not been measured for your home.
How Should Move-Up Sellers Compare Both Sides of the Transaction?
Model the sale and the purchase together. A market move that changes the sale price can also change the cost of the replacement property, but the two homes may be in different segments and need not move by the same percentage. Do not assume a larger purchase automatically creates a favorable dollar spread whenever the broader market softens.
For a transparent illustration, suppose a seller receives $445,000 and pays $30,000 in assumed selling costs, then a $255,000 payoff. The remaining cash is $160,000 before other adjustments. Applying all of it to a $625,000 purchase leaves a $465,000 loan before purchase closing costs and reserves. At an illustrative 7.40% fixed rate over 30 years, principal and interest are about $3,220 monthly. That is a calculation, not a current home or mortgage offer.
According to the CFPB Loan Estimate explainer, cash to close and the full monthly payment need separate review. If the $160,000 is all the available cash, using every dollar as down payment leaves nothing for purchase costs or a reserve. The financing plan must address that before the move is called affordable.
Compare selling first, buying first and a coordinated contingent sequence with the actual lender and contract constraints. Each has tradeoffs: temporary housing, overlapping payments, contingency risk or reduced flexibility. Our Nevada contingency guide explains why deadlines and written terms matter. A builder buydown may be one option to investigate, but a temporary subsidy does not make an unaffordable full payment safe or guarantee a future refinance.
How Should a Seller Moving to a Smaller Home Compare the Options?
Compare the total cost and function of the replacement home, not just its square footage. A smaller property can still have higher association charges, a different insurance cost, renovation needs or transaction expenses. The relevant question is whether it meets your requirements and improves the financial or practical part of the move that matters to you.
Begin with sale proceeds after actual costs and payoff, then prepare the purchase estimate. If you plan to pay cash, identify the reserve remaining after closing. If you will borrow, obtain the full payment and loan terms. If you plan to rent temporarily, use actual lease options and include deposits, moving, storage and the possibility of a second move. These alternatives should be compared over the same period.
A paid-off current home still has carrying costs, while a smaller replacement can release cash without automatically producing a better overall result. Do not assume investment returns on that cash or treat a long-term bond as a cash equivalent. Use clearly stated, appropriate assumptions and obtain individualized financial advice where an investment decision is material to the move.
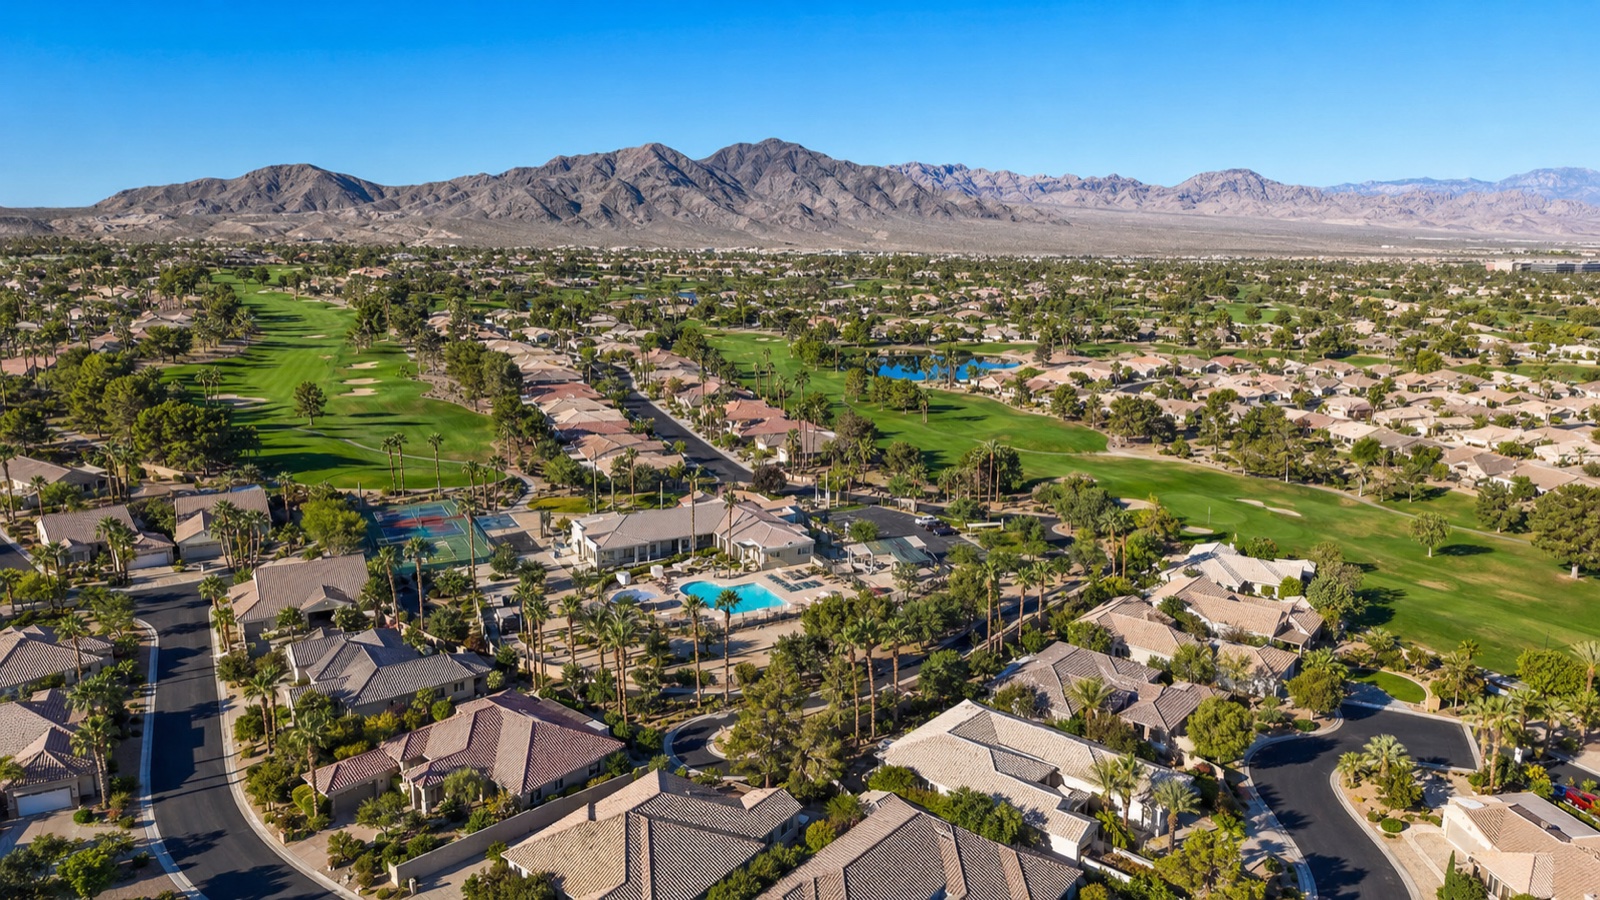
If you are considering a 55-plus community, verify its eligibility rules, property features and fees rather than assuming it is the right option from a life-stage label. The decision should follow your stated needs and the actual documents. A negotiated rent-back can be useful in some transactions, but it is not guaranteed and needs written terms, lender compatibility and an agreed possession plan.
How Should You Price the Home Without a Mechanical Discount Rule?
Use a supported range from relevant completed sales and current competition. A fixed rule such as “lowest comp plus one percent” or “trimmed median minus one percent” can give different answers without explaining the property. A credible comparison should identify the homes, dates, condition differences and reasons for any adjustment.
Do not assume an asking price a prescribed percentage below a median guarantees multiple offers. A higher price also does not automatically cost a fixed percentage per month. Those claims require evidence that accounts for differences among the properties and sellers. This guide does not use an unsupported formula for price erosion, staging return or photography return.
Review current alternatives in Summerlin, Henderson or North Las Vegas when they compete with your property. The relevant comparison depends on the actual home, not an entire city or a label such as “family tier.” If the property is unusual, explain the limited evidence rather than increasing the precision of the asking price.
Set a review plan before launch. Decide which new evidence would prompt a change in price, preparation or access. Our seller-pricing guide can help organize that discussion, while a current net sheet shows the effect of each price or credit scenario. A price should be supported by buyer alternatives and property evidence, not only by the cash needed for the next purchase.
How Should Sellers Handle Buyer-Broker Compensation and Credits?
According to NAR's offers-of-compensation guide, sellers may choose to offer compensation, must approve the amount in writing and cannot place broker compensation offers on the MLS. According to NAR's seller-concessions guide, an MLS concession cannot be conditioned on the buyer using or paying a broker. Keep a general credit and a direct compensation offer clearly distinguished.
The historical company approach described as a posted concession was: offer a posted concession upfront (for example, seller contribution toward buyer representation). Roughly 78% of NREG sellers in Q1 2026 chose this approach. For current implementation, any offer of broker compensation belongs off the MLS and requires the seller's written authorization; the historical description is not permission to put compensation into an MLS concession field.
According to Q1 2026 NREG concession data across 318 closed listings, the buyer-agent concession structure broke down as follows:
| Concession Approach | Frequency Used | Avg Concession Offered | Avg Time to Contract |
|---|---|---|---|
| Posted concession upfront (2.5%) | 62% of listings | $11,400 | 24 days |
| Posted concession upfront (2.0%) | 16% of listings | $9,475 | 28 days |
| Negotiated at offer time | 18% of listings | $8,900 | 32 days |
| No concession offered | 4% of listings | $0 | 47 days |
| Hybrid (closing cost only) | varies | $5,000–$8,500 | 29 days |
These are historical company observations, not a required rate or a causal test. Differences in time to contract do not prove that compensation alone caused the outcome, and the rows should not be turned into a guaranteed price or timing benefit. No current seller is required to select one of those amounts.
According to NAR's client-interest guide, agents must put their clients' interests first and must not steer based on compensation. Evaluate the actual offer's net proceeds, financing, contingencies and schedule. If a buyer requests assistance, ask how it will be documented and whether lender approval is needed. Our seller-concessions guide discusses the distinction further.
What Seller Mistakes Can Make Either Timing Choice More Expensive?
Across 9,600+ career closings, the three highest-cost seller mistakes are:
- Setting a price without relevant evidence. A desired net or a neighbor's unaccepted asking price is not a completed comparable sale. Build the range from appropriate records and explain differences.
- Spending on preparation without a plan. Identify necessary work, get quotes and distinguish repairs from optional finish changes. Do not assume a fixed return on every staging, landscaping or renovation expense.
- Failing to coordinate access, documents and deadlines. A buyer needs to evaluate the home, and the transaction needs information in time for contractual decisions. Organize responsibilities before the listing goes live.
This update does not attach unsupported percentages or dollar losses to those mistakes. The cost depends on the property and transaction. A maintenance issue may affect financing, while an incomplete association file may affect timing; neither can be reduced to a universal price penalty.
Review the entire move for avoidable duplication. Two moves, storage, overlapping housing, rushed repairs and a last-minute loan extension can matter more than a small fee negotiated elsewhere. Obtain quotes where possible and leave unresolved amounts visible rather than filling them with zero. A complete plan also identifies who will act if a deadline changes. That makes the decision to list now or wait more concrete: you can compare the actual work, cost and uncertainty in each path rather than choosing between two broad market stories.
How Do You Build a Fair Sell-Now-or-Wait Worksheet?
Start with today's net, then calculate several later-sale scenarios using the same cost assumptions and an appropriately updated payoff. The example below assumes a $550,000 current price, 6% selling costs and a $300,000 payoff, producing $217,000 before other adjustments. Six percent is a hypothetical input, not a standard commission or a claim about typical total costs.
For the later sale, assume a $294,000 payoff and three possible prices. These are stress-test scenarios, not forecasts or assigned probabilities. They show the later sale's cash remainder before interim housing cash flows and replacement-housing differences.
| Later price scenario | Assumed selling costs | Later sale remainder | Difference from today's $217,000 |
|---|---|---|---|
| $522,500 | $31,350 | $197,150 | -$19,850 |
| $550,000 | $33,000 | $223,000 | +$6,000 |
| $577,500 | $34,650 | $248,850 | +$31,850 |
The $6,000 improvement in the unchanged-price case comes entirely from the assumed payoff reduction. It is not free profit: principal payments that created that reduction were part of the intervening cash outflow. In a cash-flow comparison, include those payments and the final sale proceeds so they are not counted twice. In an economic-cost comparison, distinguish principal from interest and expenses.
Then add actual interest, taxes, insurance, association charges, maintenance, moving and the housing you would use after selling now. Compare replacement purchase prices and financing as well. According to the CFPB Loan Estimate guide, review the full payment and cash to close; the mortgage rate alone is not the complete cost. A fair worksheet cannot conclude “sell” merely by charging ownership costs to waiting while pretending the sell-now path has free housing.
What Should You Confirm Before Making the Final Timing Decision?
Confirm the current price range, payoff, settlement estimate, replacement housing and deadlines in writing. Separate a desired result from an obligation another party has actually accepted. A builder reservation, a lender pre-approval and a signed purchase agreement answer different questions and should not be treated as interchangeable proof that the move will work.
According to IRS Topic 701, the home-sale gain exclusion has ownership, use and lookback requirements. Cash equity and taxable gain are different, so obtain a separate tax review where the timing affects eligibility or other obligations. Do not assume a large payoff eliminates a taxable gain or that a large equity check is entirely taxable.
According to NRS 361.4723, the qualifying primary-residence abatement concerns tax-bill increases, with statutory conditions and exceptions. Use actual parcel information for the home you are leaving and any replacement property rather than assuming a universal tax percentage. New improvements and changes in claimed status can matter.
According to RealTrends, which ranks Nevada enterprise teams by 2025 transaction sides in its 2026 program, Nevada Real Estate Group closed 789 sides and approximately $361.5M in 2025 production. Our Southern Nevada coverage runs across the Summerlin master plan and its Cliffs, Kestrel and Stonebridge villages; Henderson ZIPs 89002 through 89077 (Anthem, Green Valley, Inspirada, Cadence, MacDonald Highlands, Seven Hills, Lake Las Vegas); and Las Vegas Southwest, the North Valley (Skye Canyon, Valley Vista, Tule Springs), Mountain's Edge, Centennial Hills and the resort-corridor luxury condo towers.
If you want to apply the worksheet to your own home, contact Nevada Real Estate Group or call (702) 637-1759 with the address, move date and replacement-housing plan. We can help organize current evidence and compare offers. The outcome should be a clear decision about your circumstances, without a guarantee about future prices, mortgage rates or sale timing.
Keep the final worksheet with the quotes and comparable sales that support it. Record which terms expire and which assumptions remain unresolved. If the buyer requests a new credit or the replacement-home plan changes, rerun the same calculation before accepting. This makes the decision traceable without pretending that the market outcome is certain.
Frequently Asked Questions
Should I sell my Las Vegas home now or wait until 2027?
Compare today's supported net proceeds with several future scenarios, actual carrying costs and the next housing arrangement. This research does not establish a Las Vegas price-recovery forecast for 2027. A workable move can matter more than trying to identify a market peak.
How much would I keep from a $550,000 sale?
In the hypothetical 6%-cost, $300,000-payoff example, $217,000 remains before other adjustments. Actual compensation, fees, credits, liens and prorations can change that result. Obtain a current written net sheet rather than treating the example as a quote.
Does a lower monthly market median mean my home lost that percentage?
No. Different homes sell each month. Our June–August residential medians were $440,000, $430,000 and $440,000 across changing samples. Use comparable property evidence rather than applying a group-median change mechanically to your home.
Will lower mortgage rates make waiting profitable?
Not necessarily, and a future decline is not guaranteed. Rates can affect both your buyer pool and your next purchase. Compare actual financing and several scenarios; PMMS is a rate survey, not a local home-price forecast.
Should I offer buyer-broker compensation?
It is negotiable and should be evaluated with the full offer and your net proceeds. Seller approval must be documented, broker compensation offers cannot appear on the MLS, and MLS concessions cannot be conditioned on broker payment. Agents must not steer based on compensation.
Does selling first eliminate every risk in a move-up purchase?
No. It may reduce overlapping mortgage exposure but can introduce temporary housing or replacement-home risk. Buying first has different financing and carrying costs. Compare the actual lender, contract and possession terms for both sequences.
How should I count mortgage principal while waiting?
Principal payments reduce the later payoff but also consume cash during the holding period. A cash-flow comparison includes both the payments and eventual proceeds. An economic-cost analysis separates principal from interest and other expenses so the same benefit is not counted twice.
Which Sources and Methods Inform This Analysis?
NREG collected GLVAR/Repliers aggregate residential records on October 21, 2026, using type Sale, city field Las Vegas, active status for current inventory and sold status grouped by month for June–August closings. The city field is not a verified municipal boundary. September remains preliminary under the 40-day reporting-lag rule. No repeat-sales model or local appreciation forecast was produced.
Primary references: Freddie Mac PMMS, CFPB Loan Estimate guide, NAR compensation guide, NAR concessions guide, NAR client-interest guide, IRS Topic 701 and NRS 361.4723. Payment and net scenarios are original calculations with stated assumptions. Historical company cohort observations do not establish causation or a current-market average.
NREG's 2025 production of 789 closings and $361.5M+ in volume is as ranked by RealTrends in its 2026 program.