The most common reason Las Vegas buyers give me for staying on the sidelines is one sentence: "We're waiting for rates to come down." When I first published this guide on August 23, 2026, Freddie Mac's 30-year average was 6.65% and every headline was about the Federal Reserve's September meeting. The Fed raised rates on September 16 instead; the average reached 7.40% on October 8 and 15, then eased for three straight weeks to 7.18% on November 5. On a median-priced Las Vegas home with 10% down, the wait since August still adds about $152 a month to principal and interest.
This update reruns every number at today's rate and adds the question I hear most this month: how much does a one-point rate change actually move a payment, and how much house does it cost you? The answer, with the history and every assumption shown, is below.
For most Las Vegas buyers, waiting on rates alone has not paid. Freddie Mac's 30-year average was 7.18% on November 5, 2026, up from 6.65% in August, after the Fed raised rates on September 16. On a $475,000 median home with 10% down, one percentage point moves principal and interest about $283 a month and buying power about 10%. Negotiate today's price cuts and seller credits; treat a lower rate as a refinance option, not a plan.
- Freddie Mac's 30-year average was 7.18% on November 5, 2026, up from 6.65% on August 20.
- One point on a $427,500 loan moves principal and interest about $283 down or $295 up monthly.
- A one-point drop lets the same $2,896 payment carry about $46,000 more loan, roughly 10.8%.
- Rates follow the 10-year Treasury, not Fed headlines; the 2026 low was 5.98% on February 26.
- 45.1% of listings we sampled October 15 had cut price; ask sellers to fund a buydown.
Why Doesn't a Fed Cut Automatically Lower Mortgage Rates?
The Federal Reserve sets the federal funds rate, the overnight rate banks charge each other. Your 30-year mortgage is priced off the 10-year Treasury yield plus a spread, because mortgage investors care about inflation and growth over the next decade, not tonight's rate. Our plain-English guide to the 10-year Treasury walks through the mechanics.
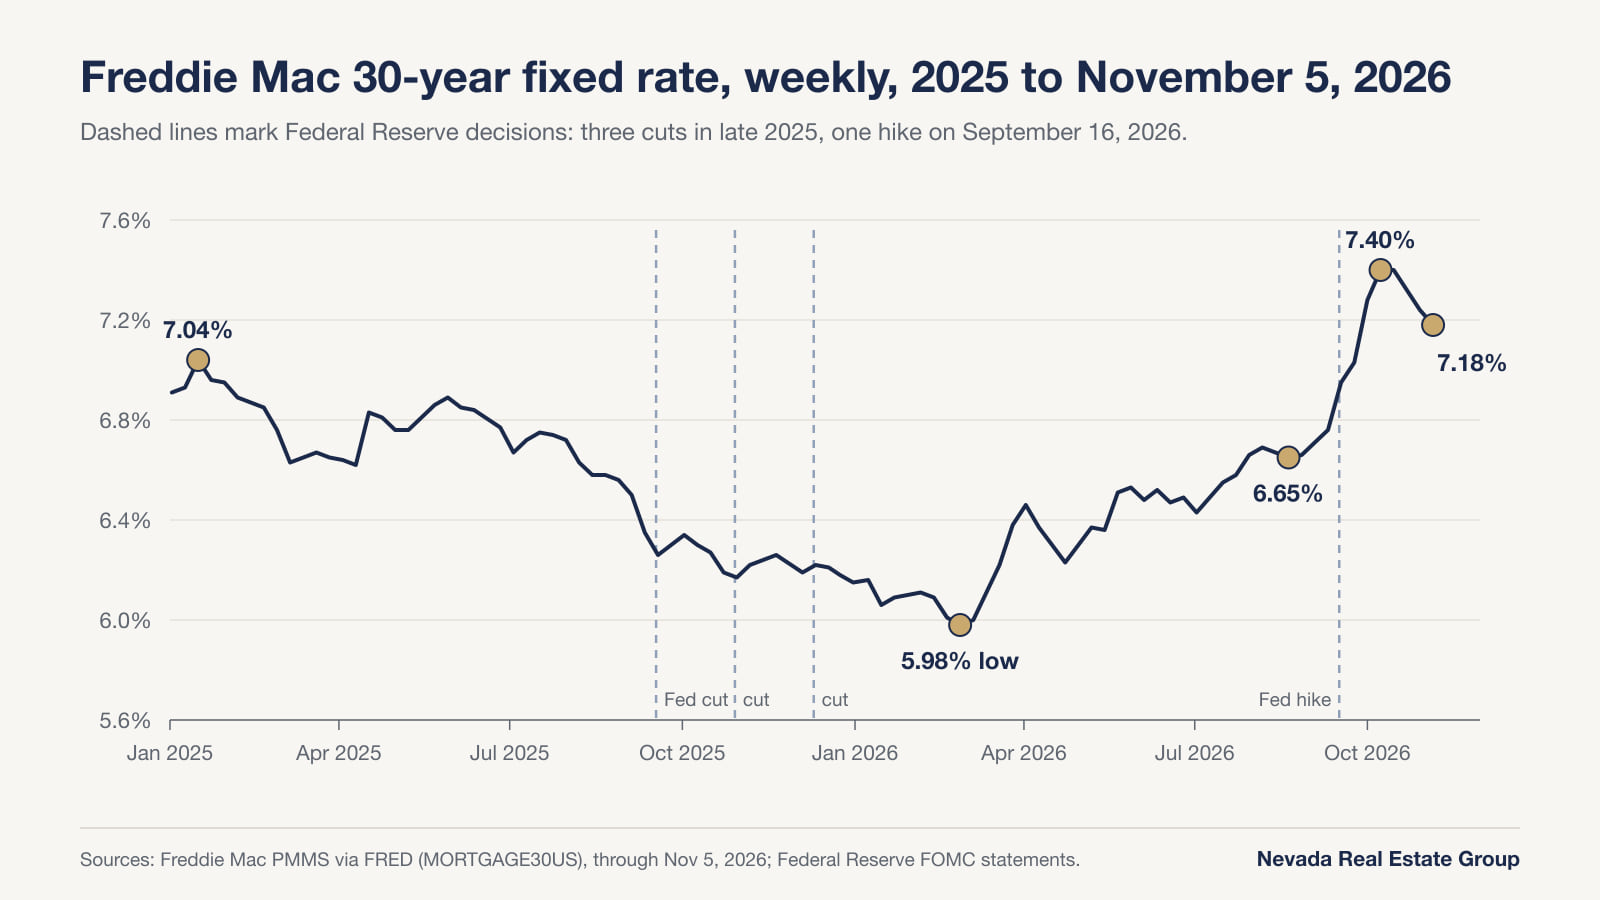
The last 13 months show the difference. According to the Federal Reserve's statements, the committee cut three times in late 2025: September 17, October 29 and December 10. According to Freddie Mac's weekly history in FRED, the 30-year average fell from 6.50% on September 4, 2025 to 6.26% on September 18 as markets priced the first cut in early, then rose to 6.34% by October 2; after the October cut it rose from 6.17% to 6.26% by November 20. Then, on September 16, 2026, the committee raised the range a quarter point to 3.75% to 4.00%, and the average climbed from 6.95% on September 17 to 7.40% on October 8. By the time headlines promise a Fed move, it is already in your quote; what moves rates afterward is the next news on inflation, jobs and government borrowing. On October 28, 2026 the committee held the range at 3.75% to 4.00% by a 10–2 vote, with both dissenters preferring another quarter-point hike, and it meets next on December 8 and 9, according to its meeting calendar.
The Fed touches your rate more directly through its mortgage-bond holdings. It resumed buying them in bulk in March 2020, let them run off from June 1, 2022 under its balance-sheet plan, and since December 1, 2025 has reinvested that principal into Treasury bills rather than new mortgage bonds, according to its October 29, 2025 implementation note. The biggest mortgage buyer of the 2020–2021 era is still stepping back.
What Has Actually Happened to Rates in 2026?
Here is the 30-year fixed's real path, priced on a $427,500 loan, what you would borrow on a $475,000 home with 10% down. According to Freddie Mac's Primary Mortgage Market Survey, the average was 7.18% for the week of November 5, 2026, down from 7.24% the week before and up from 6.22% a year earlier.
| Survey week | 30-year fixed | Principal and interest on $427,500 | What was happening |
|---|---|---|---|
| January 16, 2025 | 7.04% | $2,856 | The 2025 high |
| September 18, 2025 | 6.26% | $2,635 | Day after the first 2025 Fed cut; down from 6.50% on September 4 |
| October 2, 2025 | 6.34% | $2,657 | Rates rose for two weeks after the cut |
| February 26, 2026 | 5.98% | $2,558 | 2026 low; lowest weekly average since September 2022 |
| April 2, 2026 | 6.46% | $2,691 | The dip had reversed within five weeks |
| August 20, 2026 | 6.65% | $2,744 | When this guide first ran |
| September 17, 2026 | 6.95% | $2,830 | Day after the Fed's September 16 hike |
| October 8 and 15, 2026 | 7.40% | $2,960 | Highest since 7.44% on November 16, 2023 |
| November 5, 2026 | 7.18% | $2,896 | Latest survey; third weekly decline in a row, after 7.32% on October 22 and 7.24% on October 29 |
Rates did fall for a while: from 7.04% to 5.98%, more than a point, and buyers who were ready in February captured it. Then it reversed, and anyone still waiting gave back the whole drop.
According to U.S. News & World Report's 2026 Spring Homebuying Survey of 1,207 people planning to buy with a mortgage, as reported by USA TODAY on May 21, 2026, 62% said they were waiting for rates to fall before buying, down from 80% in 2025, and 41% of those who had put off buying in 2025 to wait for rates regretted it. That week the average was 6.51%; November 5's 7.18% costs about $191 a month more on the same $427,500 loan.
What Leverage Do Las Vegas Buyers Have Right Now?
The local numbers give buyers real room to negotiate, mostly on aged listings. According to Las Vegas REALTORS' October 2026 report, as covered by FOX5 and News 3 on November 6, 2026:
- The single-family median sale price was $475,000, up 0.1% from October 2025, up from $470,000 in September and $15,000 below the $490,000 record set in May and June 2026.
- 8,112 single-family homes were listed without offers at the end of October, up 7.6% from a year earlier.
- The sales pace equated to nearly a six-month supply, up from just over four and a half months a year earlier.
- 1,895 homes, condos and townhomes sold in October, with single-family sales down 11.9% from October 2025.
Our own count agrees. In a price-stratified sample of 700 available listings in Las Vegas, Henderson and North Las Vegas drawn on October 15, 2026, 45.1% were asking less than their original list price, the median cut was $19,900, and 67.1% of listings on the market 60 days or longer had cut. August 2026 contracts that have since closed sold at a median 97.3% of their original asking price. Our buyer's-market analysis shows the method and the margins of error.
What almost nobody waiting for rates has priced in: this leverage and low rates rarely last together. If rates drop meaningfully, waiting buyers come back at once, and in my experience price cuts and seller credits get scarce quickly. You can usually have cheap money or a motivated seller, seldom both for long.
What Does Waiting Actually Cost in Dollars?
Run it on the median: buy a $475,000 home today at 7.18% with 10% down, or wait a year hoping for 6.18%, one point lower (an example, not a forecast).
| Factor | Buy now (7.18%, Nov 5, 2026) | Wait 12 months (hope for 6.18%) |
|---|---|---|
| Purchase price | $475,000 October median, before negotiating; 45.1% of sampled listings already cut, median $19,900 | Unknown; every 3% rise adds $14,250 |
| Principal and interest | $2,896 a month on $427,500 | $2,613 if 6.18% arrives at the same price ($283 less); $2,691 if the price rises 3% ($205 less) |
| Seller concessions | Negotiable on aged listings, within loan-program caps | Likely scarcer as waiting buyers return |
| A year of rent meanwhile | No rent, but about $30,558 of year-one interest at 7.18%, plus taxes and insurance | $27,804 at HUD's $2,317 three-bedroom Fair Market Rent |
| A year of principal paydown | About $4,194 in year one | $0 |
According to HUD's fiscal 2027 Fair Market Rent schedule, effective with the fiscal year that began October 1, 2026, a three-bedroom in the Las Vegas-Henderson-North Las Vegas metro is $2,317 a month; HUD defines these as 40th-percentile gross rents, rent plus utilities.
Rent is not a one-sided cost, though. Buying now isn't free either: at 7.18%, about $30,558 of the first year's payments is interest, more than that year of rent, before taxes and insurance. The waiting year itself is closer to a wash than it looks, so the bet is decided by what comes after it. If 6.18% arrives at today's price, the waiter pays $283 a month less, about $3,399 a year, for as long as they keep the loan. If prices also rise 3%, that saving shrinks to $205 a month. And if rates go the other way, as they did from February to October, the waiter pays more every month, has skipped about $4,194 of principal paydown, and may have lost this year's negotiation too.
Price is the other lever: if prices in your target area fall faster than rates rise, the math shifts toward waiting, which is why the answer is neighborhood-specific. Our cost-of-waiting guide runs more scenarios. What the math almost never supports is waiting specifically for rates while ignoring what the local market is doing.
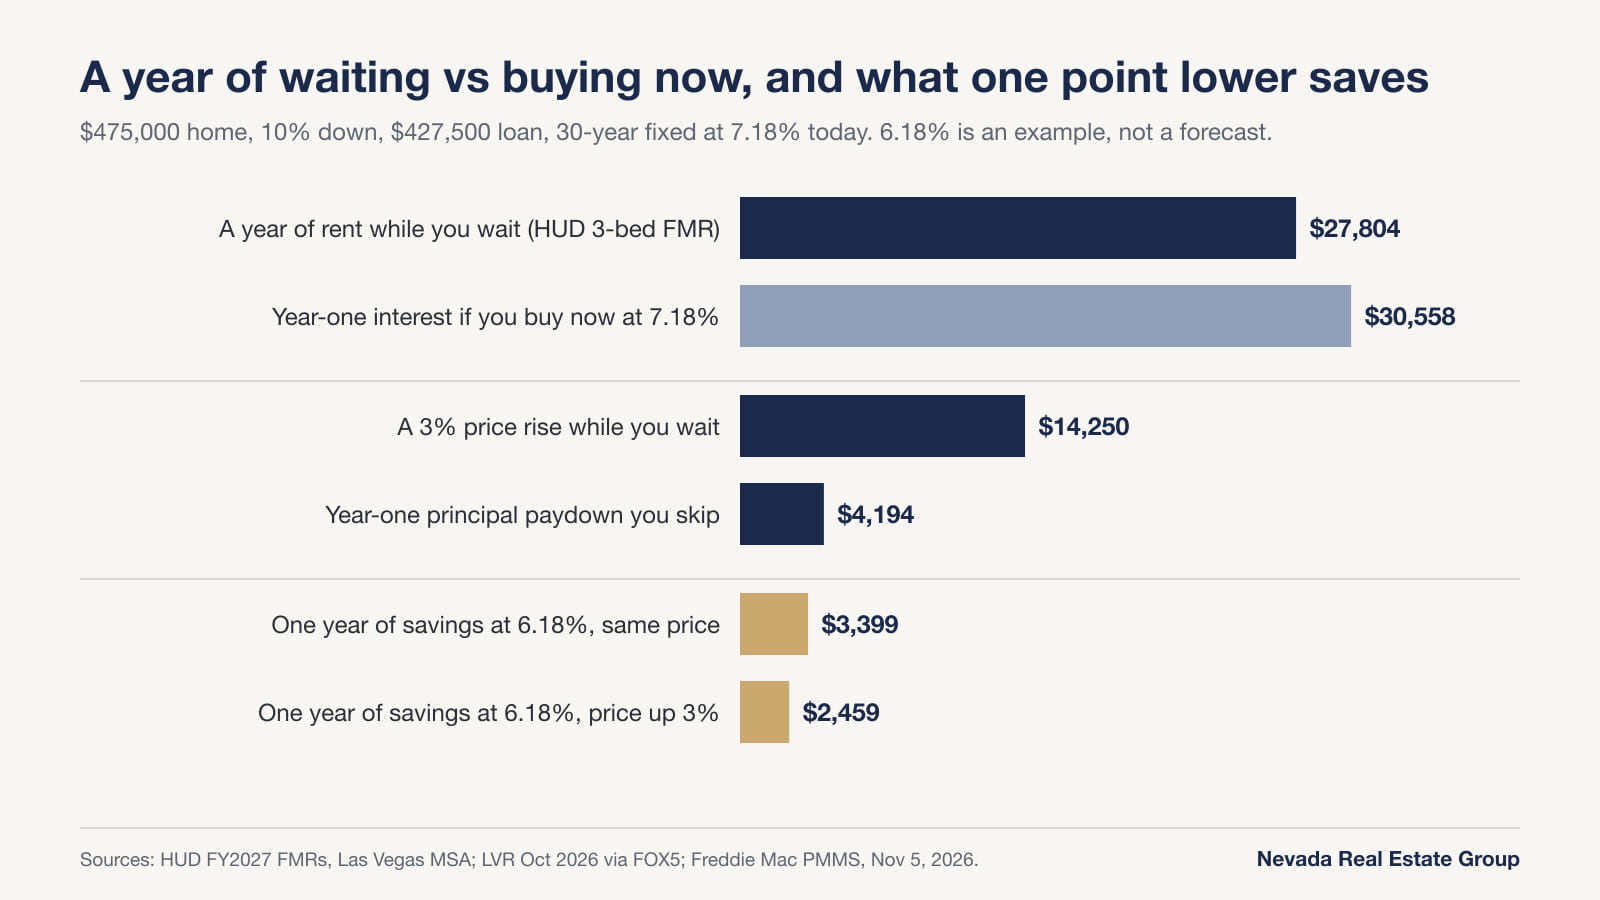
How Do You Get a Below-Market Rate Without Waiting?
In this market you do not have to accept 7.18% as your first-year payment, because sellers and builders will often help pay it down.
Seller-funded buydowns. There is no fixed price for a permanent rate cut. According to the Consumer Financial Protection Bureau, one discount point equals one percent of the loan amount, $4,275 on a $427,500 loan, but how much rate it buys "depends on the specific lender, the kind of loan, and the overall mortgage market." Treat any rule of thumb as a question for your lender. A temporary 2-1 buydown is pure arithmetic: on this loan at 7.18%, year one is paid at 5.18% ($2,342, about $554 less) and year two at 6.18% ($2,613, about $283 less), so the seller or builder deposits about $10,000 into escrow. That is about 2.1% of a $475,000 price, roughly half the $19,900 median cut in our October sample, and in year two it delivers exactly the one-point-lower payment people are waiting for. Our buydown vs rate-lock guide covers contribution caps and permanent points.
New-construction incentives. Las Vegas builders often advertise incentive financing through affiliated lenders on quick move-in homes in Summerlin, Henderson and North Las Vegas. Check whether the advertised rate is temporary or permanent, how many points it assumes, and how it compares with Freddie Mac's average that week. Our 2-1 builder buydown breakdown and new-construction hub go deeper; incentives change weekly, so I don't quote them here.
Assumable loans. A minority of listings carry FHA or VA loans from the 2020–2021 era that can transfer to a qualified buyer at the original rate, far below today's. They are rare and paperwork-heavy, and the seller's equity takes cash or a second loan; our Nevada assumable-mortgage guide explains the qualification path.
Behind all three sits the fallback: buy at today's rate with today's leverage, and refinance only if rates genuinely fall. According to Freddie Mac, a refinance typically costs 3% to 6% of the loan principal, $12,825 to $25,650 on $427,500. A full one-point drop, 7.18% to 6.18%, saves about $283 a month on the same balance, so the costs take roughly 45 to 91 months to pay back. That is why I treat one point, not half a point, as the start of a refinance conversation. You must also re-qualify on income, credit and appraisal, and a new 30-year loan restarts the clock. The fallback protects buyers who bought a payment they could carry indefinitely; it rescues nobody who stretched betting on relief.
What Should You Watch Instead of the Fed Meeting?
If you want to time anything, watch the numbers mortgages are actually priced off:
- The 10-year Treasury yield. It closed at 5.31% on October 5, 4.96% on October 22 and 4.84% on November 5, 2026, according to the Treasury series in FRED. Quotes follow it within days.
- The mortgage spread. By our calculation from FRED's weekly Freddie Mac series and the daily 10-year, the 30-year averaged 1.76 points above the 10-year on the same day from 2000 through 2019, 2.85 points in 2023 and 2.00 points across 2026's surveys through November 5. Freddie Mac's November 5 figure averages loan rates offered October 29 through November 4, when the 10-year averaged 4.94%, so the spread that week was about 2.24 points. If it narrowed to 1.76 with the 10-year unchanged, the average would be near 6.7%: arithmetic, not a prediction.
- Inflation reports. A cool monthly consumer-price report can do more for mortgage rates than a Fed decision.
- Local cut share and supply. The leverage clock: 45.1% of our October 15 sample had cut price, against 48.6% in our October 4 sample, a change inside the margin of error, and supply was nearly six months in October. When both tighten, the buyer's window is closing, whatever rates did.
None of these is a scheduled meeting with a countdown clock, and they will move your payment more than the next Fed headline.
How Much Does a One-Point Rate Change Move a Las Vegas Payment?
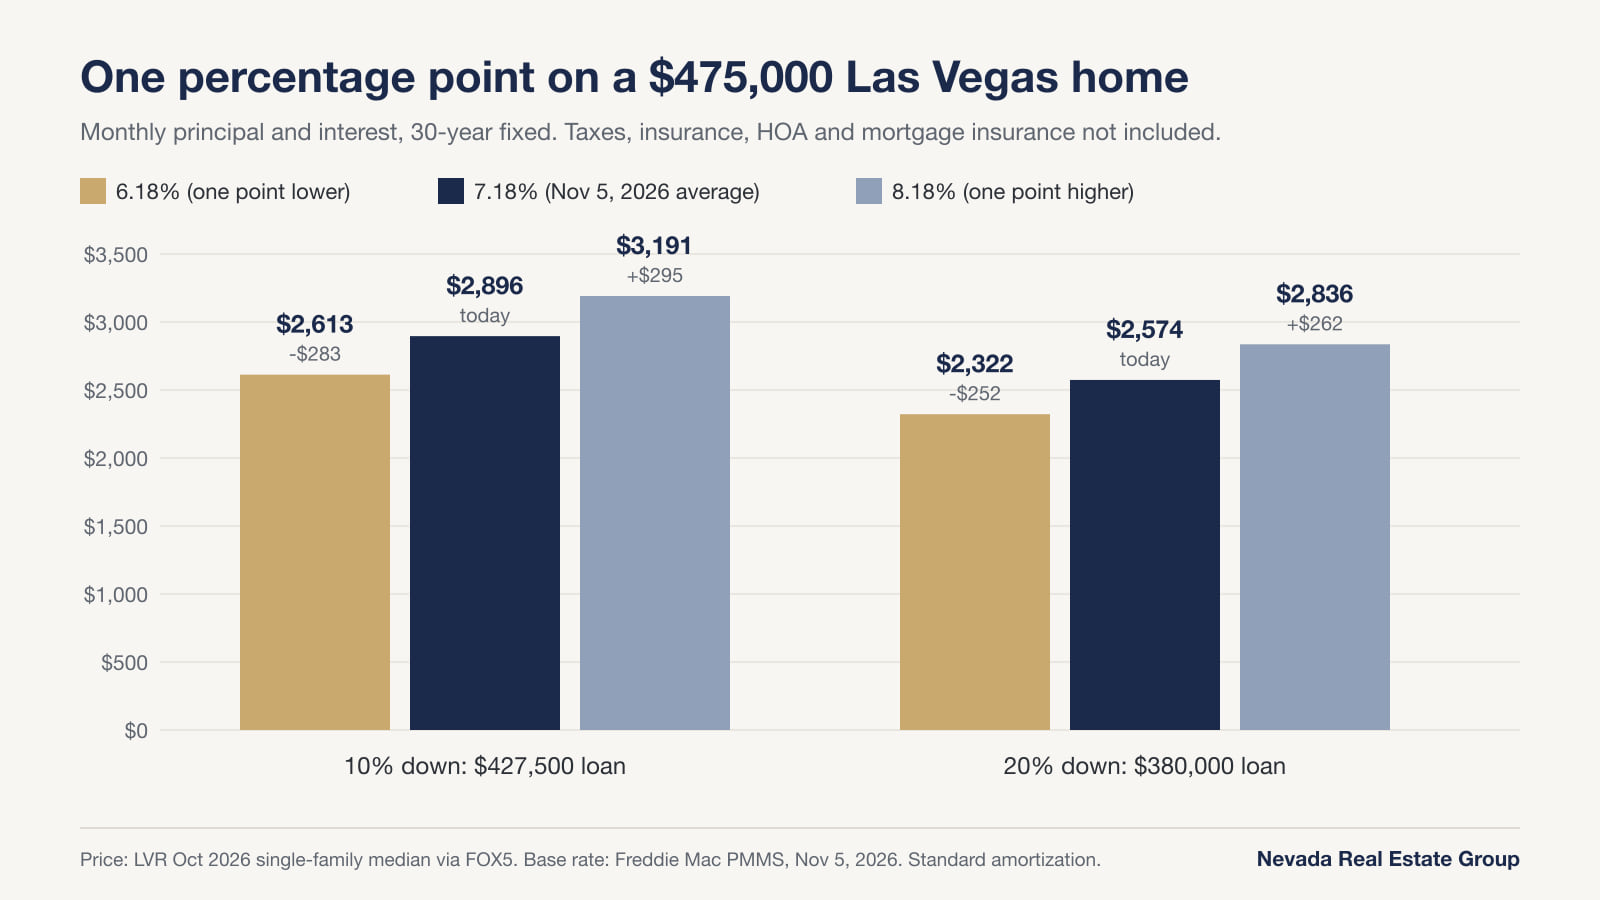
A one-point change means one percentage point, 7.18% to 6.18%, not a discount point, which is a fee of 1% of the loan. Here is the math on the Las Vegas median, with every assumption shown: a $475,000 price, the single-family median in Las Vegas REALTORS' October 2026 report as covered by FOX5; 10% down ($427,500 loan) or 20% down ($380,000 loan); a 30-year fixed term with 360 payments; and Freddie Mac's 7.18% average for November 5, 2026, plus or minus one point. Principal and interest only; taxes, insurance, association dues and mortgage insurance come on top and do not change with the rate.
| Down payment and rate | Monthly principal and interest | Change vs 7.18% | Total interest over 30 years | 30-year interest change vs 7.18% |
|---|---|---|---|---|
| 10% down ($427,500 loan) at 6.18% | $2,613 | $283 less | $513,093 | $101,979 less |
| 10% down ($427,500 loan) at 7.18% | $2,896 | Baseline | $615,072 | Baseline |
| 10% down ($427,500 loan) at 8.18% | $3,191 | $295 more | $721,135 | $106,062 more |
| 20% down ($380,000 loan) at 6.18% | $2,322 | $252 less | $456,083 | $90,648 less |
| 20% down ($380,000 loan) at 7.18% | $2,574 | Baseline | $546,731 | Baseline |
| 20% down ($380,000 loan) at 8.18% | $2,836 | $262 more | $641,008 | $94,278 more |
The rule of thumb these numbers produce: near 7%, one percentage point moves principal and interest by about $66 to $69 a month for every $100,000 you borrow, roughly 10% of the payment, and changes total interest over a full 30-year term by about $24,000 to $25,000 per $100,000. It is slightly bigger going up than down because amortization is not a straight line, and few people keep a loan 30 years, so read the interest column as the size of the stakes.
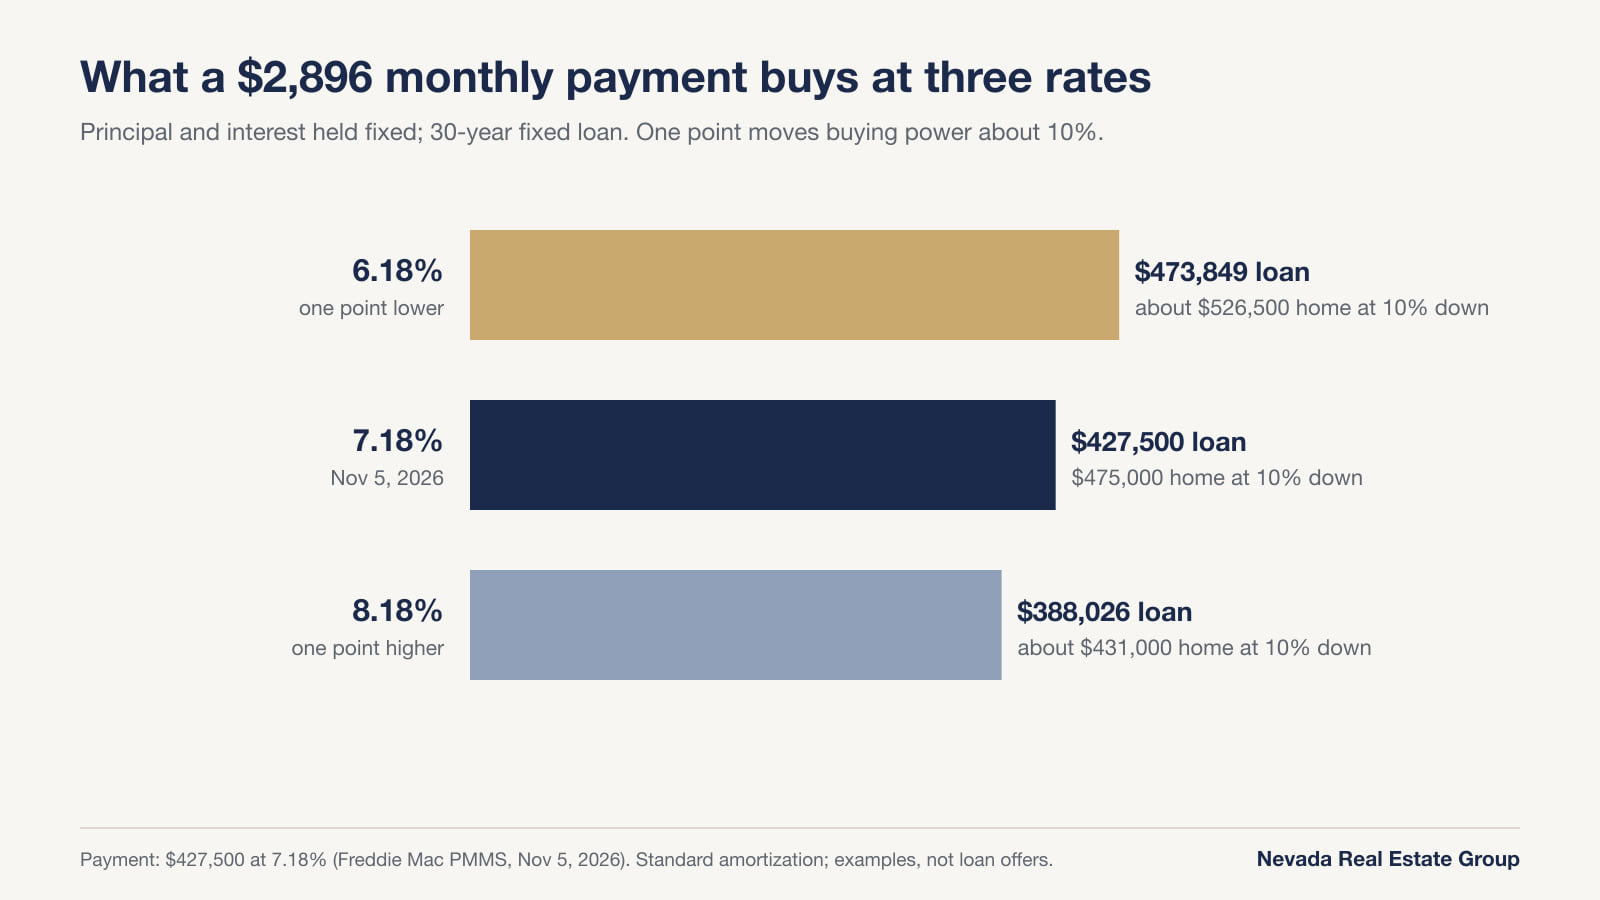
The same math works backward, the side buyers feel at pre-approval. Hold the payment fixed at $2,896, the 7.18% payment on $427,500, and change only the rate:
| Rate | Loan the payment supports | Change vs 7.18% | Home price at 10% down |
|---|---|---|---|
| 6.18% | $473,849 | $46,349 more (10.8%) | About $526,500 |
| 7.18% | $427,500 | Baseline | $475,000 |
| 8.18% | $388,026 | $39,474 less (9.2%) | About $431,000 |
So a point of rate is worth about $44,000 to $51,500 of purchase price on a median Las Vegas home, and the percentages are the same at 20% down. That is the real cost of waiting since August: the 0.53-point rise from August 20 to November 5 added about $152 a month on a $427,500 loan, or trimmed a 10%-down buyer's budget by roughly $25,000 at the same payment. For a buyer shopping homes under $500,000, a point can decide which side of that line the search lands on.
Who Should Actually Wait?
Waiting is right in some cases:
- Your horizon is under three years. Transaction costs eat short holds. Closing costs in, closing costs out, and Nevada's real property transfer tax leave little room for a plan that needs appreciation in 36 months. Renting often wins short timelines.
- Your credit is close to a better pricing band. Conventional pricing improves in steps as your score rises, through the loan-level fees our 10-year Treasury guide tabulates. Ask a lender to price your file at your current score and at the next band up; a few months of credit work can be worth more than months of Fed-watching.
- Your income is genuinely unstable. A mortgage you can barely carry at 7.18% is not fixed by a refinance that may not come. Size the payment for a bad year, not a good one.
- Your down payment is still forming. Getting from 5% down to 10% down changes your payment, your mortgage insurance and your offer's strength, so savings months can be worth more than rate months.
What separates every one of those from the rate-waiters: they are waiting on something they control, a credit score, a savings balance or a job change. Waiting on the Fed is waiting on a coin someone else flips.
What Did the Last Rate Drop Do to Las Vegas Buyers?
Freddie Mac's average slid from 6.16% on January 8, 2026 to 5.98% on February 26, the lowest weekly reading since September 2022, then climbed back to 6.38% by March 26 and 6.46% by April 2. On a $427,500 loan, 5.98% is $2,558 a month against $2,896 at November 5's 7.18%: about $338 a month, or about $4,060 a year, for as long as those buyers keep the loan. The window lasted a few weeks and arrived without a Fed meeting attached.
The dip did not come alone, either. The Southern Nevada single-family median went on to set its $490,000 record in May and June 2026, according to Las Vegas REALTORS as covered by FOX5, before easing to $470,000 in September as rates rose; October's median was $475,000. I can't prove the dip caused the spring peak, but the sequence is the one to expect: cheaper money brings more buyers, and more buyers firm up prices.
The 2021 version was the extreme case. Freddie Mac's average hit its record low of 2.65% on January 7, 2021, and cheap money met thin inventory; bidding wars followed. Cheap money is never a private invitation. It is a starting gun.
So the real trade is not "7.18% versus 6.18%," but 7.18% with almost half of listings showing a price cut, versus a lower rate with fewer cuts and more competing offers. In my experience the buyers who do best are underwritten and ready before the crowd moves.
How Do You Buy Well at 7.18%?
If the math points to acting, use the leverage:
- Get fully underwritten first, not just pre-qualified. In a market with nearly six months of supply, an underwritten buyer can move on the 60-day-old listing whose seller just got serious. Our pre-approval guide explains the difference.
- Target the sitters. In our October 15 sample, 67.1% of listings on the market 60 days or longer had already cut price. Fresh listings still anchor high.
- Ask for the buydown, not just the discount, and run both. About $10,000 of seller money funds a 2-1 buydown on a $427,500 loan, $554 off year one and $283 off year two. The same $10,000 off the price trims the loan by $9,000 at 10% down and the payment by about $61 a month, roughly $21,900 over a full 30 years. The buydown wins on early cash flow; the price cut wins if you keep the loan a long time.
- Keep the inspection contingency. Repair credits stack on top of the price negotiation.
- Model the refinance now. Know your break-even before you buy: at Freddie Mac's 3% to 6% cost range, a one-point drop on this loan pays back in roughly 45 to 91 months. Then a future rate drop is upside, not a requirement.
- Shop at least three lenders on the same day. Quotes are only comparable if pulled the same afternoon, because the 10-year moves daily. According to Freddie Mac research published February 16, 2023, in the high-rate months of October and November 2022, borrowers who got two quotes could have saved as much as $600 a year, and those with at least four quotes more than $1,200 a year.
What Would Have to Be True for Waiting to Win?
Waiting beats buying if rates fall at least a point AND prices in your target area stay flat or fall AND concessions are still there when you re-enter AND your rent stays below what owning would cost in interest, taxes and insurance. All four together is the parlay you are betting a year on, and from February 26 to November 5, 2026 the first leg went the wrong way by 1.20 points.
Nobody can tell you which way the next point goes, me included; our 10-year Treasury guide explains why forecasts miss. What you can measure is the payment you can carry today, the leverage in front of you today, and what one point is worth on your actual loan, which this guide puts at about $283 a month and about $46,000 of buying power on the median home.
So the verdict is conditional. If you are waiting on something you control, a credit band, a down payment or a job change, keep waiting and use the time. If you are waiting on the Fed, you are betting this year's price, this year's negotiation and this year's principal paydown on that parlay. The answer depends on your horizon, credit, savings and target neighborhood. We'll run the wait-versus-buy math on your actual situation, listing by listing, including which sellers are open to funding a buydown: call Nevada Real Estate Group at (702) 637-1759, or start with our buyer program. Or go straight to the live Las Vegas inventory and see which listings have already cut.
Frequently Asked Questions
Will mortgage rates drop after the December 2026 Fed meeting?
Nobody honestly knows, and I don't predict rates. The committee held its range at 3.75% to 4.00% on October 28, 2026, with two members preferring another hike, and meets next on December 8 and 9. After its September 16 hike, Freddie Mac's average climbed from 6.95% to 7.40% over the next three weeks, then eased for three straight weeks to 7.18% on November 5. Mortgages follow the 10-year Treasury and inflation expectations, so watch the bond market's reaction the next morning rather than the decision itself.
How much does a half-point rate drop save per month?
On a $427,500 loan (a $475,000 Las Vegas home with 10% down), moving from 7.18% to 6.68% saves about $143 a month in principal and interest, roughly half of what a full point saves, or about $1,718 a year. If the price also rises 3% while you wait, the saving shrinks to about $61 a month.
Is it better to buy now and refinance later?
Usually, if today's payment is one you can carry indefinitely. Freddie Mac puts refinance costs at 3% to 6% of the loan, so on $427,500 a full one-point drop, worth about $283 a month, takes roughly 45 to 91 months to pay back, and you must re-qualify on income, credit and appraisal. Buying now captures today's price cuts and seller credits; the refinance is optional upside, not a plan.
What if Las Vegas prices keep falling while I wait?
That is the strongest argument for patience, and it is neighborhood-specific. Las Vegas REALTORS put the October 2026 single-family median at $475,000, up 0.1% from a year earlier and $15,000 below the May–June record, so prices have flattened rather than fallen. If your target area drops faster than rates rise, waiting can win; watch your ZIP's cut share and days on market.
Are sellers really paying for rate buydowns in Las Vegas?
On aged listings it is a normal request. In our October 15, 2026 sample, 45.1% of available listings had cut their price, and 67.1% of those listed 60 days or longer had. A seller who has already cut once is often open to a credit instead of a second cut. Loan programs cap how much a seller can contribute, so confirm the limit for your loan before writing the offer.
What credit score do I need for the best rate right now?
There is no single cutoff. Freddie Mac's weekly average describes a borrower with good to excellent credit putting 20% down, and conventional pricing improves in steps as your score rises through Fannie Mae's loan-level fees. Pull your scores and ask a lender to price your file at your current score and at the next band up, then compare that difference with what you hope a rate drop would deliver.
How long will the current buyer's leverage last?
Watch two dials: the share of listings with price cuts (45.1% in our October 15 sample) and months of supply (nearly six months in Las Vegas REALTORS' October report, up from just over four and a half a year earlier). A meaningful rate drop would likely tighten both as waiting buyers return, which is why leverage and low rates rarely last together.
Which Sources Inform This Rate-Timing Guide?
- Freddie Mac Primary Mortgage Market Survey: weekly averages through November 5, 2026, survey window and borrower profile (read November 9, 2026)
- FRED, 30-Year Fixed Rate Mortgage Average (MORTGAGE30US): weekly history
- FRED, 10-Year Treasury Constant Maturity (DGS10): daily 10-year closes
- Federal Reserve FOMC statements: September 17, 2025, October 29, 2025, December 10, 2025, September 16, 2026 and October 28, 2026
- Federal Reserve statement of March 15, 2020, balance-sheet plans of May 4, 2022 and implementation note of October 29, 2025: mortgage-bond purchases, runoff and reinvestment
- Federal Reserve FOMC meeting calendar
- FOX5, November 6, 2026 and News 3, November 6, 2026: Las Vegas REALTORS' October 2026 report
- FOX5, October 6, 2026 and News 3, October 6, 2026: Las Vegas REALTORS' September 2026 report
- Las Vegas REALTORS housing market statistics: the association's dashboard (the October figures above come from FOX5 and News 3 coverage of the association's report)
- HUD FY2027 Fair Market Rent schedule and HUD Fair Market Rents overview
- Consumer Financial Protection Bureau, discount points
- Freddie Mac, costs of refinancing
- Freddie Mac rate-shopping research, February 16, 2023
- USA TODAY via Yahoo Finance, May 21, 2026: U.S. News & World Report's 2026 Spring Homebuying Survey
Method: payments are principal and interest only, from the standard 30-year amortization formula; they are examples, not loan quotes, and Nevada Real Estate Group is a brokerage, not a lender. Listing-cut and sale-to-list figures are from our October 15, 2026 MLS sample. Spread averages are our calculation from the two FRED series.