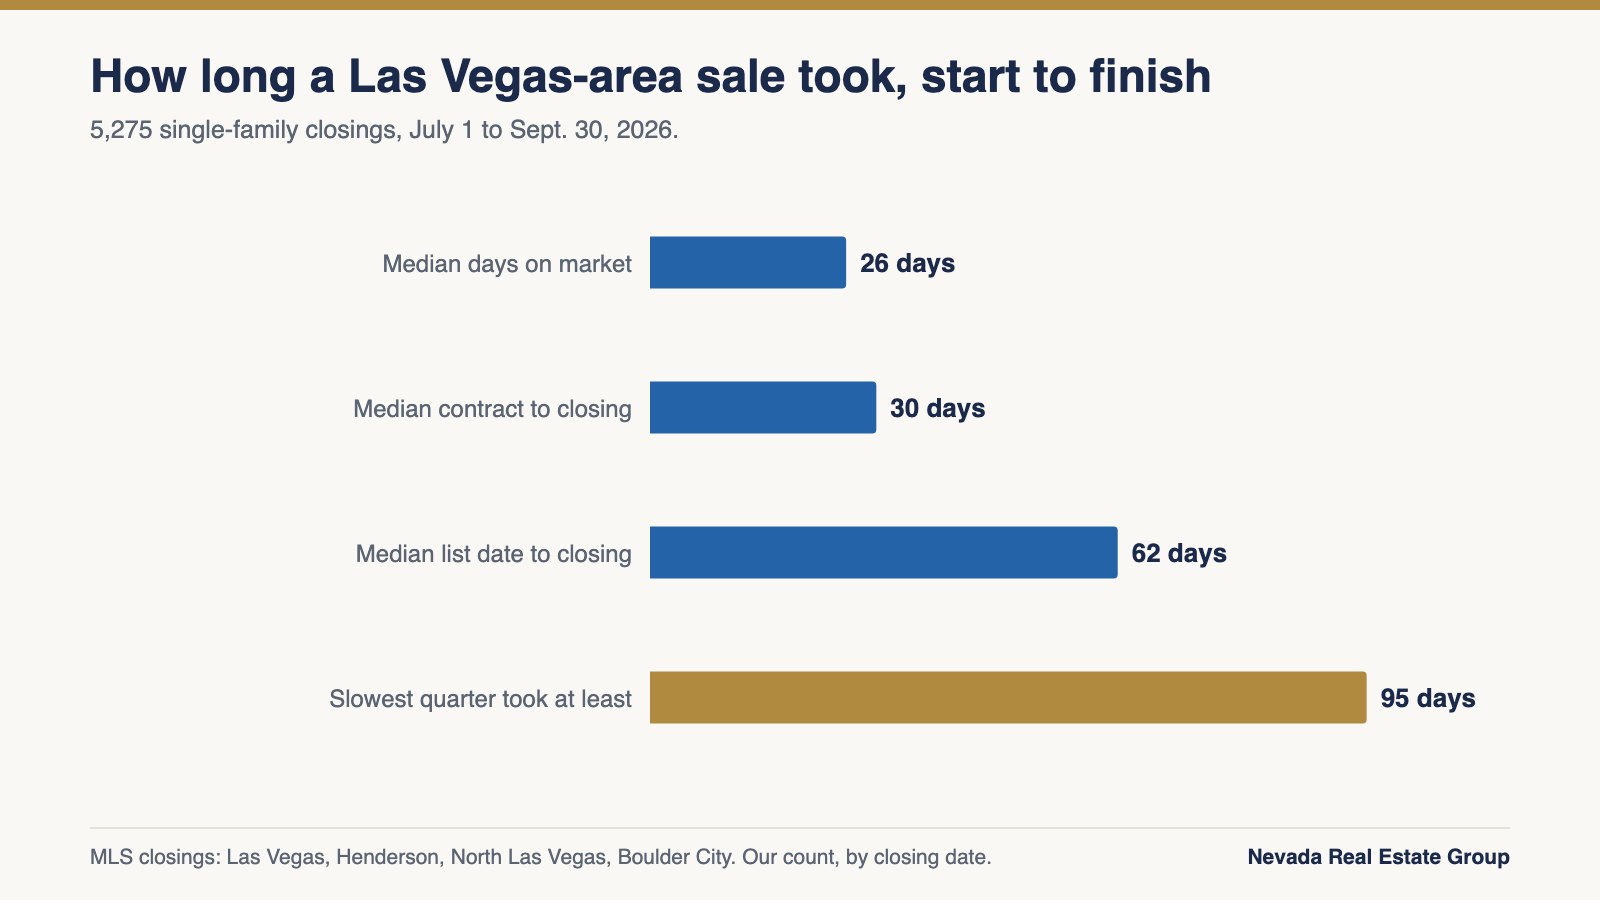
The question that keeps move-up buyers frozen in place is never about wanting the next house. It is the chicken-and-egg underneath it: how do I buy the new one when my down payment is sitting in the old one, without ending up owning two homes or none? The calendar is part of the answer. We counted 5,275 single-family closings in Las Vegas, Henderson, North Las Vegas and Boulder City from July 1 to September 30, 2026: a median 62 days from list date to closing, 30 days from contract to closing, and a quarter of sales taking 95 days or more. The fix is two decisions, made in order: the sequence of the two escrows, then the equity source that fits it.
Fall 2026 moves the math in two directions. Supply loosened to about five months in September, so the seller you buy from has more competition, and mortgage money costs more than a year ago, so every week of owning two homes costs more. This guide covers the three paths, then how a HELOC, bridge loan, cash-out refinance or buy-before-you-sell program turns your current equity into the next down payment, what each costs now, and how lenders count two mortgages.
You can buy before your Las Vegas home sells if you have cash for the next down payment and income that qualifies with both payments counted; otherwise sell first with a rent-back or write a sale contingency. Las Vegas-area single-family homes took a median 62 days from listing to closing in July through September 2026, and the 30-year rate averaged 7.24% on October 29, so sell-first is the safest default.
- Las Vegas-area homes took a median 62 days from listing to closing in July through September 2026.
- Open any HELOC before listing; AmeriSave says most lenders won't approve one on a listed home.
- Bankrate's average HELOC rate was 7.36% on October 21, 2026; bridge loans run 2-4 points above mortgage rates.
- Fannie Mae counts both payments unless your sale contract is executed with financing contingencies cleared.
- A cash-out refinance must close while the home is off the market, at today's rate on the whole balance.
What Are the Three Ways to Buy and Sell at the Same Time?
To buy your next home before your Las Vegas home sells, you need two things that don't depend on the sale: cash for the down payment and income that qualifies with both payments counted. The cash can come from a HELOC opened before you list, a bridge loan, a buy-before-you-sell program or savings. Fannie Mae counts both payments unless you have an executed sales contract with financing contingencies cleared, so test the ratio with a lender before you write an offer. If either piece fails, the sale has to come first or your offer has to be contingent on it. FHA, VA and lender rules differ, and this guide can't tell you what a particular lender will approve.
Every double move resolves into one of three sequences, and everything else in this guide hangs off which one you pick. Sell-first: close the sale, then buy, with a rent-back from your buyer bridging the gap so you never move twice. Maximum certainty and maximum negotiating strength on the purchase, because you are a non-contingent buyer with verified funds; the only cost is temporary-housing risk if the purchase drags. Buy-first: secure the new home before your sale closes, funding the down payment with a HELOC, a bridge loan, a buy-before-you-sell program or cash while your equity is still locked up. One move and the chance to renovate before moving in, at the price of carrying two homes and qualifying with both payments. Contingent: write the purchase offer contingent on your current home selling. Little double-carry risk and no bridge costs, in exchange for a weaker offer and a two-escrow domino chain.
A fourth lane, selling for cash at a known number and date, trades some price for certainty; I cover it with the buy-before-you-sell programs below, because it is really a way of unlocking equity on a deadline.
There is no universally right answer, only a right answer for your equity, your income, the rate on your current loan and this market. My advice is to pick one before you list, because a seller who lists "to see what happens" ends up reacting to whichever escrow moves first.
| Factor | Sell-First + Rent-Back | Buy-First (Equity Tools) | Contingent Offer |
|---|---|---|---|
| Financial risk | Lowest: proceeds in hand before you buy | Highest: two payments possible | Low: the purchase falls away with the sale |
| Offer strength | Strongest: no sale contingency | Strong: no sale contingency | Weakest: the seller shares your risk |
| Extra cost | Rent-back per diem, sometimes waived | Interest and fees, or a program fee | Usually none |
| Old home in your loan approval | Already sold | Counts unless the sale contract is signed and financing contingencies cleared | Usually sold first or the same day |
| Main risk | Finding the next home inside the rent-back window | The old home selling slower or lower than planned | Your sale failing and taking the purchase with it |
What Does the October 2026 Las Vegas Market Mean for a Double Move?
According to Las Vegas REALTORS' September 2026 report, released October 6, the median price of existing single-family homes sold through its MLS in September was $470,000, down 1.1% from August, level with September 2025 and below the $490,000 record set in May and June. Condos and townhomes sold at a $290,000 median. LVR counted 2,169 sales, down 7.4% for homes and 12.6% for condos and townhomes from a year earlier, a pace it put at five months of supply, up from roughly four a year ago. At the end of September, 7,995 single-family homes were listed with no offer, 6.6% more than a year earlier.
For a double move, that cuts both ways. LVR reported that 75.9% of existing homes sold in September had sold within 60 days, so plan the listing on a 60-day horizon, not a 30-day one. Our count of 5,275 single-family closings from July through September found a median 26 days on market and 30 days from contract to closing, or 62 days from list date to closing, with a quarter taking 95 days or more. Add two weeks of preparation and the median seller is about 11 weeks from decision to cash. On the buying side, the seller you negotiate with has competition of their own, which can make a rent-back request or a well-built contingency easier to hear.
Rates are the other half. According to Freddie Mac's Primary Mortgage Market Survey, the 30-year fixed averaged 7.24% as of October 29, 2026, down from 7.32% a week earlier and up from 6.17% a year ago; the 15-year averaged 6.60%. On a $450,000 loan, 7.24% means about $3,067 a month in principal and interest, roughly $319 more than at 6.17%. LVR also found 23.5% of September sales were cash, so most buyers for your current home will be financing, and their loan timeline usually sets the date your equity arrives.
Why Is Sell-First With a Rent-Back Still the Safest Default?
Because it converts your biggest weakness, needing somewhere to live, into a line item. You list, negotiate a sale that includes a post-closing occupancy agreement (the rent-back), close and collect your proceeds, then stay in your own house for up to 60 days while you shop and close the purchase as the strongest buyer on the block: verified funds, no sale contingency, a flexible timeline.
A rent-back is a negotiated ask, not a given. With five months of supply and nearly 8,000 single-family homes without offers at the end of September, your buyer has choices too, and a short rent-back is one term weighed against price and timing.
Structure it properly and it is boring, which is the goal: a written occupancy agreement (not a handshake), a per-diem rate, a deposit held in escrow against damage, proof that your insurance has converted to a renter-style policy, and a hard end date with a daily holdover charge. Have a Nevada real estate attorney review any terms that go beyond your purchase contract's standard form.
The 60-day ceiling is not a custom; it comes from your buyer's loan. According to the Fannie Mae/Freddie Mac Nevada Deed of Trust (Form 3029), the uniform instrument for conventional single-family loans in this state, the borrower must occupy the home as a principal residence within 60 days after signing and keep it as one for at least a year, unless the lender agrees otherwise in writing. An owner-occupant buyer therefore cannot give you 90 days without lender consent; a request for that much time is a signal to restructure. The same document makes misrepresenting intended occupancy a default, which matters again in the cash-out section.
How Does Rent-Back Math Work at a 7.24% Mortgage Rate?
A common starting point, and a negotiated one rather than a rule: the seller in possession pays the buyer's daily carrying cost, meaning the buyer's full monthly housing payment (principal, interest, taxes, insurance, HOA dues and any mortgage insurance) divided by thirty. Here is the piece you can calculate today. A buyer financing $450,000 on a $500,000 purchase with 10% down, at the 7.24% PMMS average for the week of October 29, 2026, pays about $3,067 a month in principal and interest, roughly $102 a day. A 45-day rent-back therefore runs about $4,600 before taxes, insurance and HOA dues. Ask for the total monthly payment on the buyer's Loan Estimate and divide by thirty; that is the defensible number.
Then the negotiating layer. A buyer can offer a free or discounted rent-back to win a home, which you would weigh against a slightly higher offer with no flexibility. The per diem is a starting convention, not a law.
One lender detail from the buyer's side: according to Fannie Mae's reserve rules, rent-back credit cannot count as a borrower's reserves, so your per diem compensates your buyer without helping them qualify.
The same discipline applies to your own purchase loan. At 7.24%, a quarter-point on a $450,000 loan is about $77 a month, roughly $27,600 over 30 years, far more than any rent-back bill, so sequence your rate lock against the realistic purchase timeline, not the optimistic one. Extension pricing varies by lender; price it before you lock, and see our guide to rate buydowns versus rate locks for a purchase that might slip.
How Can You Use Your Current Home's Equity for the Next Down Payment?
Your equity is real, but until escrow closes it is not cash. There are six ways to reach it, roughly from cheapest to most flexible: sell first and take the proceeds at closing; open a home equity line of credit (HELOC) before you list; take a bridge loan secured by the current home; do a cash-out refinance while the home is off the market; enroll in a buy-before-you-sell program that advances your equity against a backup offer; or buy with a smaller down payment and recast the new mortgage once the old home sells.
Start with the net number, not the gross one: what remains after the loan payoff, commissions, title and escrow charges and any repairs or credits. Our analysis of Las Vegas home equity by purchase year shows why purchase year matters: owners who bought before 2021 usually have room to work with, and owners who bought at the 2022 peak often do not. A home value estimate and a net sheet built on our Las Vegas seller closing costs breakdown give you the number every option depends on.
Then match the tool to the timeline. If you list within weeks, the HELOC window is closing and a bridge loan or program becomes the realistic route. Six months out, a HELOC is usually cheapest to hold. With a pandemic-era rate, the cash-out refinance is almost always the wrong tool. Government loans add one rule: according to HUD Handbook 4000.1, FHA accepts net proceeds from selling your current home, but the lender must document the actual sale with a fully executed Closing Disclosure or similar legal document, so FHA buyers who need the proceeds generally need the sale to close first.
| Option | Cost | Speed and timing | Main risk | Approval impact |
|---|---|---|---|---|
| Sell first, use proceeds | Selling costs; rent-back per diem | Equity arrives at your sale closing | Buying inside the rent-back window | One housing payment |
| HELOC opened before listing | Bankrate average 7.36%, variable; possible early-closure fees | Draw when needed; most lenders won't approve one on a listed home, per AmeriSave | Due in full at sale; line can be frozen | Its payment counts in your ratio |
| Bridge loan | 2-4 points over mortgage rates, plus 1%-3% origination | Usually 6-12 months, lump-sum payoff at sale | Maturity before the home sells | Must show you can carry both homes and the bridge |
| Cash-out refinance | Whole balance at today's rate, plus closing costs | Must close while the home is off the market; loan 12+ months old | Losing a low existing rate | Bigger first mortgage counts; 80% of value cap |
| Buy-before-you-sell program | Program fee; HomeLight's example uses 2.4% | Equity advanced before you offer | Fee and backup-offer price | HomeLight says most lenders then exclude the old payment |
| Smaller down payment, then recast | Recast fee typically $150-$500 (Bankrate, January 2026) | After the old home closes | Qualifying at the higher payment | FHA, VA and USDA loans generally can't recast |
Can You Open a HELOC While Your Home Is Listed for Sale?
Often, no, so apply before you list. Policies differ, so confirm with your lender before the sign goes up. Mortgage lender AmeriSave writes that most lenders will not approve a HELOC on a property listed on the market. Some will: Service Credit Union's HELOC terms allow a listed property but put about $900 of closing costs on the member and charge an $800 early-termination fee if the line is closed within 36 months. Service CU is based in Portsmouth, New Hampshire; it is cited only as an example of a published policy, not as a Nevada lender, so confirm any lender's Nevada availability.
That last detail matters, because a double mover opens a line intending to close it within months. According to the Consumer Financial Protection Bureau's HELOC brochure, if you sell your home you are generally required to pay off the HELOC in full immediately, so weigh the up-front costs if a sale is near. The CFPB's HELOC explainer adds that the draw period might last 10 years, repayment often runs 10 or 20 years, rates are usually variable, and the lender may freeze draws if your home's value falls significantly. Ask each lender: will you open a line on a home I plan to list, what does early closure cost, and how far ahead of listing must I apply?
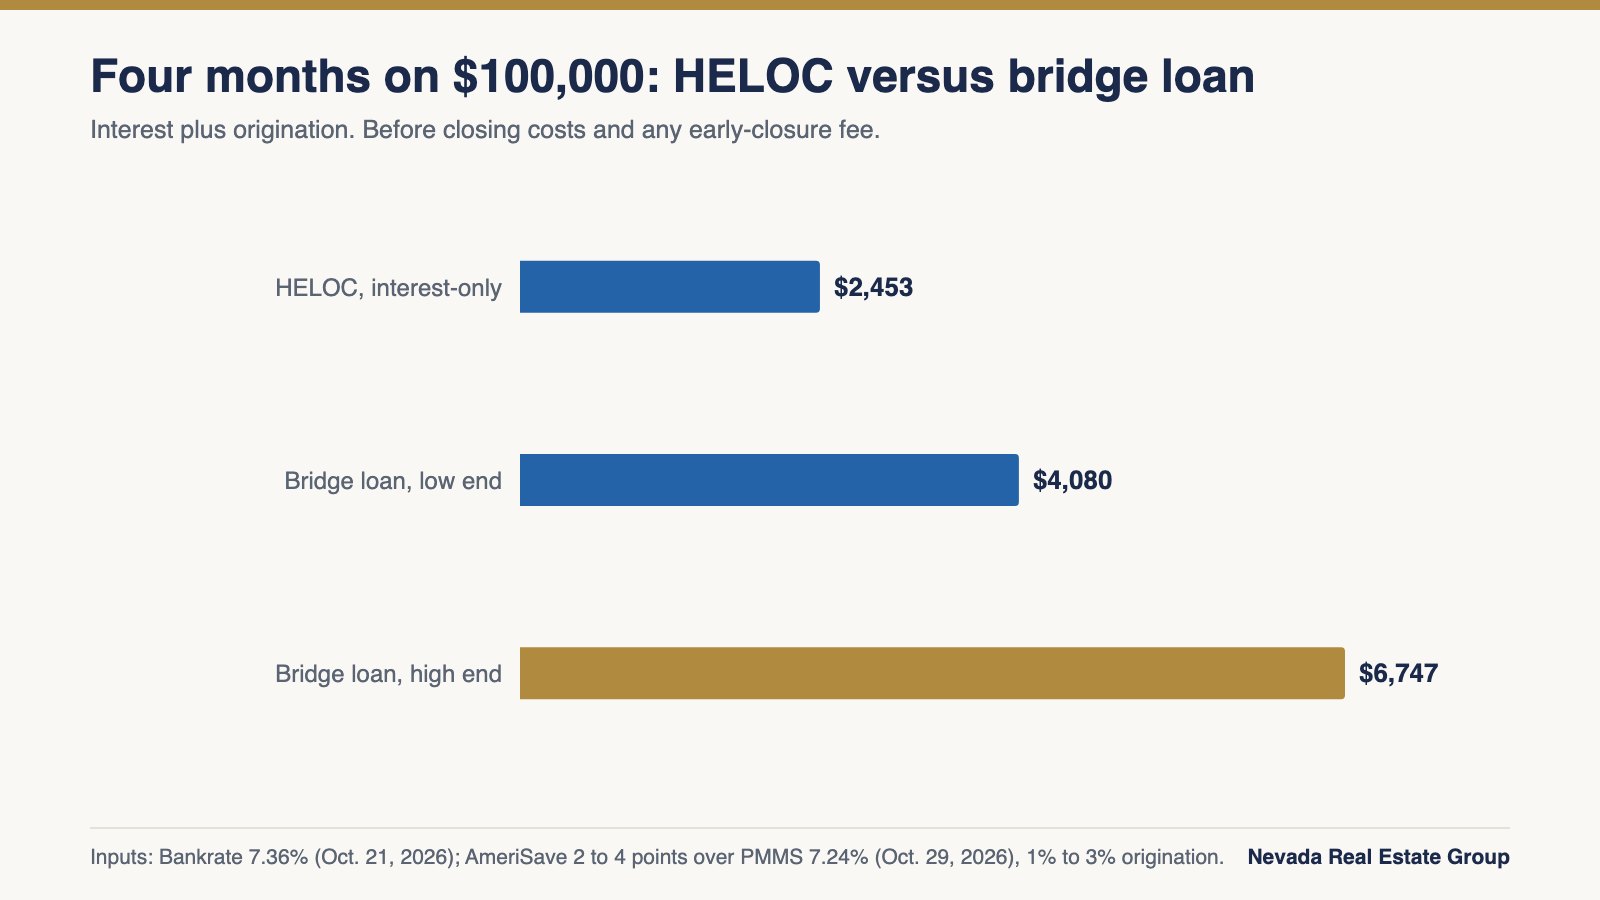
According to Bankrate's national survey, the average HELOC rate was 7.36% as of October 21, 2026, the latest on its page when we read it November 1. With the 30-year fixed at 7.24%, HELOC money costs about the same as first-mortgage money rather than points more. Bankrate's average assumes a $30,000 line, a 700 credit score and an 80% combined loan-to-value, so treat it as a benchmark: at 7.36%, a $100,000 draw paid interest-only costs about $613 a month, or roughly $2,453 over four months before fees. Bankrate says to expect at least a 15% to 20% equity stake, and the payment counts in your debt-to-income ratio while you hold both houses.
What Does a Bridge Loan Cost and How Is It Structured?
A bridge loan is a short-term loan secured by the home you are leaving, sized to cover the next down payment and repaid in one lump sum from your sale. According to AmeriSave's bridge-loan guide, read November 1, 2026, bridge loans often run six to twelve months, with origination fees usually 1% to 3% and rates typically two to four percentage points above first-mortgage rates; its six-month example adds about $2,500 to $4,000 of closing costs. It says most lenders want a mid-700s credit score and at least 20% equity in the departing home. Some lenders allow a paid extension at maturity and others don't, so get those terms in writing. AmeriSave also sells HELOCs and cash-out refinances, so read its comparisons with that in mind.
Applied to this week's market, two to four points over the 7.24% PMMS average implies roughly 9.24% to 11.24%. On a $100,000 bridge held four months, that is about $3,080 to $3,747 of interest plus $1,000 to $3,000 of origination, roughly $4,080 to $6,747 before closing costs, against about $2,453 of interest on the same HELOC draw at Bankrate's average. The bridge loan's advantage is availability, not price: once your home is listed and the HELOC door has closed, it is often the remaining way to make a non-contingent offer.
The purchase lender has rules for it too. According to Fannie Mae's Selling Guide, section B3-4.3-14, a bridge loan is an acceptable source of funds only if it is not cross-collateralized against the new property, and the lender must document that you can carry the new home, the current home, the bridge loan and your other obligations. Fannie Mae sets no term limit. So the bridge solves the cash problem, not the qualifying problem; you still need the income for both houses, or a signed sale that lets the lender drop the old payment.
Who offers them here? Flyhomes' product-availability page, read November 1, 2026, lists Nevada among the states where its bridge loans are available. Ask any lender for the all-in cost at four, six, nine and twelve months; the slow-sale case is the one you live with if the market softens.
When Does a Cash-Out Refinance Make Sense Before You Move?
Rarely, for a household selling within months, and the rules explain why. According to Fannie Mae's cash-out refinance rules (B2-1.3-03), the first mortgage being paid off must be at least 12 months old, a borrower must have been on title for six months, a Desktop Underwriter loan above a 45% debt-to-income ratio needs six months of reserves, and a property listed for sale must come off the market on or before the day the new loan disburses. The refinance has to close while the home is off the market: before you list, or after you withdraw the listing. AmeriSave's summary of cash-out limits puts the conventional ceiling at 80% of value on a one-unit primary residence, and HUD Handbook 4000.1 sets FHA's cash-out maximum at 80% too, for owners who have lived in the home for the prior 12 months.
The cost is the rate reset. Take a $500,000 home with a $250,000 balance at 3%. An 80% cash-out replaces it with a $400,000 loan, freeing about $150,000 before closing costs, but interest on $400,000 at the 7.24% PMMS average is about $2,413 a month, against about $625 on $250,000 at 3%. AmeriSave also notes that Fannie Mae's loan-level price adjustments can raise the rate on cash-out loans. You would pay closing costs on a loan you retire at your sale, and today's rate on the whole balance, to reach equity a HELOC reaches on the gap alone. With a sub-4% loan, that is the wrong trade.
It can make sense in three narrower cases: your existing rate is already at or above today's market; you plan to keep the current home as a long-term rental, so the new loan is its permanent financing (run that through our refinance timing guide and the rental rules below); or no HELOC lender will work with you and you have not listed yet.
Be candid with the lender about the move. The Nevada deed of trust makes misrepresenting your intended occupancy a default, and a refinance on a home you are about to leave is exactly where that question gets asked. Tell your loan officer the plan up front.
Which Buy-Before-You-Sell Programs Operate in Las Vegas?
We read each company's own page on November 1, 2026, and we name only programs whose pages show they are available in Nevada.
HomeLight Buy Before You Sell. According to HomeLight's program page, the program is available in every state except Alaska, Massachusetts and New York, with certain ZIP code exclusions, so confirm your address. It advances an "Equity Unlock" of up to 90% of combined loan-to-value, up to $2 million, at 0% interest, repaid from your sale; places a backup offer on your current home when you enroll; and collects the program fee at your sale. The fee is "disclosed up front," and HomeLight's own illustration uses a 2.4% program fee while stating actual fees vary. Its stated fit criteria are a conventional loan, more than 30% equity in the current home and a 620+ credit score.
Flyhomes. Flyhomes lists Nevada for its bridge loans and says its Guaranteed Backup Contract is available in all 50 states. Its buyer page says that if your old home does not sell within 180 days of the new home's closing, Flyhomes buys it at the backup contract price and returns any net profit after its transaction costs. It does not publish fees; it says they vary by solution and are based on the loan amount.
How to judge any program: the fee is only half the cost. The other half is the backup-offer price, the number you are guaranteed if the open market disappoints, and neither company publishes it on these pages. Ask how it is set, whether it moves with the market and when it expires, then compare the total against the four-month HELOC and bridge figures above.
The cash-sale lane is the simplest version of the same idea. Our cash offer program returns a no-obligation offer within 24 hours and can close in as few as 7 days or up to 60, per its page, and two national instant-offer companies, Opendoor and Offerpad, list Las Vegas as a cash-offer market on their own sites as of November 1, 2026. Put a cash number next to the listed projection, never instead of it, because the spread is the real price of certainty.
How Do Lenders Count Two Mortgages When You Buy First?
This is where buy-first plans succeed or fail. According to Fannie Mae's Selling Guide, section B3-6-06, updated September 2, 2026, if your current home is pending sale but will not close before the new purchase, the lender must qualify you with both the current and the proposed housing payment. Fannie Mae waives the old payment only with the executed sales contract on your current home and confirmation that its financing contingencies have been cleared. Under B3-6-02, the maximum debt-to-income ratio is 50% for loans run through Desktop Underwriter, and 36% (up to 45% with qualifying credit and reserves) for manual underwriting.
If you keep the old home as a rental, section B3-3.8-05 applies. The lender takes 75% of documented market rent (from an appraisal, a comparable rent schedule or rent tools with at least three comparables) and subtracts the departing home's full payment; a positive result only offsets that payment, and a negative one is added to your debts. The September 2, 2026 version does not accept lease agreements for a departing residence, and requires six months of reserves for its payment if you have under 12 months of property-management experience. Separately, B3-4.1-01 adds reserves of 2% of the unpaid balance on other financed properties when you own one to four, excluding properties sold or pending sale.
FHA is stricter. According to HUD Handbook 4000.1, last revised August 12, 2026, rental income from a home you are vacating counts only if you are relocating more than 100 miles away, with a lease of at least one year and proof of the deposit or first month's rent; without a rental history, the lender also needs an appraisal showing market rent and at least 25% equity. For a move across the valley on FHA, no rent offsets the old payment, and we found no pending-sale exclusion like Fannie Mae's in the handbook's underwriting chapters, so plan on it counting in full until the sale closes and ask your lender.
| Situation | Old payment in your ratio? | What the lender needs |
|---|---|---|
| Sale closed first | No | Proof of sale; FHA specifies the executed Closing Disclosure |
| Pending, financing contingencies cleared (Fannie Mae) | No | Executed contract plus confirmation |
| Pending, contingencies open (Fannie Mae) | Yes, both | Income for both inside 50% |
| Kept as a rental (Fannie Mae) | Net of 75% of market rent | Rent support; reserves if new to managing |
| Kept as a rental, local move (FHA) | Yes, in full | Rent counts only beyond 100 miles |
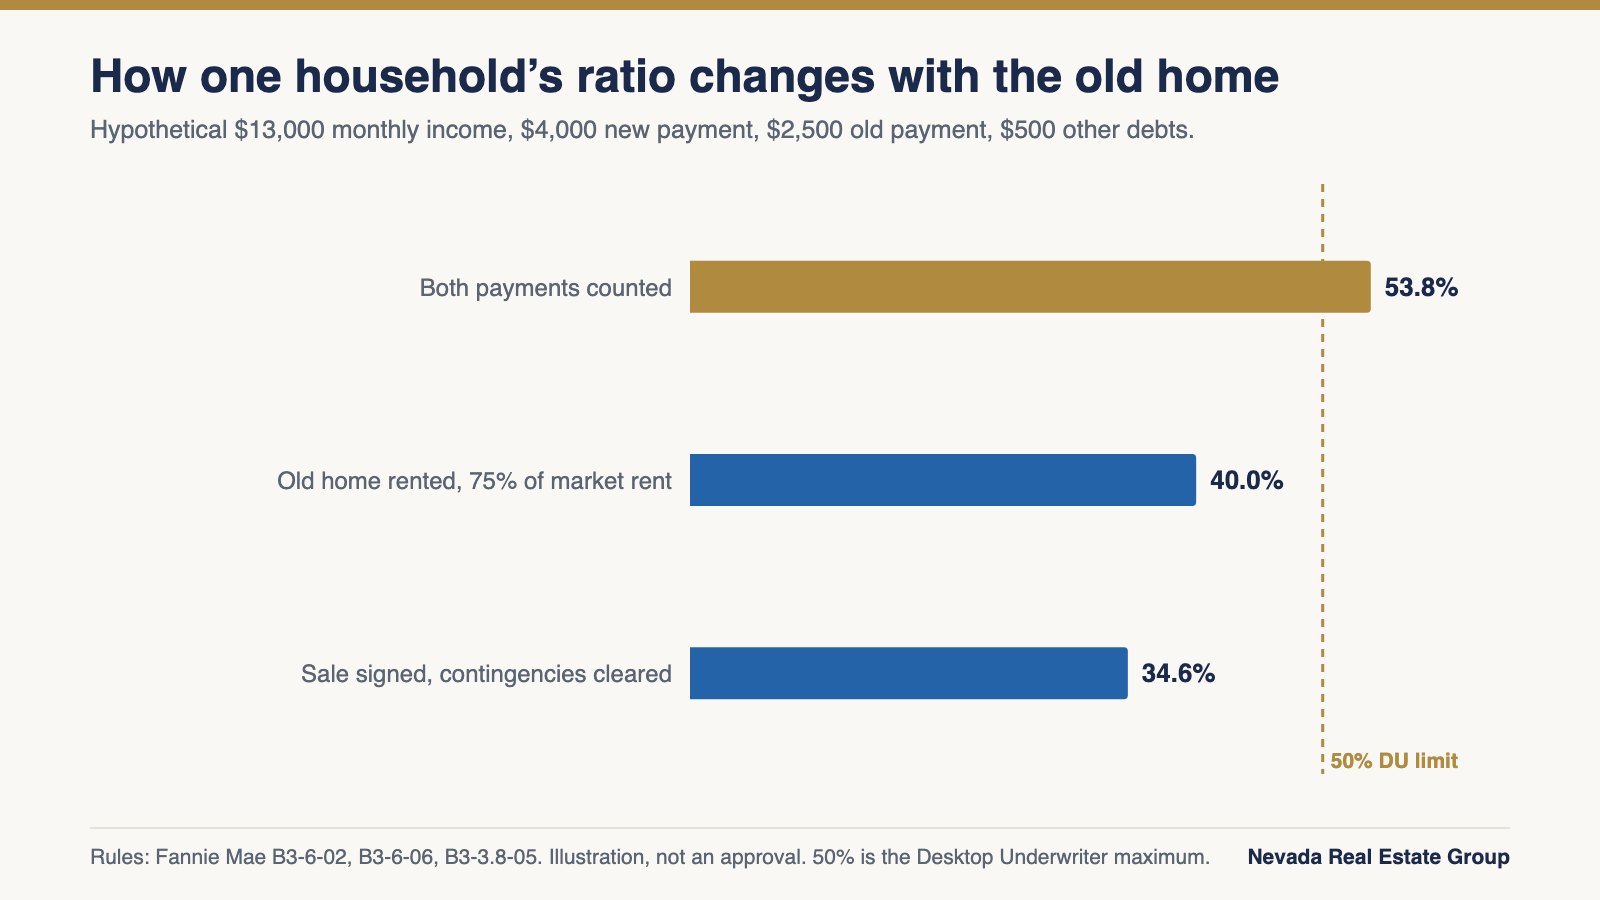
A worked example shows why the cleared-contingency rule matters. Take a hypothetical household earning $13,000 a month before tax, with a new payment of $4,000, a current payment of $2,500 and $500 of other debts. Counting both houses, the ratio is about 53.8%, over the 50% ceiling. With a signed sale whose financing contingencies are cleared, it falls to about 34.6%. Renting the old home at $2,400 of market rent gives $1,800 after the 75% factor, a $700 monthly shortfall, and a ratio of about 40.0%. Have your lender run your version before you write the offer.
How Does New Construction Change the Double-Move Timeline?
A double move that ends at a builder's design center instead of a resale closing is its own animal, because the purchase date moves. The Las Vegas new construction homes version also sits partly outside the statistics above: LVR notes its MLS figures do not account for all newly constructed homes sold by local builders. You are timing a resale against a delivery window the builder controls, and your purchase agreement, not the sales office, sets how far that window can move.
The sequencing that works: sign the builder contract first, then list your current home against the builder's construction milestones, not the original estimate. Ask for the current schedule in writing and read the contract's delivery language. Price the listing to sell in that window at sold comps, and build flexibility into both ends: a rent-back if your buyer closes before the builder delivers, and a defined short-term housing plan if the builder slips.
The equity tools behave differently here. A HELOC opened before you list can carry the builder's deposit and design-center upgrades without forcing your sale onto the builder's calendar, while a bridge loan's six-to-twelve-month term can run out if delivery slips repeatedly; match any term to the contract's outside date, not the estimate.
Two money notes. Extended rate locks on new builds cost real money, and builder incentives are frequently tied to the builder's affiliated lender, so run their numbers alongside outside quotes; our breakdown of builder closing cost credits shows which October 2026 offers required one. And buyers who close their old home before finalizing options walk the design center with cash certainty instead of a guess. The calendar differs from a resale, but the principle is identical: one project, one plan, slack built in on purpose.
Do Contingent Offers Work in Las Vegas With Five Months of Supply?
Yes, if the seller is willing, and this market gives them more reason to listen. A contingent offer says: I will buy your home, provided my current home sells and closes. With five months of supply and 7,995 single-family homes without offers at the end of September 2026, a seller whose home has sat for weeks has reason to weigh one, especially one built right.
Building it right means de-risking it for the other side. A stronger contingent offer has the buyer's current home already listed or in escrow and priced at sold comps; clean terms elsewhere, with strong earnest money and reasonable timelines; and a release clause the seller can live with. Expect to negotiate one: the seller keeps marketing, and if a backup offer arrives you get a short, written window to remove the contingency or step aside. A sale contingency carries its own written deadlines, and our guide to Nevada contingencies explains how they lapse if missed.
There is a lender angle most buyers miss. Once your own sale is under contract and your buyer's financing contingency is cleared, Fannie Mae's rule lets your lender drop the old payment from your ratio, and a pre-approval that reflects it tells the seller your financing does not depend on carrying two homes.
One brokerage handling both your listing and your purchase can put the listing's pricing, showing activity and escrow milestones in front of the seller as evidence. A seller who can see your home's activity and pending status has a reason to believe your contingency will clear.
How Do You Synchronize Two Escrows for a Same-Day Close?
Nevada's escrow system, covered in our Nevada escrow guide, handles concurrent closings routinely. The classic same-day structure: your sale records with the Clark County Recorder in the morning, the proceeds wire moves at midday, and your purchase funds and records that afternoon.
The choreography that makes it boring: one title company for both files where possible, so the transfer between escrow desks happens internally instead of between banks; matching contract calendars, with your purchase closing one to three business days after your sale, a buffer that removes most of the drama for the cost of a short rent-back; wire cutoffs respected; and a moving plan with slack, with the truck booked for the buffer date. The cutoffs are real. According to the Federal Reserve's Fedwire operating hours, the Fedwire Funds Service stops taking customer transfers at 6:45 p.m. Eastern, 3:45 p.m. in Las Vegas, and does not run on weekends or Federal Reserve holidays. Your title company may set an earlier cutoff, so ask; a Friday sale that misses the window may not fund your purchase until Monday.
Delays are common enough to plan for. According to the National Association of REALTORS' September 2026 Confidence Index, contracts nationally typically closed in 30 days, but 16% had delayed settlements and 7% were terminated over the prior three months. Our local contract-to-closing median was also 30 days. The domino failure to guard against: your buyer's loan slips, which delays your proceeds, which threatens your purchase deadline. The defenses are contractual: a per-diem extension clause in your purchase contract, a rent-back or short-stay fallback named in advance, and both escrow officers introduced in week one.
What Does the Double-Move Timeline Look Like Start to Finish?
An illustrative sell-first version:
| Weeks | Milestone | The Point |
|---|---|---|
| 1-2 | Sold-comp pricing · net sheet · path decision · purchase pre-underwriting · HELOC application if needed | Both sides armed before anything goes live |
| 3-5 | Listing live · offers negotiated with rent-back terms | The rent-back is won here |
| 5-6 | Sale in escrow · buyer's inspection and appraisal · serious shopping begins | Shop with a pending sale behind you |
| 7-9 | Buyer's financing contingency cleared · write on the new home · purchase escrow 1-3 days behind the sale | Old payment out of your ratio |
| 9-10 | Both closings · proceeds roll into the purchase | The synchronized finish |
| 10-14 | One move, inside the 60-day rent-back ceiling | The whole point |
Serious shopping runs through the advanced search once the sale is pending, when every offer you write carries real proceeds and real dates.
Total: about 11 weeks from decision to closing at the median pace (two weeks of preparation plus the 62-day median), and about 16 weeks or more for the slowest quarter of sales, so budget the longer end and let the rent-back absorb the difference. The buy-first version compresses the front and stretches the financial tail, which is why the HELOC application belongs in week one. The contingent version follows the sell-first calendar with both contracts signed early. An out-of-state leg mostly changes logistics, not structure.
One tax note to plan around rather than discover: according to the IRS's Topic 701 on selling your home, you may exclude up to $250,000 of gain on a main home, or $500,000 on a joint return, if you meet ownership and use tests of at least 24 months in the five years before the sale. If you have owned for many years, check your expected gain against those caps early. Our capital gains guide covers the rules; your tax professional should see the numbers before you set a closing date.
What Are the Costliest Double-Move Mistakes?
Seven, and each one is avoidable. Listing before opening the equity tool: most lenders won't approve a HELOC on a home for sale, and the cheapest money is gone. Buying before pricing the sale: the current home turns out to be worth less than the plan assumed; sold comps come first, always. Assuming the lender will ignore the old payment: under Fannie Mae's rule it counts until your sale contract is signed and its financing contingencies are cleared, and on an FHA local move it counts in full. Handshake rent-backs: no written agreement, no deposit, no insurance conversion, then a dispute with the people living in the buyer's new house. Contingency chains three houses long: every added link adds a way to fail, so I would avoid any chain longer than one link. Bridge debt with no exit date: set a date at which you cut the old home's price rather than keep paying two carries into a softening market. Moving-truck optimism: book the truck for the buffer day, so a 24-hour recording delay does not cascade into storage pods and hotel nights.
All seven share a root cause: treating the double move as two transactions that happen to be near each other. It is one project with two escrows and one equity decision, and it deserves one coordinated plan: one pricing strategy, one calendar, one lender conversation about how both houses are counted, and one team seeing both files. When those four line up, the double move stops being the scariest week of the year and becomes a schedule.
Frequently Asked Questions
Can you buy and sell a house at the same time in Las Vegas?
Yes. The three structures are sell-first with a rent-back, buy-first using equity from a HELOC, bridge loan or buy-before-you-sell program, and a contingent offer tied to your sale. With about five months of supply in September 2026, all three are workable; the right one depends on your equity, income and current mortgage rate.
Can I use my home equity for the down payment before my house sells?
Yes, through a HELOC opened before you list, a bridge loan, a cash-out refinance completed while the home is off the market, or a buy-before-you-sell program that advances equity against a backup offer. Each has a cost: Bankrate's average HELOC rate was 7.36% on October 21, 2026, and bridge loans typically run two to four points above mortgage rates plus origination. Your lender also counts the new debt.
Can I get a HELOC if my house is already listed for sale?
Sometimes, but AmeriSave says most lenders won't approve one on a listed home. Lenders that allow it may add closing costs and early-termination fees. Apply before you list, and ask what closing the line within a year costs, because the balance is generally due when you sell.
How much does a bridge loan cost in 2026?
AmeriSave's guide puts bridge loans at two to four points above first-mortgage rates, with 1% to 3% origination and six-to-twelve-month terms. Against the 7.24% PMMS average of October 29, that implies about 9.24% to 11.24%; on $100,000 for four months, roughly $4,080 to $6,747 in interest and origination before closing costs.
Will my lender count both mortgage payments when I buy first?
Usually. Fannie Mae counts both payments unless your current home has an executed sales contract with financing contingencies cleared. FHA counts rental income from a home you are vacating only if you are moving more than 100 miles away, so a local FHA buyer should plan on both payments until the sale closes.
What is a rent-back agreement and how much does it cost?
A rent-back, or post-closing occupancy agreement, lets you stay in your sold home while you close your purchase, up to the 60 days a conventional buyer's Nevada deed of trust allows for moving in. It is commonly priced at the buyer's daily carrying cost; at 7.24%, principal and interest alone on a $450,000 loan is about $102 a day.
Do sellers accept contingent offers in Las Vegas now?
They can, because LVR reported five months of supply in September 2026 and 7,995 single-family homes without offers at month's end. A seller is likelier to weigh one when the buyer's home is already listed or pending, priced at sold comps, and the offer includes a release clause.
What is a mortgage recast, and does it work with an FHA loan?
A recast applies a lump sum, such as your sale proceeds, to the new mortgage's principal and re-amortizes the payment at the same rate and term. Bankrate's January 2026 explainer puts the fee at typically $150 to $500, with minimum lump sums often $5,000 or $10,000. FHA, VA and USDA loans generally cannot be recast.
How Do You Start a Double Move With Our Team?
One team handling your sale and your purchase keeps one pricing strategy, one calendar, one lender conversation about how both houses are counted, and a purchase negotiation armed with evidence from your own listing. The first meeting is a planning session, not a listing appointment, and it goes faster with five things: your current mortgage statement with rate and payoff; the closing statement from your purchase, which shows your basis for the capital-gains question; any HELOC or second-mortgage paperwork; a budget and target area for the next home; and your lender's contact, if you have one, so we can confirm how they will treat your current payment.
From that we build the net sheet, the sequence, the equity source that fits it and the date each piece has to happen. If a HELOC is in the plan, we flag the latest date to apply before the listing goes live. If a buy-before-you-sell program or a cash offer is on the table, we put its total cost next to the listed projection so you see the price of certainty in dollars.
Start with a seller strategy call and a real number for your current home, browse Las Vegas homes for sale for the next one, or call (702) 637-1759 and we will map your sequence before anything goes live. Email info@nevadagroup.com anytime.
Nevada Real Estate Group · 8945 W Russell Rd, Suite 170 · Las Vegas, NV 89148 · (702) 637-1759 · NV License S.181401
Which Sources Inform This Double-Move Guide?
Sources were read on November 1, 2026, unless another date is given. MLS timing figures are our count of 5,275 single-family closings by closing date in Las Vegas, Henderson, North Las Vegas and Boulder City, July 1 to September 30, 2026; contract dates come from the MLS sold-date field.
- Las Vegas REALTORS September 2026 statistics, released October 6, 2026, as published by FOX5; LVR's statistics hub is lasvegasrealtor.com.
- Freddie Mac Primary Mortgage Market Survey, week of October 29, 2026.
- Bankrate HELOC rates, as of October 21, 2026.
- CFPB HELOC brochure and Ask CFPB: What is a HELOC?.
- Service Credit Union HELOC terms, cited as an example policy.
- Opendoor Las Vegas and Offerpad Las Vegas market pages.
- AmeriSave on bridge loans and cash-out limits.
- Fannie Mae Selling Guide: B3-4.3-14, B2-1.3-03, B3-6-06, B3-6-02, B3-3.8-05 and B3-4.1-01.
- HUD Handbook 4000.1, revised August 12, 2026.
- Fannie Mae/Freddie Mac Nevada Deed of Trust, Form 3029.
- HomeLight Buy Before You Sell, Flyhomes product availability and Flyhomes buyer programs.
- Bankrate on mortgage recasting, January 26, 2026.
- NAR September 2026 REALTORS Confidence Index.
- Federal Reserve Fedwire Funds Service operating hours.
- IRS Topic 701, Sale of your home and the Clark County Recorder.
Payment, per-diem, interest and debt-to-income figures are our arithmetic from the rates above and the stated assumptions: illustrations, not loan quotes. This guide is general information, not legal, tax or lending advice, and no attorney, CPA or lender reviewed it. Final structuring of any double move belongs with a licensed Nevada agent, your lender, a qualified tax professional for tax questions and a Nevada real estate attorney for custom contract terms.