A useful real estate definition tells you what to do with the word. A contingency needs a deadline; an assessment needs a balance and billing schedule; an approval needs a list of remaining conditions. This glossary follows those decisions from an offer through ownership, serving buyers from Las Vegas to Reno. Nevada Real Estate Group has represented 9,600+ closings statewide. The definitions below draw on the identified public authorities, with rules checked October 23, 2026 and invented examples clearly separated from actual transactions.
Start with earnest money, contingencies, escrow, seller disclosures, HOA resale documents, loan terms and title. Each describes a different obligation or protection. For a Nevada resale covered by NRS 116.4109, the buyer generally has through midnight of the fifth calendar day after receiving the resale package to cancel by written notice, before accepting conveyance. Contract and statutory deadlines must be checked separately.
- Earnest money is a deposit; the contract determines when it is refundable or at risk.
- Escrow closing, loan funding, recording and possession are separate milestones.
- Duties Owed discloses responsibilities; it does not create an agency relationship.
- Mortgage payments, HOA dues and special assessments need separate budget lines.
- Use the actual documents and applicable exceptions before relying on a glossary definition.
Which offer terms determine your obligations?
Purchase agreement means the contract governing the proposed transaction. Offer is the proposal; counteroffer changes proposed terms; acceptance must satisfy the contract’s requirements. Read the complete signed agreement and attachments together. A listing description or an informal conversation may leave important conditions unresolved. Start the deadline calendar from the event the agreement actually specifies, rather than assuming the day you first toured is relevant.
Earnest money deposit, or EMD, is money delivered under the purchase agreement. Down payment is the portion of the purchase price you fund rather than borrow. The deposit may be credited toward what you owe at closing; it is not necessarily an extra cost on top of the down payment. No single deposit percentage or inspection period applies to every Nevada purchase. Record the amount, recipient, delivery deadline and conditions for any refund in your own agreement. The earnest-money guide explains the questions to bring to that review.
Contingency means a stated contractual condition, such as an inspection, financing or appraisal condition. Its effect depends on its wording, notices and deadlines. A lender declining a loan does not automatically tell you whether the purchase contract permits cancellation. Due diligence describes investigation; its contractual scope may differ from a statutory disclosure right. As-is describes an agreed condition or repair allocation, not a universal exemption from disclosure law.
Seller credit allocates an agreed amount toward eligible buyer costs, subject to the contract and financing rules. Price reduction changes the purchase price. Escalation clause increases an offered price under specified conditions, often with a ceiling. Appraisal-gap language allocates a valuation shortfall. Before using any of them, ask for a written comparison of maximum purchase price, loan amount, required cash and cancellation rights. Our offer guide and contingency guide provide companion questions; your signed terms control the transaction.
How do earnest money and cash to close fit together?
Cash to close is the additional amount needed to complete settlement after the applicable deposits, credits and adjustments. Closing costs are charges associated with the loan and transfer. Prepaids include amounts paid in advance for specified expenses; an initial escrow deposit funds a mortgage-servicing account for later bills. These labels distinguish where money goes. They do not tell you that a quoted estimate is final.
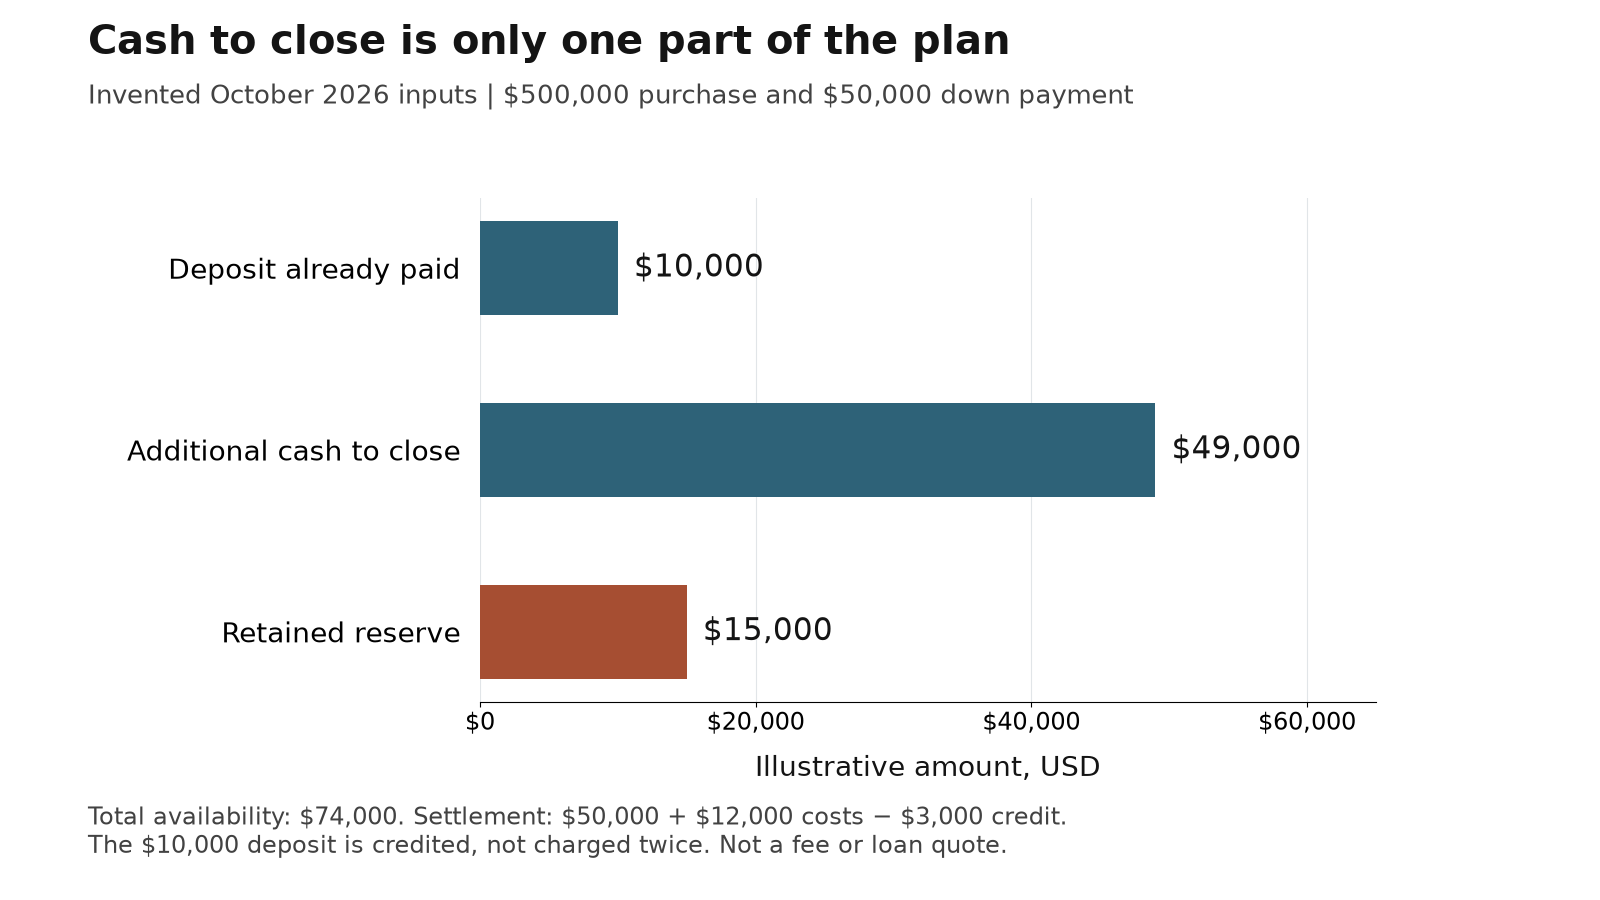
Consider an invented October 23, 2026 example: a $500,000 purchase with a $50,000 down payment, $12,000 of combined closing costs and prepaids, a $3,000 allowable credit and a $10,000 deposit already paid. Additional cash to close is $49,000: $50,000 + $12,000 − $3,000 − $10,000. Total buyer cash used for those settlement items is $59,000, including the deposit. This is an arithmetic illustration, not a fee quote, required down payment or permitted credit for every loan.
| Item | Amount | Effect |
|---|---|---|
| Down payment | $50,000 | Buyer’s purchase-price contribution |
| Costs and prepaids | $12,000 | Added to required settlement funds |
| Assumed allowable credit | −$3,000 | Offsets eligible charges |
| Deposit already paid | −$10,000 | Credited rather than paid twice |
| Additional cash to close | $49,000 | Remaining settlement funds in this example |
According to the CFPB’s Closing Disclosure explanation, cash to close should be compared with the earlier estimate and unexplained changes raised with the lender. Keep your moving budget and post-closing reserve outside the settlement calculation. If the household also wants $15,000 left after closing, this example requires $74,000 available in total, including the deposit already delivered. Ask which charges are estimates, which credits have been approved and which bills arrive after ownership begins. A paid appraisal or inspection may already have left your account without appearing as additional money due on signing day.
What does escrow mean before and after closing?
Transaction escrow is the arrangement for holding and delivering funds or documents under agreed conditions. According to the Nevada Division of Mortgage Lending’s escrow explanation, the third party holds the items until the specified event or condition occurs, then delivers them according to the instructions. An escrow officer’s role should not be confused with having an attorney represent your legal interests. You may seek legal advice about your agreement or dispute.
Close of escrow, or COE, is the closing milestone described in the agreement and escrow instructions. Signing is executing documents. Funding concerns the lender’s delivery of funds and applicable funding conditions. Recording places an instrument in the county’s public records. Possession concerns when the buyer can occupy or receive keys. Ask the escrow officer to explain the sequence for your file, and ask your agent to identify the contract’s possession language.
It is too broad to say a recorder’s stamp is always the sole legal moment ownership transfers. NRS 111.315–111.325 address recording, notice and competing interests, including validity between parties without recording. That legal distinction does not make an unrecorded deed a sensible shortcut. Resolve title and closing questions with the responsible professionals before moving money or occupying the property.
Mortgage escrow, by contrast, is an ongoing servicing account for specified bills such as property taxes and insurance. It does not mean every ownership expense is included. Proration allocates a particular charge between parties for their respective periods. Holdback describes funds retained under written conditions for a later obligation. For each item, identify who holds the money, what releases it and how disputes are addressed. The Nevada escrow guide is useful for organizing that discussion, but a glossary cannot establish that your lender has funded or that possession has been authorized.
How should you read the loan disclosure vocabulary?
Loan Estimate, or LE, is the standardized estimate for a covered mortgage application. According to the CFPB’s Loan Estimate guide, it is generally provided within three business days of the application and does not itself mean the loan is approved. Closing Disclosure, or CD, provides final loan terms and costs; the CFPB’s CD explanation describes the required delivery at least three business days before closing for covered loans. Reverse mortgages, HELOCs and certain other products use different disclosures.
Promissory note records the debt promise and payment terms. Deed of trust or security instrument concerns the property securing repayment. Neither is the same as the deed conveying ownership. According to the CFPB’s closing-document guide, borrowers should review these contractual documents alongside the disclosures. Ask for copies early enough to resolve discrepancies in names, loan amount, term or payment changes.
Prequalification, preapproval and underwriting describe stages or levels of lender review, but the labels alone do not establish what was checked. Request the remaining conditions, expiration date and property-related requirements. An approved borrower can still be purchasing a property that raises appraisal, insurance or project issues. Do not waive a financing protection because a marketing letter sounds final.
Build a comparison sheet using the same loan amount, term, product and proposed lock period. Mark every difference in lender fees, points, credits, mortgage insurance and cash to close. Keep the original estimate and each revision so a changed figure can be traced to a changed input. A lower monthly payment created by a longer term needs a different comparison from a lower rate on the same term. Review the total costs over a plausible ownership and loan period, without assuming a future refinance will be available.
Which payment and ratio terms belong in your budget?
Principal is the outstanding amount borrowed; interest is the financing charge. Amortization describes how scheduled payments reduce a loan balance over time. PITI combines principal, interest, taxes and insurance. It is not a promise that a quoted payment includes mortgage insurance, association charges, assessments, utilities or repairs. Ask the lender to label what is included and build the household budget from the full list.
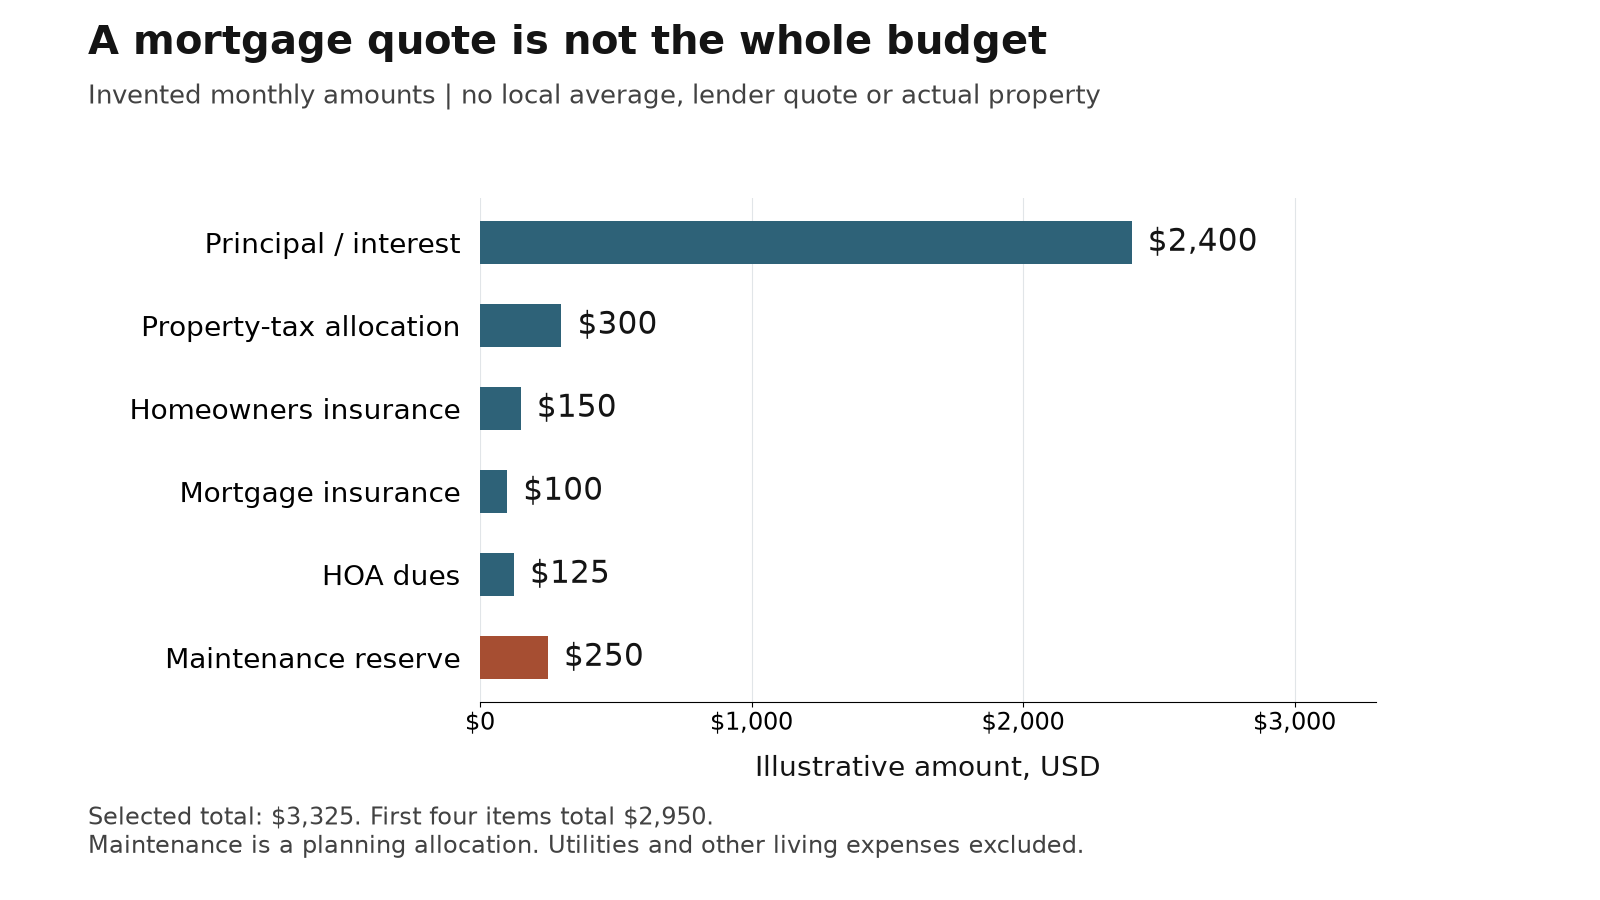
An invented October 23, 2026 budget illustrates the distinction: $2,400 principal and interest, $300 property-tax allocation, $150 homeowners insurance and $100 mortgage insurance total $2,950. Adding $125 HOA dues and $250 maintenance allocation produces $3,325 before utilities or other living expenses. Those are assumed monthly amounts, not a mortgage quote or local cost average. The maintenance allocation is money reserved for future work, not a mandatory payment to the lender.
Debt-to-income ratio, or DTI, compares monthly debt payments with gross monthly income. According to the CFPB’s DTI explanation, product and lender limits differ. A lender’s qualifying calculation is not a complete household spending plan. Loan-to-value, or LTV, compares the financed amount with the relevant property value; the CFPB’s LTV guide explains its relationship to lending decisions and costs. Ask which value the specific program uses.
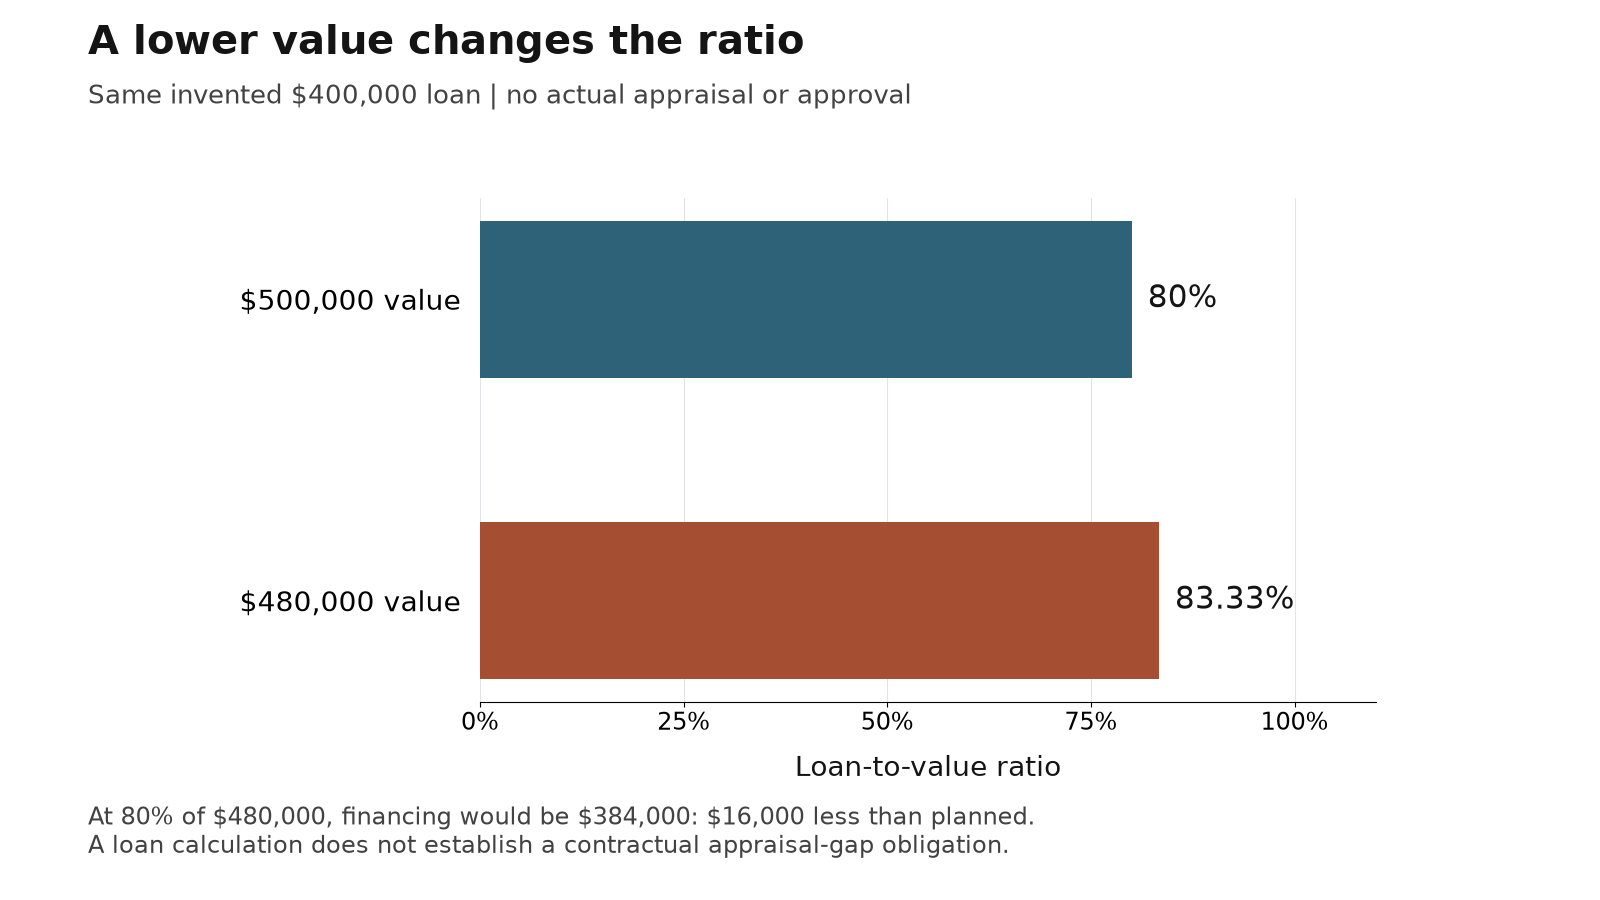
For illustration, a $400,000 loan divided by a $500,000 value is 80%; the same loan divided by $480,000 is 83.33%. If the lender instead caps the loan at 80% of $480,000, that loan is $384,000, leaving $16,000 less financing than planned. This calculation does not establish a contractual appraisal-gap obligation. Review both the lender’s conditions and the agreement’s appraisal language with the appraisal guide beside them.
What do points, mortgage insurance and loan labels mean?
Discount points exchange an upfront charge for a rate reduction under the lender’s offer. According to the CFPB’s points and credits explanation, one point equals 1% of the loan amount; it does not guarantee a one-percentage-point rate reduction. Lender credits often exchange a higher rate for lower upfront costs, although credits can have other purposes. A rate lock is an agreement with specified terms and an expiration; ask about extension costs and what changes can affect it.
PMI is private mortgage insurance associated with certain conventional loans. MIP refers to FHA mortgage insurance. The two have different rules. According to the CFPB’s PMI guidance, reviewed in August 2026, covered borrowers may request cancellation at 80% of original value subject to conditions; scheduled 78% termination generally requires current payments. “I have 20% equity” is not a universal automatic-cancellation instruction. Ask the servicer which rule applies to your loan.
Conforming concerns eligibility for the relevant agency loan framework, including applicable limits; jumbo generally describes a balance above the conforming limit. Qualified Mortgage, or QM, concerns a regulatory category with specific requirements. The CFPB’s QM explanation makes clear that loan features, pricing and repayment assessment matter. Non-QM and portfolio are not synonyms: the former concerns qualification under that framework, while the latter concerns how a lender holds the loan. Neither label substitutes for reading the actual terms.
LLPA means loan-level price adjustment, a pricing input rather than a universal consumer rate quote. Temporary buydown describes a temporary payment subsidy arrangement; a permanent rate reduction is different. Ask which payment is used for qualification, who funds the subsidy, and what happens if the loan ends early. In every comparison, preserve enough cash for the household after paying any upfront charge.
What do refinance, recast, assumption and Tidewater describe?
Refinance replaces an existing mortgage with a new loan. Recast, in the principal-reduction context, means recalculating the scheduled payment after a substantial principal payment under the servicer’s requirements. According to Fannie Mae’s servicing guidance, re-amortization after a substantial principal curtailment has a defined documentation process. Do not assume sending extra principal automatically lowers the required monthly payment, or that every loan offers the same recast terms.
Assumption means taking over an existing mortgage through the applicable approval process. It is different from informally making payments on someone else’s loan. Ask the servicer about eligibility, remaining balance, remaining term, required cash and the seller’s release from liability. A low existing rate does not resolve the difference between the purchase price and the balance being assumed. Our assumable-loan guide provides a separate framework for that decision; obtain the actual loan documents and current servicer requirements.
Tidewater is a VA appraisal procedure for submitting additional sales evidence before an anticipated below-price appraisal is finalized. The VA’s published explanation describes two business days for additional sales data. That is different from promising a flat 48-hour window. Notice of Value, or NOV, and reconsideration of value concern later appraisal review steps. None guarantees a higher valuation.
These terms describe different problems. Recasting addresses a payment after principal reduction; refinancing changes the debt contract; assumption concerns transfer of an existing debt; appraisal review concerns support for a value. Before choosing a solution, name the actual issue. Is the buyer short of cash, unable to qualify, disputing comparable sales, or trying to reduce a payment after another home sells? Request the relevant numbers and conditions for that issue rather than treating a familiar acronym as a complete strategy.
What do SRPD and as-is mean for property condition?
SRPD is the Seller’s Real Property Disclosure. According to NRS 113.130–113.150, the covered seller generally completes and serves the disclosure at least 10 days before conveyance, with specified exceptions and rules for newly discovered or worsening defects. The statute also explains that the disclosure is not a warranty and does not replace the buyer’s reasonable care. An exempt transaction needs its own analysis; “every seller always uses this form” is too broad.
Inspection is an examination within an agreed scope, while appraisal addresses value and applicable lender requirements. Permit history concerns approval records; warranty concerns specified coverage and conditions. A favorable answer in one category does not establish the others. A renovated bathroom can look sound while its permit history remains unresolved, and an appraisal may not answer a buyer’s maintenance questions.
Read the disclosure beside the inspection findings, invoices and available repair records. For each issue, identify what was observed, who evaluated it, whether the cause was resolved and what remains uncertain. Ask about inaccessible areas and specialist recommendations before the relevant deadlines expire. Repair request is a proposed negotiation, not proof the seller has agreed. Repair amendment records the accepted work or credit and should identify how completion will be demonstrated.
As-is should lead you back to the contract’s condition and repair provisions. It is not a substitute for considering statutory duties or investigating the property. Remedies and cancellation procedures can require specific notices; do not infer them from a short definition. The home-inspection checklist can organize practical questions, while a Nevada attorney can interpret disputed rights. Keep the actual dates and delivery records. The useful outcome is a documented decision about condition, price and remaining risk before commitment, rather than simply collecting a signed disclosure form.
How do HOA, CIC, resale-package and reserve terms differ?
HOA commonly refers to the association; CIC means common-interest community. CC&Rs are the recorded covenants, conditions and restrictions. Bylaws govern association organization, and rules address additional operating requirements within their authority. Regular assessment funds association obligations. A special assessment is a separate association charge under the applicable documents and procedures; it is not automatically the same thing as a government improvement-district assessment.
According to NRS 116.4109, a covered resale package includes specified governing documents, financial and assessment information, legal-action information and insurance evidence. The purchaser generally may cancel by written notice through midnight of the fifth calendar day following receipt. The statute specifies delivery methods and limits the right after accepting conveyance. Exceptions apply, including transactions requiring a public offering statement. Keep a receipt record and have the applicable deadline confirmed for your transaction.
Reserve study examines future major-component needs and funding assumptions. Reserve balance is the money currently held; operating budget concerns ongoing expenses. A large balance alone does not establish that planned replacements are adequately funded. Read the component schedule, projected costs, funding plan and recent board materials together. Ask whether an announced assessment is already adopted, merely proposed or associated with an unresolved project.
For a buyer planning a particular use, compare the written restrictions with that use: parking an RV, leasing the home, modifying landscaping or constructing an addition. Ask for the approval process before treating a seller’s past practice as permission. Identify any master association and subassociation separately so their charges and obligations do not collapse into one misleading monthly number. The SID/LID comparison guide helps distinguish public assessments from association obligations. Request property-specific statements rather than applying a generic fee range to a community name.
Which Nevada tax and assessment terms change the bill?
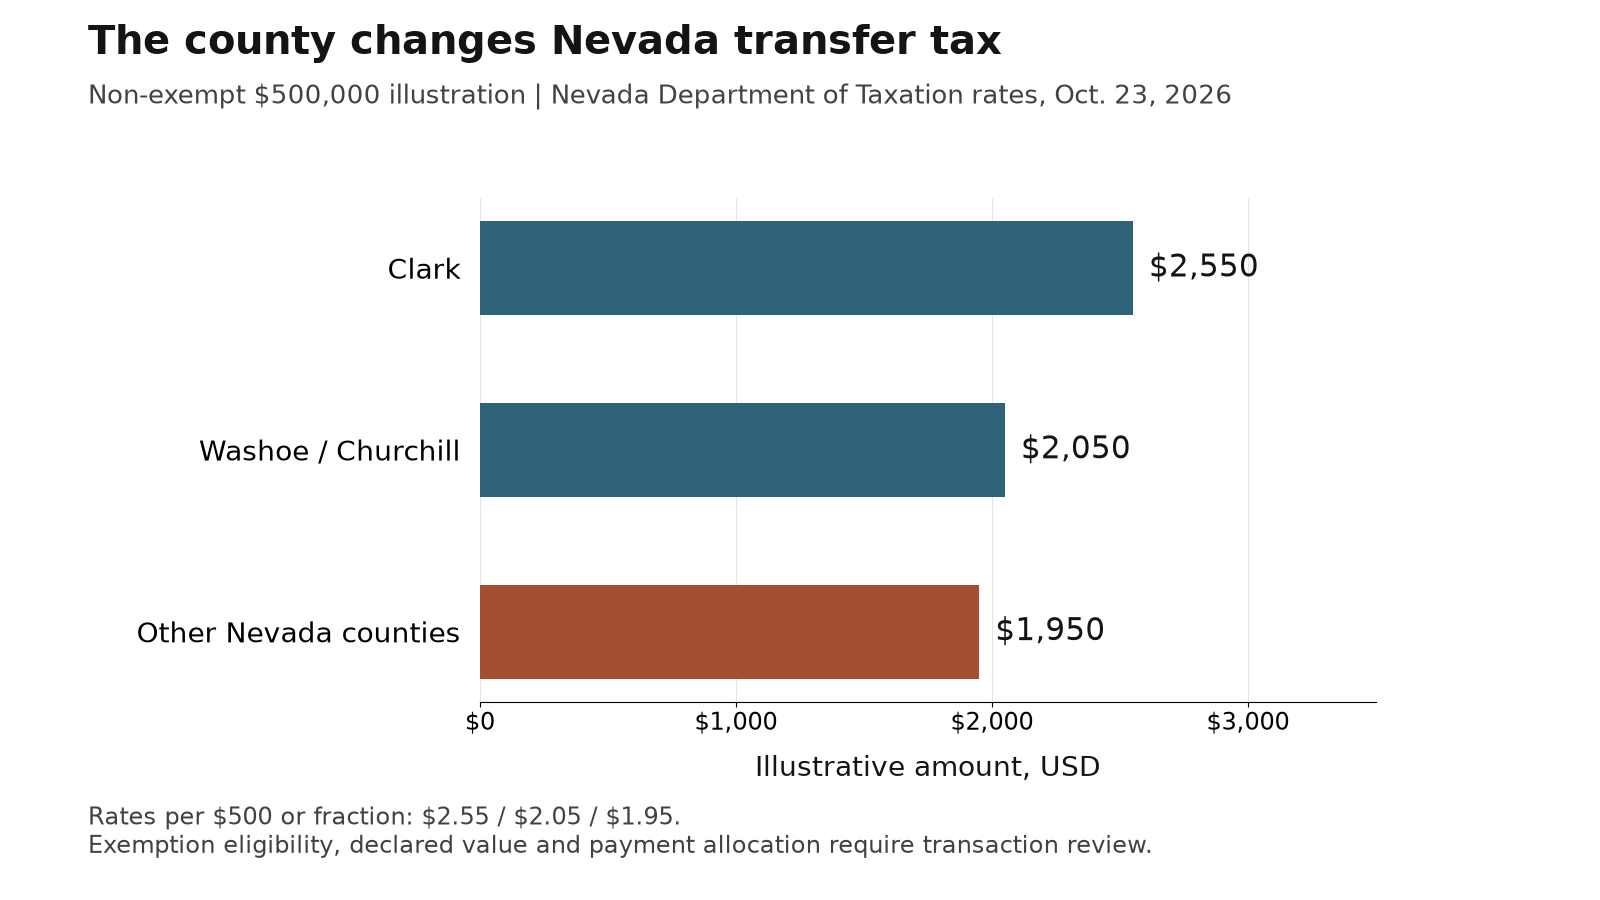
Real property transfer tax, or RPTT, is a transfer-related tax collected through recording. According to the Nevada Department of Taxation, the base rate is $1.95 per $500 of value or fraction thereof, with an additional $0.10 in Washoe and Churchill and $0.60 in Clark. Exemptions and the correct declared value require transaction-specific review. Do not infer who pays from the rate; confirm the contract’s allocation.
| County | Rate per $500 | Illustrated tax |
|---|---|---|
| Clark | $2.55 | $2,550 |
| Washoe or Churchill | $2.05 | $2,050 |
| Other Nevada counties | $1.95 | $1,950 |
Property-tax abatement concerns limits on annual tax-bill increases, not a tax rate equal to 3% of the sale price. The Clark County Assessor’s explanation distinguishes qualifying primary residences and certain qualifying rentals from the general cap of up to 8%, and explains new-construction and ownership-document issues. After a recorded ownership change, confirm the required primary-residence paperwork. Ask the assessor for the parcel’s actual classification and calculation rather than multiplying a new purchase price by a remembered cap.
SID or LID refers to a special or local improvement district context. According to the Clark County Treasurer’s SID explanation, a special assessment funds benefiting improvements, is a property lien until paid, and is billed separately from ordinary property tax. Obtain the current balance, installment amount, due dates and payoff terms. A monthly equivalent may help budgeting but does not change a semiannual bill into monthly installments.
Keep four different lines visible: transfer tax at closing, recurring property tax, association assessments and any public improvement assessment. The Nevada transfer-tax guide can help frame a closing estimate. A buyer comparing Reno, Las Vegas and another county should apply the correct county rules to the actual parcel rather than use a statewide average bill.
How do title, vesting, homestead and a deed upon death differ?
Title concerns legal ownership and interests; deed is the instrument used to convey an interest. Vesting describes how ownership is held. Lien is a claim securing an obligation; easement concerns a specified right involving property. A preliminary title report identifies matters for title review and proposed coverage, not a guarantee that every physical or use issue has been resolved. Ask for the referenced documents and identify any exception that affects your intended use.
According to the CFPB’s title-insurance explanation, a lender’s policy protects the lender’s interest, while an owner’s policy protects the buyer’s interest within its coverage. Request an explanation of exclusions, exceptions and proposed endorsements. Do not assume paying a lender-policy charge buys you the same protection as an owner’s policy. The title-insurance guide can organize questions for the title professional.
CPWROS means community property with right of survivorship. NRS 111.064 requires the survivorship feature to be expressly declared in the instrument. Deed upon death, often called a TOD deed, is governed by Nevada’s Uniform Real Property Transfer on Death Act. Relevant NRS 111 provisions address creation, recording before death, lifetime ownership and later liabilities. It is not a universal replacement for a complete estate plan or a promise that beneficiaries face no claims.
Homestead declaration concerns a particular creditor-protection framework. NRS 115.010–115.020, checked October 23, 2026, generally specifies protection up to $605,000 of qualifying equity with significant exceptions, including specified mortgage, tax and other obligations. It does not erase debt or automatically establish tax-abatement eligibility. Review ownership, succession, creditor protection and tax consequences as separate questions with qualified advisers before signing a new deed.
What do condo, PUD, GLA and builder labels actually establish?
Condominium describes a legal ownership structure; townhome often describes a building form. PUD, or planned unit development, has a financing definition that cannot be inferred from architecture or zoning alone. According to Fannie Mae’s PUD requirements, updated August 2026, association membership, assessments, common property and legal creation matter. Lenders still must determine applicable eligibility, and a condominium within a larger PUD remains subject to condominium requirements. “PUD means no project review” is not a reliable financing rule.
Warrantable is shorthand used in lending discussions about meeting a particular investor’s project requirements. Ask which program, which review and which unresolved item the lender means. It is not a universal label guaranteeing approval for every buyer. GLA, or gross living area, is a measurement term used in appraisal reporting. Ask how the appraiser measured and classified the space, particularly additions, below-grade areas or converted garages; a listing’s total does not settle the issue.
Casita and ADU should prompt questions about permitted use, facilities, access and approval records. A marketing name does not establish that a separate rental is allowed. Guard-gated and gated describe access arrangements whose actual staffing and procedures need confirmation; neither is a crime guarantee. For particular communities in Henderson or Sparks, evaluate the property and documents instead of relying on the label.
In builder paperwork, base price precedes separately priced selections; lot premium is a site-specific charge; options and allowances need precise descriptions. Spec home describes inventory built without an earlier individual buyer’s full selection process, but does not prove completion or availability. To-be-built, substantial completion, punch list and warranty refer to different construction or contract stages. Ask for the actual completion evidence, deposit terms, included features and warranty conditions. No generic incentive range or inspection anniversary replaces the builder’s signed documents and applicable rights.
Which investment terms need a formula and a defined scope?
Gross rental yield compares annual gross rent with a chosen property cost or value. Net operating income, or NOI, subtracts identified operating expenses before financing and income taxes. Capitalization rate, or cap rate, divides NOI by the selected purchase price or value. Cash-on-cash return compares a defined annual cash-flow measure with the cash invested. The inputs and exclusions matter as much as the label. Ask whether vacancy, management, repairs and replacement reserves are treated consistently in two competing worksheets.
An invented October 23, 2026 comparison makes the distinction visible: $30,000 annual rent on a $500,000 price gives 6% gross yield. If assumed operating expenses are $12,000, NOI is $18,000 and the indicated cap rate is 3.6%. If annual debt service is $20,000, the cash flow before other omitted items is negative $2,000. A positive gross yield therefore does not establish positive cash flow. These are teaching inputs, not Las Vegas or Reno rent estimates.
DSCR, or debt-service coverage ratio, compares a defined income measure with debt service. Lenders can use specific qualifying calculations; obtain that definition before applying a threshold to your worksheet. STR means short-term rental, but permitted use depends on jurisdiction and applicable private restrictions. A property marketed as an investment is not evidence of a rental license.
Section 1031 exchange concerns eligible business or investment real property, not a blanket tax-free sale. The IRS Form 8824 instructions explain the general 45-day identification deadline and receipt by the earlier of 180 days or the applicable return due date, including extensions. The IRS exchange FAQ explains actual or constructive receipt and available safe harbors. Depreciation and basis affect tax calculations; an exchange or later conversion to personal use does not automatically erase those consequences. Have the tax adviser and exchange professional assess the structure before funds are released.
How do you turn unfamiliar terms into a practical checklist?
Pair each term with a document, a responsible person and a decision. NRED is the Nevada Real Estate Division; NRS means Nevada Revised Statutes. An association acronym, MLS name or agency label tells you where to investigate, not whether a particular assertion is correct. County assessors, treasurers and recorders have different roles. Match the question to the correct office and retain the parcel identifier so information from a similarly named property is not substituted.
According to the Nevada Real Estate Division’s Duties Owed bulletin, Form 525 discloses licensee duties and does not create an agency relationship. Representation must be separately confirmed, and representing both parties requires the applicable consent. A signed disclosure is therefore not the whole answer to who represents you, what services are agreed or how compensation works. Read it with the actual brokerage agreement and related documents.
| Term or question | Evidence to request | Person to clarify it |
|---|---|---|
| Contingency and deposit | Signed contract, amendments and delivery records | Agent; attorney for disputed interpretation |
| Loan approval and payment | Written conditions, disclosures and lock terms | Lender or servicer |
| Title and possession | Title documents, escrow instructions and contract | Title/escrow professional and agent |
| Association or SID balance | Property-specific current statements | Association or administering public office |
| Vesting and succession | Existing deed and proposed estate documents | Nevada attorney and tax adviser as appropriate |
For every answer, write down the date, whether it is final and what could change it. Separate a quoted charge from an estimate, a planned repair from completed work and a proposed amendment from a signed agreement. The CFPB’s closing-fraud guidance recommends confirming wire instructions with trusted representatives using previously established contact information. An unexpected change deserves direct confirmation before funds move. Do not use an email’s new phone number as its own proof.
Bring the unresolved items to the buyer team or seller team with the relevant documents. Our experience includes 9,600+ closing tables. A useful conversation identifies the next decision and the evidence needed for it, rather than promising that every situation has the same answer. Call (702) 637-1759 in Southern Nevada or (775) 277-2120 in Northern Nevada.
Nevada Real Estate Group · 8945 W Russell Rd, Suite 170 · Las Vegas, NV 89148 · (702) 637-1759 · NV License S.181401
Frequently Asked Questions
Is earnest money an extra charge on top of my down payment?
It is a deposit paid under the purchase agreement and is generally accounted for in the settlement reconciliation. In the invented example above, the $10,000 already paid reduces the additional cash needed at closing; it is not charged twice. Refund rights, deadlines and the recipient depend on the contract and applicable law. Ask escrow to show the credit on your actual statement.
Does signing closing documents mean I can move in?
Not necessarily. Signing, funding, recording and possession are distinct events. Read the contract’s possession provision and obtain confirmation from the responsible closing professionals before scheduling occupancy. A seller rent-back or other agreed occupancy arrangement may affect when keys and possession transfer. A glossary cannot confirm that your specific transaction has closed.
What is the five-day HOA resale-package right?
For a resale covered by NRS 116.4109, the purchaser generally may cancel by written notice until midnight of the fifth calendar day following receipt of the resale package, subject to the statute’s scope, delivery methods and conveyance limitation. It is a calendar-day rule, not a generic five-business-day inspection period. Confirm applicability and document receipt immediately.
Does the Duties Owed form hire my agent?
No. NRED explains that Form 525 discloses duties and does not create an agency relationship. Review the separate representation confirmation, brokerage agreement and any required consent. Ask who represents each party and what services and compensation the actual agreement establishes. Do not infer those answers solely from a friendly conversation or a signed disclosure.
Are SID payments the same as HOA dues or property taxes?
No. They concern different obligations. Clark County explains that SID assessments fund benefiting improvements and are billed separately from ordinary property taxes. An HOA can also have regular and special assessments. Obtain a separate current balance and billing schedule for each applicable obligation, and check whether any amount is being paid off or allocated at closing.
Is mortgage insurance automatically removed when I reach 20% equity?
Not universally. For covered conventional PMI, the CFPB distinguishes a conditional cancellation request at 80% of original value from scheduled 78% termination, generally when payments are current. Appreciation, junior liens, payment history and loan type can matter. FHA insurance follows different rules. Request the applicable written cancellation requirements from your servicer.
Does a PUD or townhome avoid condominium financing review?
A building’s appearance does not determine its legal structure or loan eligibility. Fannie Mae’s PUD requirements still require applicable lender review, and a condominium inside a larger PUD remains subject to condominium requirements. Ask the lender to identify the ownership classification, program, review method and outstanding project conditions before relying on a financing estimate.
Does a homestead declaration also handle inheritance and my tax cap?
No. Homestead protection, property-tax abatement and transfer at death are separate matters. A homestead declaration has statutory limits and exceptions. A deed upon death has execution, recording and later-administration requirements, while primary-residence tax treatment has its own eligibility and paperwork. Have the relevant professionals review the documents together without treating one filing as a substitute for the others.
Which sources and methods support this glossary?
Rules were reviewed October 23, 2026 against the linked Nevada statutes, Nevada Real Estate Division bulletin, Nevada Division of Mortgage Lending explanation, Nevada Department of Taxation and Clark County pages. CFPB materials support the specific loan-disclosure, insurance, points and ratio distinctions; Fannie Mae supports the identified PUD and re-amortization rules; the VA bulletin explains Tidewater; IRS instructions and FAQs support the exchange discussion. The association discussion uses the official NRS 116 text reviewed for the cited sections.
The four charts and settlement, loan-ratio and rental calculations are original arithmetic with disclosed inputs. They are not market samples, lender quotes, client outcomes or predictions. Existing company figures remain separate from the source-based definitions. No property file, legal dispute, loan application or tax return was reviewed for the examples. Use this reference to prepare questions; the applicable documents, current rules and your facts determine the answer for an actual transaction.