The median home price can help orient a Las Vegas search, but it does not identify one standard house. Property type, condition, location, financing and ongoing obligations determine what a particular budget delivers. Begin with the right market definition, then compare actual candidates using the same questions. A larger house, a newer house and a more convenient house can each be the better choice for different needs.
Las Vegas REALTORS’ September 2026 release reports a $470,000 median for existing single-family homes sold through its Southern Nevada MLS. That regional figure does not guarantee a bedroom count, home size or neighborhood. This guide uses $375,000, $475,000 and $575,000 as chosen shopping examples. Compare actual properties, their full ownership costs and current financing before deciding what your budget buys; the median alone cannot make that decision.
- Keep a regional sold median separate from a city-filtered report, an asking price and an individual valuation.
- The $475,000 case is a chosen buyer budget, not a claim that every market measure equals that amount.
- Compare usable rooms, condition and daily travel without assuming that one area always gives more home for the money.
- Association charges, property taxes, insurance, maintenance and utilities can change the choice between similarly priced homes.
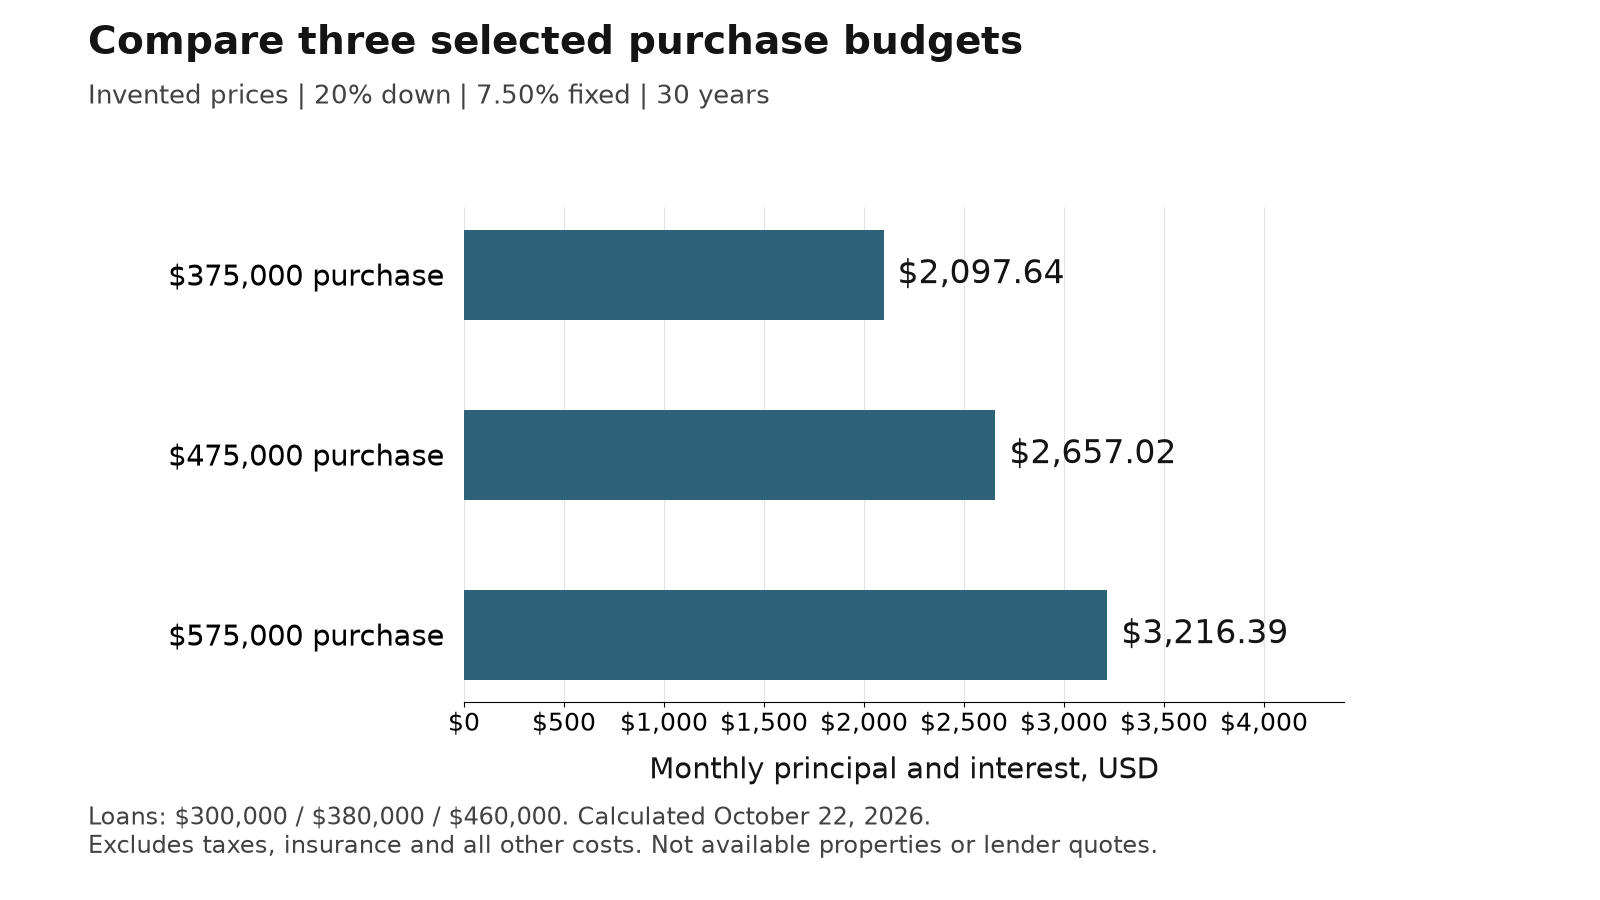
- At an assumed 7.50% fixed rate for 30 years with 20% down, a $475,000 purchase has $2,657.02 monthly principal and interest; other costs are additional.
How we know this: Across the 9,600+ closings Nevada Real Estate Group has represented statewide — more than $4.85B in closed volume — a large share sit right around the valley median, so we see what that budget buys every week. In my experience, buyers who decide their top priority first — newest, biggest, or best location — get far more for $475,000 than buyers who try to maximize all three at once. Public market measures and hypothetical calculations below are identified separately; they are not presented as an analysis of those company transactions.
Which Las Vegas Median Should You Use?
According to Las Vegas REALTORS’ September release, published on Nevada Business’s press-release wire, existing single-family homes sold through its Southern Nevada MLS had a $470,000 median, while condos and townhomes had a $290,000 median. The release describes MLS activity and notes that it does not include all builder-direct and owner-direct sales. Those are important limits when you compare resale with a new-home advertisement.
NREG’s separate Las Vegas city market report displayed an August 2026 single-family median of $485,000 across 1,023 reported sales when reviewed as of October 22, 2026. It is an affiliated published summary using a different period and city filter. It is not a contradictory estimate of the same September regional group, and subtracting the two medians would not measure a monthly change.
| Measure | Period and scope | Reported median |
|---|---|---|
| LVR existing single-family sales | September 2026; Southern Nevada MLS | $470,000 |
| LVR condo and townhome sales | September 2026; Southern Nevada MLS | $290,000 |
| NREG published city-filtered sales | August 2026; Las Vegas single-family selection | $485,000 |
We've represented buyers at this exact price point across every corner of the valley, so treat the median as a starting budget, not a house. The selected $475,000 example helps compare financing and property choices; it does not replace either source’s date or definition. For an offer, request comparable closed sales relevant to the actual home and review the differences that could justify a different price. A citywide or regional midpoint is too broad to establish a property’s condition-adjusted value.
How Do You Turn a Price Ceiling into a Useful Search?
Write down what the house must do before deciding where a headline budget supposedly buys the most. Essential requirements might include a specific room arrangement, enough parking, a manageable work trip or a maximum monthly payment. Separate those requirements from preferences you can change later. A search becomes clearer when you know which feature you are unwilling to sacrifice.
At the three example budgets, do not assume a standard ladder of bedrooms or square feet. A $375,000 candidate might have different association obligations from a $475,000 candidate. A $575,000 asking price might reflect a larger lot or updated finishes rather than extra usable space. It might also be an asking price that needs stronger supporting evidence. Compare what is actually offered instead of treating price as a complete specification.
Use a short candidate sheet: address and jurisdiction, property type, essential rooms, significant condition questions, property charges, financing estimate, travel needs and cash remaining. Mark unknowns clearly. If you need to guess at several material expenses to make the home look affordable, it is too early to call it a good fit.
Start with the Las Vegas, Henderson and North Las Vegas hubs when those locations match your needs. The hubs help identify alternatives; they do not prove that any one city offers the best value. The buyer resources cover the overall process. This guide’s narrower job is to help you explain why one candidate meets your priorities better, using current property evidence and a budget that includes the obligations after closing.
Why Do the Property’s Jurisdiction and Daily Destinations Matter?
A broad “Las Vegas” description is not enough to identify the government rules or the travel routine that applies to an address. According to Clark County’s planning guidance, county and incorporated-city jurisdictions have different development rules, and its mapping resources and planning staff can help identify a property’s jurisdiction. Confirm that information before relying on a generic neighborhood description for a proposed project.
Then map the destinations you actually use. Someone working on a particular shift may value a different route from someone working at home. The relevant comparison includes the time of day, parking, required stops and the reliability your schedule needs. This article does not promise that every newer suburb has a longer commute or that every central location works better for every job.
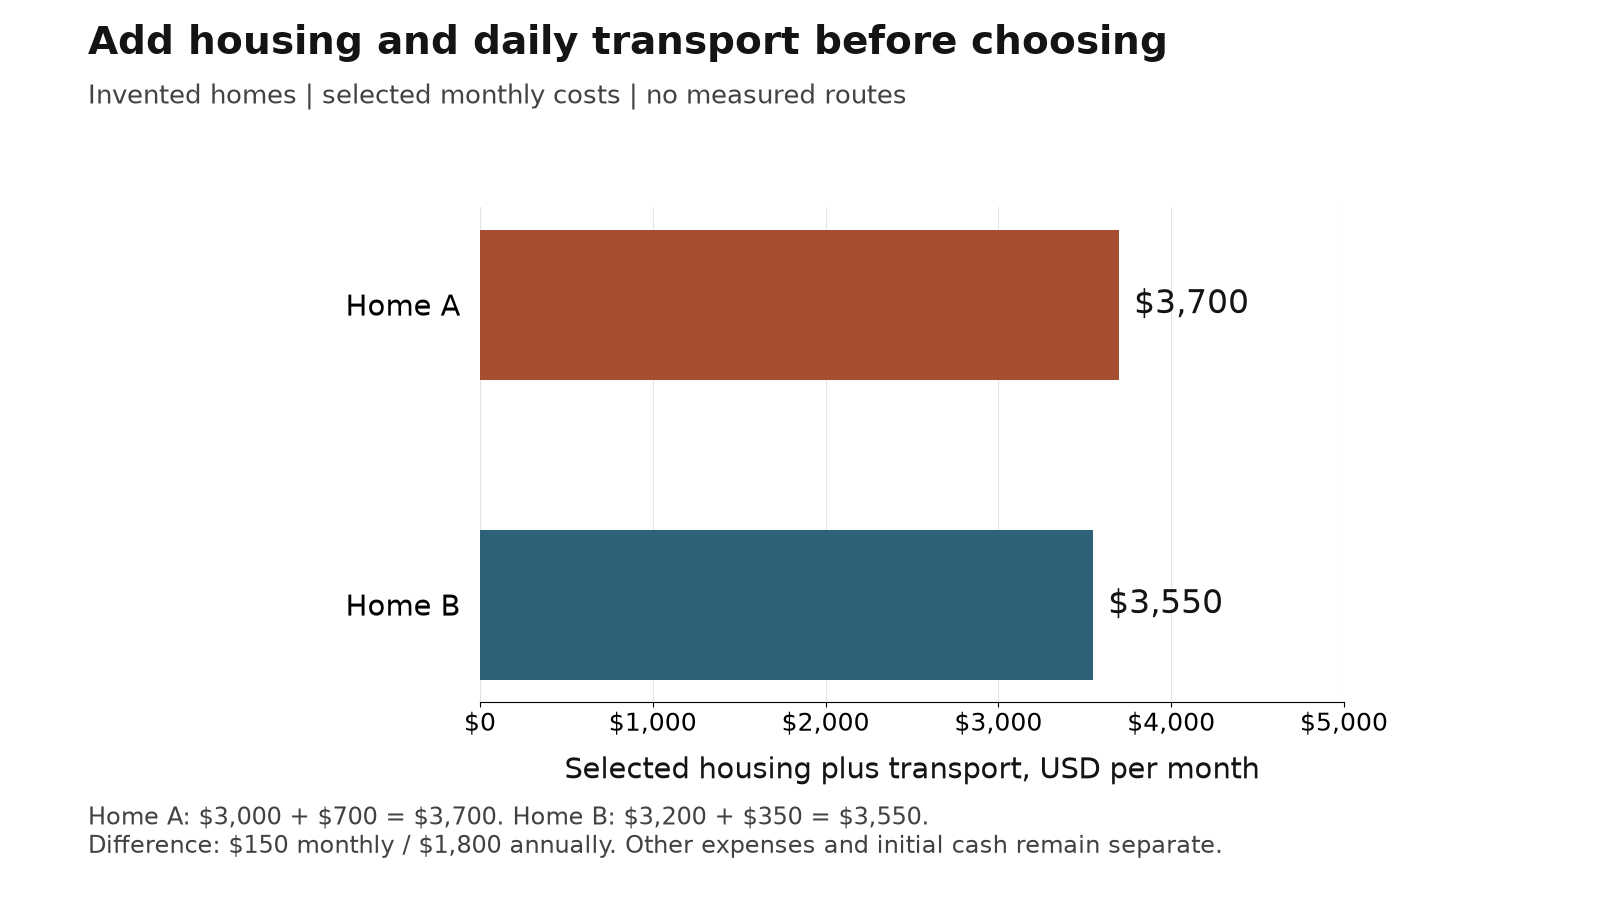
Consider a deliberately simple example as of October 22, 2026. Home A has an assumed $3,000 monthly housing subtotal and $700 in transport spending. Home B has a $3,200 housing subtotal and $350 in transport. The selected totals are $3,700 and $3,550, respectively. Home B leaves $150 more monthly, or $1,800 annually, despite the higher housing line. Those are invented costs, not measured routes or actual properties.
Time and personal preferences still matter even if the dollar totals are equal. Test your normal routine from serious candidates and record the circumstances. If a particular school is essential, confirm the address and applicable school year directly with the district; a community marketing label is not a school assignment or a quality guarantee. This makes the location choice specific to the household without ranking communities by vague prestige.
What Should You Compare in Newer Suburbs and Established Areas?
Use age and location to generate questions, not to predetermine the answer. For a newer house, ask about the actual construction, installation quality, warranties and what was included in the purchase. For an established house, investigate the systems, previous repairs, additions and maintenance records. A recent year built is not a substitute for an inspection, and an older year does not establish poor condition.
I steer value-focused buyers here when they are comfortable trading dated finishes for space and location, and are willing to budget for updates over time. For established homes, start with a workable renovation plan. Determine which improvements are cosmetic, which affect basic usability and which require permits or specialist work. Get relevant estimates before assigning the house a bargain label.
Tour with the same checklist in each area. Record the layout’s usefulness, outdoor space, parking, storage and maintenance responsibilities. If a house has an addition or converted room, ask how it appears in the records supporting the listing and whether it suits your intended use. Do not pay for a presumed feature solely because the total room count looks attractive.
Compare Spring Valley, Rhodes Ranch or other suitable areas as actual alternatives rather than automatic winners at a fixed budget. Conditions and available properties differ within each place. The search should also leave room for an address outside an initially favored label if it meets the same needs and passes the same review. A useful comparison explains the compromises; it does not promise a universal exchange rate between distance, age and square footage.
How Do You Evaluate a Smaller Home in a Master-Planned Community?
An attached or smaller home can be a sensible choice when its layout and location fit. It can also carry obligations that change the cost comparison. Ask which components the owner maintains, which the association maintains, what services the dues include and what restrictions affect the way you intend to use the property. Compare actual documents for the specific association rather than assuming one community name describes every home’s obligations.
In Summerlin or Green Valley, begin with current candidates and their property types. Do not assume that $475,000 necessarily buys only a condo or that a particular area guarantees better resale results. A home’s value still depends on the individual property, the relevant market and future conditions that no guide can guarantee.
For attached housing, investigate the building and shared responsibilities as well as the interior. Ask the lender about the property’s eligibility for the intended financing and request the information needed to evaluate association finances, insurance and planned work. A renovated kitchen cannot answer questions about common elements or the household’s exposure to future charges.
If your choice has narrowed to two named master plans, the Summerlin versus Inspirada comparison is a separate, dated starting point. Its published measurements have their own periods and assumptions; do not carry an old fee or listing snapshot into a new offer without checking it. This median-budget guide asks a broader question: how much of the price and monthly payment buys something you will actually use, and which obligations remain after the attractive features have been counted?
What Do $375,000, $475,000 and $575,000 Mean for Financing?
According to Freddie Mac’s Primary Mortgage Market Survey, the national 30-year fixed average released October 22, 2026 was 7.32%. A national survey is context, not a personal quote. The calculations below use a separate 7.50% fixed rate, 30-year term and 20% down payment to make the comparison consistent. No actual property or financing offer is represented.
| Input or result | $375,000 purchase | $475,000 purchase | $575,000 purchase |
|---|---|---|---|
| 20% down payment | $75,000 | $95,000 | $115,000 |
| Loan amount | $300,000 | $380,000 | $460,000 |
| Fixed rate and term | 7.50%; 30 years | 7.50%; 30 years | 7.50%; 30 years |
| Monthly principal and interest | $2,097.64 | $2,657.02 | $3,216.39 |
The examples show what borrowing different amounts does under identical terms. They do not include property taxes, insurance, association charges, utilities, maintenance or other transaction costs. Those omitted expenses can change which home is affordable, and they can differ even when two prices match.
For a real purchase, compare lender documents with the same price, down payment and timing. Identify any points, lender charges, credits and lock conditions. A low payment attached to a different term or an initial incentive is not directly comparable without those differences. If you change the price or financing while negotiating, update the calculation rather than carrying an earlier estimate forward. The purpose of this table is to make the inputs visible so you can replace them with verified terms.
How Much Does the Interest Rate Change the Same Budget?
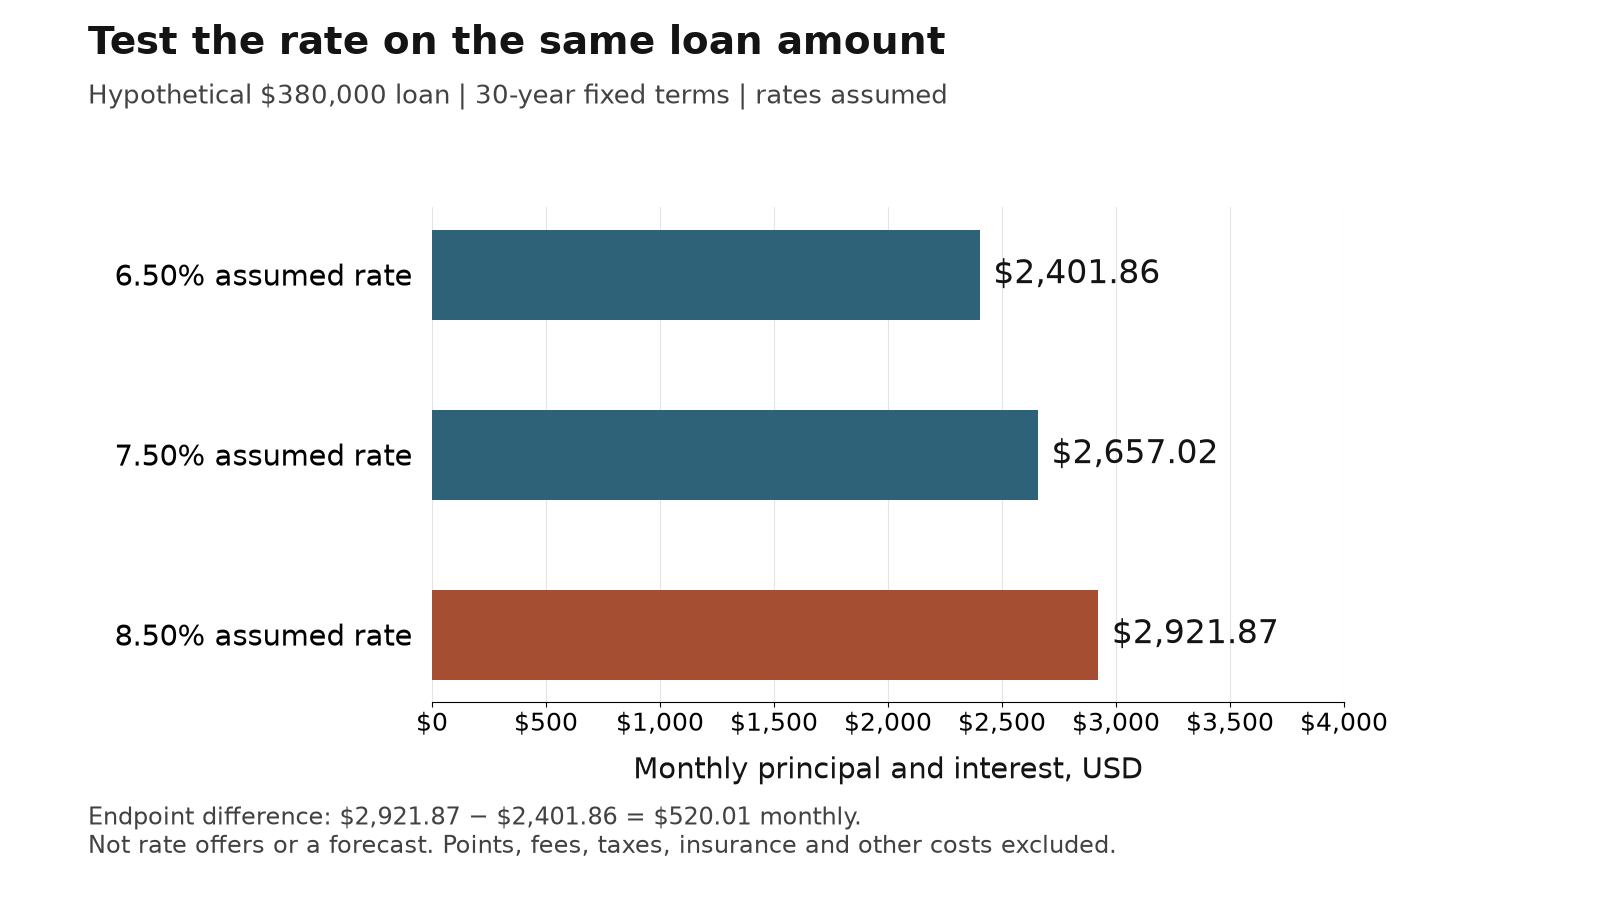
Hold the example purchase at $475,000, the down payment at $95,000 and the loan at $380,000 for 30 years. At an assumed 6.50% fixed rate, monthly principal and interest are $2,401.86. At 7.50%, they are $2,657.02. At 8.50%, they are $2,921.87. The gap between the two endpoint examples is $520.01 monthly.
These are sensitivity calculations as of October 22, 2026, not a prediction that any of those rates will be available when you buy. They also do not incorporate points, closing costs or borrower qualifications. A rate comparison becomes useful only when you understand the cash and conditions needed to obtain each offer.
According to the Consumer Financial Protection Bureau’s Loan Estimate guide, loan terms, projected payments and closing-cost information need separate attention. Keep the rate and the cost to obtain it together. Ask what is locked, what can change and how an initial payment reduction differs from the underlying loan terms.
Do not make a purchase affordable only by assuming a future refinance. That decision would depend on future conditions, eligibility, fees and the amount still owed. Instead, evaluate whether the proposed loan works on its current documented terms. If an alternative requires more cash at closing, compare the reserve left afterward as well as the monthly savings. This is particularly important when the property also needs work: a financing choice that uses the repair cushion can create a different problem even if the monthly payment looks better.
What Belongs in the Full Monthly Ownership Budget?
Start with the $475,000 example’s $2,657.02 principal and interest. Add invented monthly amounts of $300 property tax, $140 insurance and $80 association charges. The selected payment components total $3,177.02. Add $250 maintenance savings and $350 utilities, and the selected housing budget is $3,777.02 before transport and ordinary household spending.
These are planning inputs as of October 22, 2026, not current local averages or quotes for a house. Use actual documents and property-specific estimates before making an offer. A house with no association still needs maintenance; a house with association dues may leave substantial responsibilities with the owner. Confirm what is paid through the mortgage account and what must be paid separately to avoid omissions or double counting.
I build a full monthly-cost model for every home we seriously consider, because two homes at the same $475,000 price can carry very differently once taxes, insurance, and HOA are layered in. The illustrative figures here do not claim to summarize those existing client models. They provide a transparent structure for comparing the current candidates in your own search.
Treat known work separately from a general maintenance allowance. A roof or cooling-system issue identified before purchase needs an estimate and a timeline, not a vague promise to save later. Ask the relevant provider what the quoted insurance includes and excludes, and obtain service history where available. Once the housing budget is complete, add food, healthcare, debt payments, dependents’ needs and savings goals. The result is a household decision, not merely a lender’s payment calculation.
Why Should You Pull the Actual Property-Tax Record?
According to Clark County Assessor’s real-property explanation, taxable value is determined using prescribed valuation methods, and properties fall within different tax districts. It is not simply a universal percentage of the asking price. An existing owner’s bill can be useful evidence, but you still need to understand the property’s status and any changes relevant to the purchase.
According to the county’s tax-abatement guidance, qualifying primary residences can receive a 3% cap on the tax bill; other categories and new construction are treated differently. The page also explains that recorded ownership changes can require renewed owner-occupancy documentation. This is a cap framework, not a statement that the annual tax equals 3% of the home’s price. Confirm the parcel and required steps with the appropriate office.
The property-tax line in particular can differ between two similar homes if one sits inside a supplemental tax district, so I always pull the actual tax record rather than estimating. Keep any separately billed improvement-district obligation visible too. Ask for the current amount, payment timing, remaining obligation and relevant transaction treatment rather than assuming that an association fee includes it.
When a seller’s estimate, listing field and lender worksheet differ, reconcile the difference before selecting a budget. Identify which year and property status each figure describes. For a new home, ask what the quoted amount assumes about the completed improvements. A reliable purchase comparison documents the reason for the tax input instead of choosing the lowest number because it makes the payment fit. This guide does not calculate a specific parcel’s final tax liability.
How Do Association Dues and Special Charges Affect Value?
Compare what the charges pay for, which responsibilities remain yours and what additional obligations may arise. Request the governing documents, current budget, relevant reserve information, insurance details and known planned work for the specific property. Read them alongside the contract and obtain professional advice about any material uncertainty. The article does not supply a universal Nevada resale-package deadline or fee; those require current transaction-specific guidance.
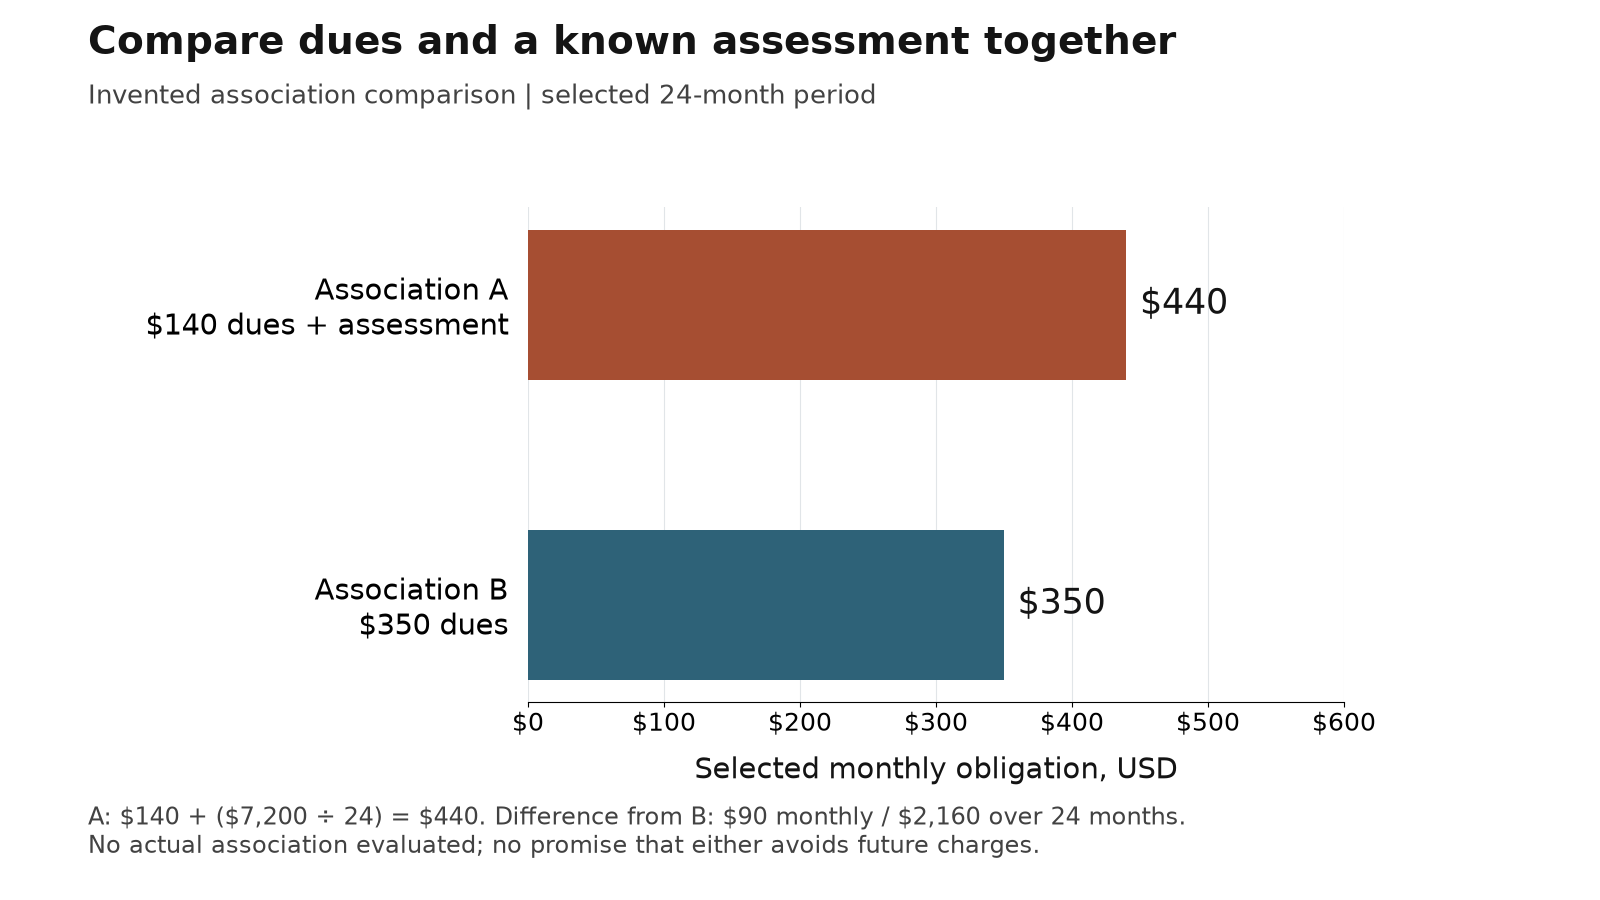
An invented comparison illustrates the cash effect. Suppose Association A charges $140 per month plus a known $7,200 assessment paid over 24 months. The selected combined obligation during those months is $440 monthly. Suppose Association B charges $350 monthly with no additional assessment included in the example. A’s selected total is $90 more monthly, even though its ordinary dues are lower. Over 24 months, the difference is $2,160.
Those assumptions, calculated as of October 22, 2026, do not predict any community’s finances or guarantee that B will avoid future charges. Actual assessments may have different payment terms, and the purchase contract may address existing obligations. Compare the documents rather than inferring risk from the dues alone.
Amenities also have personal value. A service you use frequently may justify an expense that would be unnecessary for another household. Count that value honestly without assuming that it automatically increases resale performance. For attached homes, ask about shared structures and coverage as well as recreation features. The goal is to know the obligations you are accepting and whether they fit your budget, not to label every low-dues association good or every higher-dues community expensive.
What Can a Yard, Pool or Renovation Add to the Budget?
Outdoor space is useful only if its condition, maintenance and permitted use fit the household. During the review, ask about irrigation, drainage, major equipment, access for maintenance and any existing landscape obligations. A larger lot can bring more options and more work. A pool or elaborate landscape should be evaluated as a feature with continuing costs, not as a free addition to the asking price.
According to Southern Nevada Water Authority’s landscape-planning guidance, homeowners should consider their spending limit, timeline, association requirements and future irrigation needs before planning changes. That is a useful starting point for comparing yards. It does not establish a particular property’s water bill, rebate eligibility or renovation cost.
For planned alterations, ask the appropriate jurisdiction and association about the specific work. A contractor’s estimate should identify what is included, what remains unknown and whether approvals are needed. Do not assume that an attractive project shown in another home can be replicated on the target parcel under the same conditions.
Keep three amounts separate: work required to make the property usable, optional improvements you want soon, and money retained for later uncertainty. If the first category is substantial, it can outweigh an apparent bargain in the contract price. If the second category can wait, decide whether you are comfortable living with the existing condition. No fixed renovation allowance fits every older or newer Las Vegas home. The useful comparison is a documented scope and realistic cash plan that allows the household to own the property comfortably after the initial excitement of the purchase.
How Should You Compare a Builder Offer with a Resale?
For a builder proposal, obtain the price for the actual lot and configuration, the included features, selected options, completion terms, warranty documents and any conditions attached to incentives. For resale, obtain the relevant disclosures, condition evidence, repair estimates and proposed contract terms. Compare the whole offer rather than matching a model-home image to a resale asking price.
In my experience, buyers who prioritize a move-in-ready modern home lean new, while buyers who want space and location lean resale. I've toured both sides of this trade hundreds of times, and the deciding factor is almost always which compromise you can live with daily. That experience does not establish what any builder currently offers at the illustrative $475,000 budget.
A financing incentive needs the same review as any other financing choice. Compare actual lender terms, credits, charges and the duration of any reduced payment. Ask whether the price or incentives change with a different lender or product. The new-construction hub can help identify communities to investigate, but the written current proposal is what supports a purchase comparison.
Include timing and setup costs. A completion delay or a different move-in condition can affect temporary housing, storage, landscaping or other expenses. A finished resale can still need work before it serves your household, while a new property can require items not included in the base package. Record those differences in cash and practical terms. Neither option is automatically better value because it is new or established; the decision depends on the address, the documents and the compromises you are willing to accept.
How Much Income and Initial Cash Does the Example Require?
If you choose a 30% gross-income screen for the assumed $3,177.02 selected payment, the calculation is $3,177.02 × 12 ÷ 0.30, or $127,080.80 annual gross income. That chosen rule, calculated as of October 22, 2026, is not a loan qualification standard or an estimate of the income every Las Vegas buyer needs. Approval and household comfort involve additional information.
Use take-home cash for the household comparison. With assumed monthly receipts of $8,000, the $3,777.02 selected housing budget and $3,200 of other spending leave $1,022.98. Another $600 obligation reduces that to $422.98. Missing expenses reduce it further. Use reliable income and actual obligations rather than an anticipated raise or hoped-for refinance.
| Category | Amount | What to verify |
|---|---|---|
| 20% down payment | $95,000 | Actual financing and source of funds |
| Closing and prepaid items | $13,000 | Lender and settlement documents |
| Moving and selected setup | $7,000 | Written quotes and scope |
| Retained reserves | $25,000 | Household and property needs |
| Cash accounted for | $140,000 | Known repairs are additional |
The reserve stays with the household; it is not a standard closing charge. A smaller down payment changes the loan and may change other costs, so compare actual programs instead of assuming one result. The FHA versus conventional guide provides a separate framework, but its program details and examples need their own current review before use. Keep financing approval, the monthly household budget and cash available at closing as three related checks, not one interchangeable number.
How Should Market Conditions Affect Your Offer?
A regional report can describe the market backdrop; it cannot reveal a particular seller’s priorities or the other offers on a home. Ask for relevant recent closings, listing history, condition evidence and the differences between the target and its competition. Do not apply an old universal sale-to-list percentage or a citywide days-on-market number as an automatic negotiation formula.
In my experience, buyers who are pre-approved and clear on their priorities can act within a day or two of the right home hitting the market, which is often the difference between winning and losing a median-priced house in the busy season. That observation supports preparation. It does not mean you should waive a material investigation or expect every property to follow the same timetable.
Discuss the proposed dates, contingencies and consequences with the professionals handling the transaction. Be ready to provide documents and make decisions promptly, while keeping the issues that matter to your purchase visible. A home that has been listed longer may have a price problem, a condition issue or circumstances that require further investigation; time alone does not identify a bargain.
Consider what you would do if the price remains flat or the home becomes harder to sell when you need to move. Ownership costs, transaction costs and the household’s time horizon matter alongside the purchase price. Neither a long-run regional trend nor a desirable community name guarantees appreciation. The Las Vegas investment discussion addresses a separate decision and should not be treated as a promise of returns on the home you are considering.
What Should Be on Your Final Comparison Sheet?
The most expensive mistake I see is shopping on price alone and ignoring the all-in monthly cost. Before committing, put the actual candidate’s price, financing terms, charges, condition findings, planned work and retained cash on one sheet. Label each item verified, assumed or still outstanding. A summary that hides missing information is less useful than a candid list of questions that still need answers.
Compare the daily routine too. Ask whether the house meets the non-negotiable requirements you wrote down at the start and whether you can live with the remaining compromises. More square footage does not necessarily offset a difficult schedule; newer finishes do not automatically offset a payment that consumes the reserve. The right decision should remain understandable after the tour’s first impression fades.
If you need proceeds from a current home, coordinate the timing with the seller resources and your transaction team. Include any overlap in housing, storage and moving. Do not count sale proceeds as available before the transaction actually provides them. An otherwise suitable home may require a different timetable or financing arrangement to fit the household safely.
Use $475,000 here as a chosen example, then set the search to your actual budget. As the lead agent at Nevada Real Estate Group, I do this every week for buyers at exactly this price point. Call (702) 637-1759 or contact our team to compare current candidates against the features and financial limits that matter to you. The next step is an address-specific review of what the money buys and what it leaves you responsible for afterward.
Frequently Asked Questions
What is the median Las Vegas home price in 2026?
The reviewed September LVR release reports $470,000 for existing single-family MLS sales across Southern Nevada. A report filtered to Las Vegas or to another property type can differ. Always keep the date, geographic scope and property category with the number rather than using one all-year figure.
What does $475,000 buy in Las Vegas?
It depends on the actual properties available and their condition, layout, location and obligations. The guide uses that amount as a chosen budget. It does not guarantee a certain size, bedroom count or community. Compare relevant closed sales and inspect the specific candidate before drawing a conclusion.
Does $100,000 more guarantee a bigger or better home?
No. The difference might relate to condition, lot features, location or an unsupported asking-price premium. Identify what the extra money adds for your household and compare its effect on both monthly expense and cash down. A larger price alone does not establish better value.
What is the payment on the $475,000 example?
With 20% down and an assumed $380,000 loan at 7.50% fixed for 30 years, principal and interest are $2,657.02 monthly. Property charges and other costs are additional. The broader budget in this guide uses invented allowances that must be replaced by actual documents and quotes.
Are low association dues always an advantage?
No. Compare included services, owner responsibilities, known assessments, financial information and planned work. A lower regular fee can coexist with additional obligations. The hypothetical comparison in this guide illustrates the arithmetic; it does not evaluate any actual association or guarantee future costs.
Does a 3% tax cap mean tax is 3% of the purchase price?
No. The county’s abatement guidance describes a cap framework for qualifying tax bills, with other rules and exceptions. It is not a simple tax rate applied to the asking price. Review the parcel’s records, tax district and required owner-occupancy documentation with the appropriate office.
Should I choose a new home or an established resale?
Compare the specific proposals, including included features, financing conditions, completion timing, maintenance and necessary work. A builder incentive and a lower resale price can affect different parts of the budget. Use written terms and property evidence rather than assuming either category is always cheaper.
Is buying at the median a guarantee of good resale value?
No. A median describes a reported group of transactions. It does not protect one home from price changes, condition problems or transaction costs. Choose a property that fits the household’s needs and budget without depending on guaranteed appreciation or a future refinance.
Which Sources Inform This Median-Home Guide?
Sources were reviewed as of October 22, 2026. LVR’s September press release supplies regional resale context. It appears on a press-release wire under B&P’s byline; it is attributed association material, not independent magazine analysis. NREG’s Las Vegas city report is a separate affiliated published summary with a different period and selection. Individual sale records were not recomputed for this article, and no live listing sample supports a promised home specification at any example price.
Freddie Mac PMMS supplies the dated national rate observation. The CFPB Loan Estimate guide informs the financing comparison. Mortgage payments and household worksheets are original calculations with disclosed assumptions. They are not client results, property quotes or forecasts of future borrowing terms.
Clark County’s planning FAQ, real-property explanation and abatement guidance support the jurisdiction and tax questions. SNWA landscape guidance supports planning for outdoor changes. No individual parcel, school assignment, association finances or permit outcome was verified. Current association-package rules were not inferred from an inaccessible state forms page.
The charts illustrate the disclosed examples, and the cover is conceptual. Keep dates, scope and exclusions attached when using the figures. For an actual purchase, replace the assumptions with current documents, identify the unresolved questions and compare both the immediate cash and the obligations that continue after closing.
Nevada Real Estate Group · Chris Nevada · License S.181401 · (702) 637-1759.