A Las Vegas house flip starts with a decision about one property: can its supported resale value cover the purchase, completed work, financing, ownership expenses, selling costs and a worthwhile return? A low asking price does not answer that question. Neither does a citywide median or a photograph of a remodeled kitchen. You need the actual condition, a written scope, suitable comparable sales and enough capital to finish even when the schedule changes.
This guide explains how to build that decision, with primary rules reviewed October 23, 2026 and transparent calculations. The examples are invented planning exercises, not closed deals, contractor bids, loan offers or representative Las Vegas returns. The roughly 9,600 transactions our team has closed across the valley are part of our company experience; the calculations here are not an analysis of those files.
To evaluate a Las Vegas house flip, verify comparable resale values, obtain a licensed contractor's scope, and subtract every project cost before setting your offer. The 70% rule is only a screening calculation. In this invented example, a $257,500 purchase and $475,000 resale leave $65,100 before income taxes under stated assumptions; a lower sale, extra repairs and delay can turn that into a loss.
- Use comparable completed sales and the property's intended finish to support resale value.
- Count acquisition, renovation, financing, carrying and selling costs separately.
- Test cash availability and downside outcomes before committing.
- Verify the property's permitting jurisdiction and the contractor's license.
- Check FHA resale timing and tax classification before setting an exit plan.
How do you decide whether a Las Vegas flip is worth pursuing?
Start with the finished property you can reasonably deliver and the evidence that a buyer would pay for it. Work backward to a purchase price. A listing described as an investor special is an invitation to investigate, not evidence of a discount. The seller may already have priced in an optimistic renovation outcome, while the buyer still has to fund the work and absorb the risk.
As of October 23, 2026, this guide does not establish a current median entry price, an average investor profit or a typical resale time. Those claims require a defined, dated transaction sample with clear condition and geographic filters. Comparing inexpensive fixer asking prices with the median of a different group of finished homes cannot establish the profit available on one property. Even a correctly calculated difference would omit construction and transaction costs.
Use Las Vegas fixer-upper inventory to build a candidate list, then create a separate underwriting file for each address. Save the listing details you relied on, the inspection and permit questions, the proposed work, the loan terms and the comparable properties. Record the date each input was checked so you can identify what must be refreshed before removing a contingency.
Define your stopping conditions early. A project might fail because the completed layout lacks resale support, the repair scope cannot be priced, or available cash cannot bridge construction draws. A larger theoretical profit does not cure those problems. A decision to pass can be the useful outcome of a good analysis. Compare other Las Vegas homes for sale only after accounting for their different condition, costs and intended use.
How should you estimate the property's after-repair value?
After-repair value, or ARV, is an estimate of the finished property's value at a future sale. It is not a guaranteed selling price. Describe the completed floor plan, legal living area, major systems, finishes and outdoor improvements before choosing comparables. Otherwise, the valuation may assume features your contractor's budget does not include.
According to Fannie Mae's comparable-sales guidance, appraisers consider similar physical and legal characteristics, condition and market competition. Its guidance calls for at least three closed comparables in the sales comparison approach, with applicable exceptions, and allows older or more distant evidence when appropriately explained. That is an appraisal framework, not a rule that every investor can value a property by drawing a one-mile circle.
For your own review, write down why each sale belongs in the comparison. Consider legal square footage, lot configuration, pool condition, access, traffic exposure and the actual renovation level. A renovated kitchen does not establish that the roof, sewer or HVAC systems were replaced. Listing photographs help form questions; inspection records, permits and verified sale information help answer them. Do not invent an adjustment because a feature looks expensive.
Separate closed sales from active competition. A current asking price shows what another seller wants; it does not show what a buyer paid. A pending listing may reveal competition but its final terms may be unavailable. Concessions, financing and transaction dates also matter. Keep a conservative range and explain what evidence supports its lower end.
In a location comparison, a Green Valley property should not automatically inherit the valuation of an unrelated East Las Vegas property. Use actual property and market characteristics. When the evidence is thin, acknowledge the uncertainty or obtain an independent appraisal instead of filling the gap with confidence.
What does the 70% rule tell you, and what does it miss?
The familiar calculation is 70% of ARV minus repairs. With an assumed $475,000 resale value and $75,000 repair estimate, it produces $332,500 minus $75,000, or $257,500. That arithmetic is straightforward. Whether the resulting offer makes economic sense depends on the costs and risks hidden inside the remaining margin.
The 30% allowance is not a promised profit. It has to absorb acquisition expenses, financing, carrying costs, selling expenses, repair uncertainty and compensation for your capital and work. Those items do not all move in proportion to resale value. A small project with a long permitting delay can have high financing costs. A larger project may require a different loan structure or more expensive insurance. A fixed percentage does not resolve either situation.
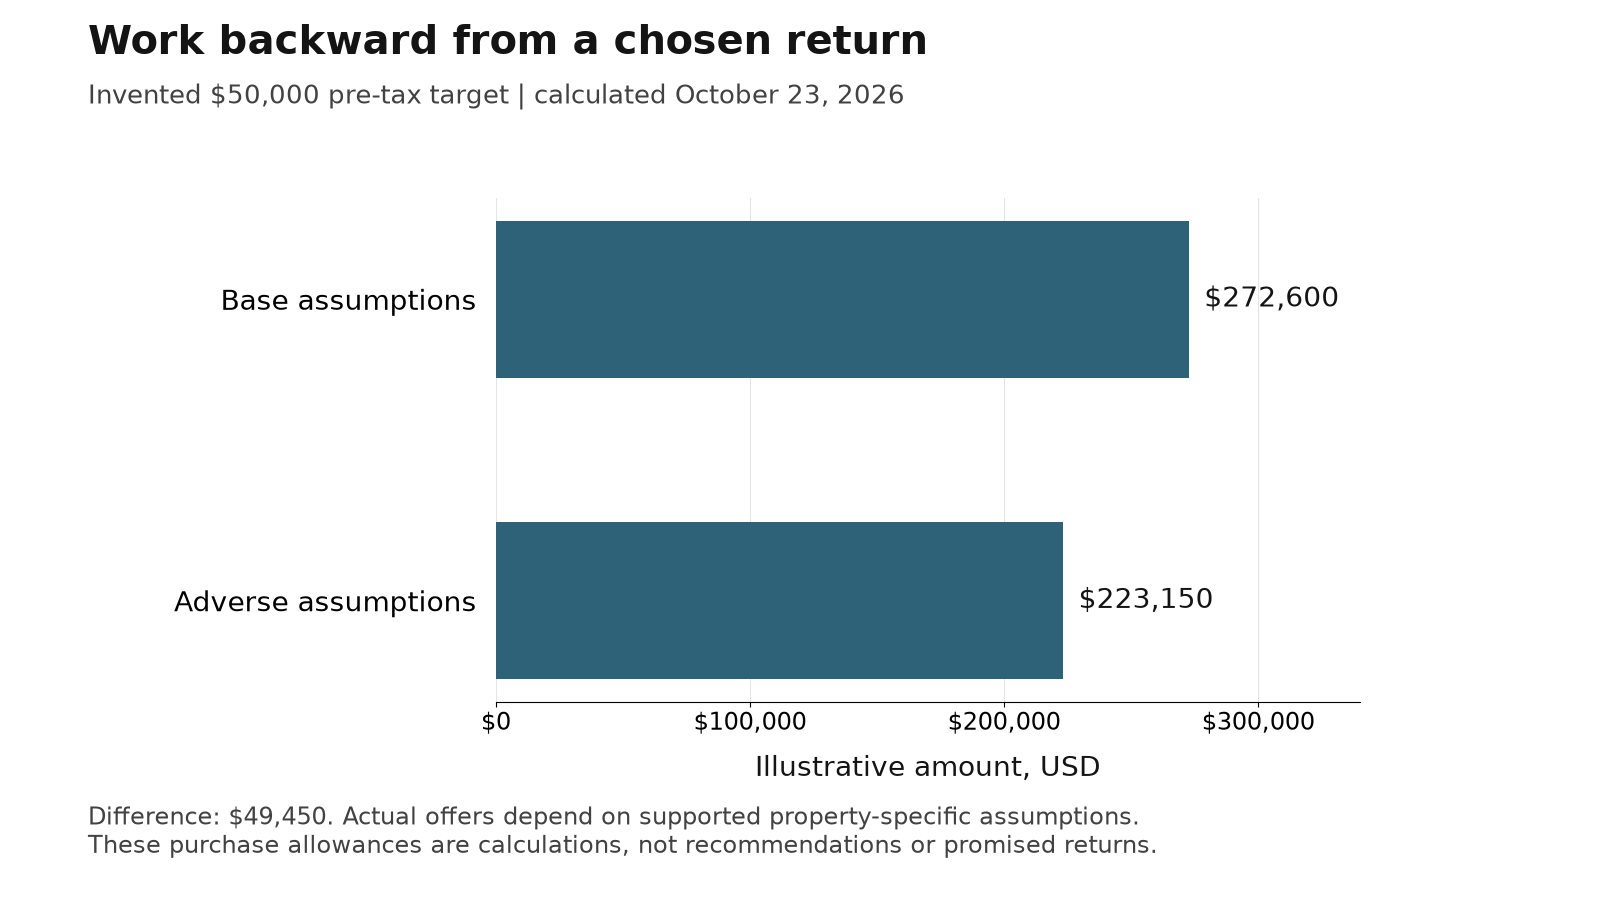
Replace the shortcut with a complete calculation before offering. In the October 23, 2026 example below, the selected costs and a $50,000 pre-tax target permit a purchase of $272,600 if every base assumption holds. Under the adverse scenario, the same target permits only $223,150. Neither is a recommended bid. They demonstrate why the acceptable price depends on your assumptions, and why a seemingly conservative percentage can still be too high for a particular project.
Keep the initial screen if it helps compare many listings, but document its limitations. Do not raise ARV to make a seller's number pass the screen or reduce a contractor allowance without changing the actual scope. The decision to buy should follow the completed analysis. The same discipline applies when comparing Henderson fixer-upper candidates or North Las Vegas fixer-upper candidates; the formula does not make their underlying markets interchangeable.
What belongs in a complete flip budget?
Use one project ledger that separates costs from loan proceeds and principal repayment. Borrowed funds are financing, not revenue. Repaying principal at resale affects the settlement cash you receive, but subtracting the original purchase price and then subtracting the entire loan principal again would count financed costs twice in the profit calculation.
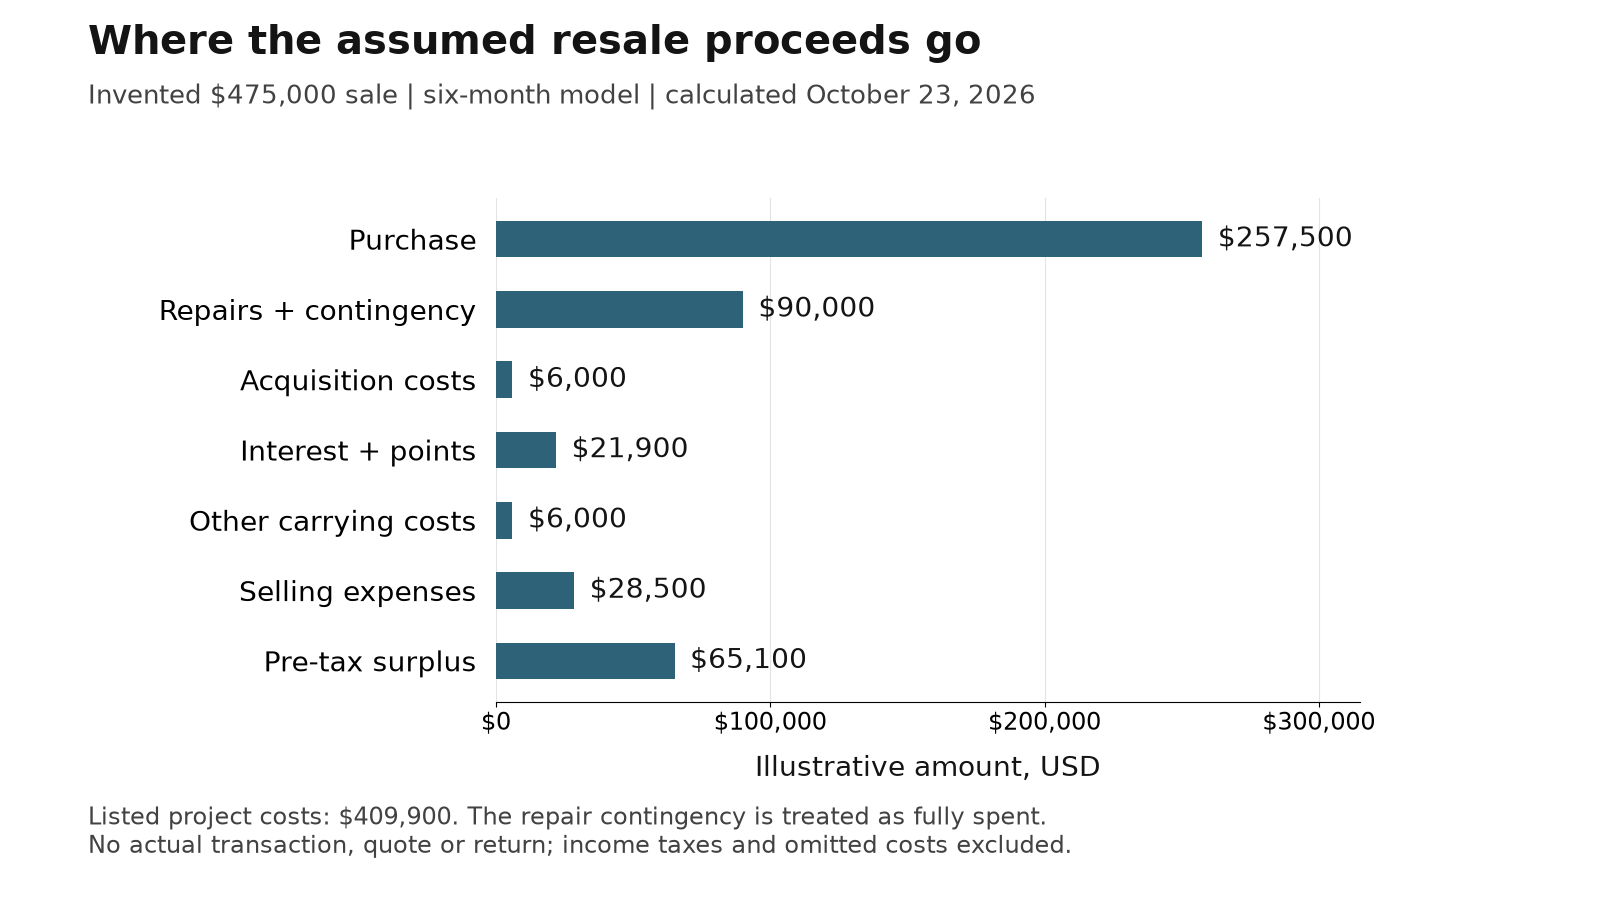
The following October 23, 2026 example assumes a $257,500 purchase, $75,000 planned repairs and a $15,000 repair contingency treated as fully spent. It also assumes a $300,000 loan commitment, $265,000 average outstanding balance, 12% simple annual interest over six months and two points on the full commitment. All amounts and terms are invented. An actual lender may charge on a different balance, use daily interest or impose additional fees.
| Item | Assumption | Amount |
|---|---|---|
| Purchase | Chosen acquisition price | $257,500 |
| Planned renovation | Illustrative work allowance | $75,000 |
| Repair contingency | 20% of planned work; fully spent in this model | $15,000 |
| Acquisition costs | Chosen closing and diligence allowance | $6,000 |
| Interest and points | $15,900 interest plus $6,000 points | $21,900 |
| Other carrying costs | $1,000 per month for six months | $6,000 |
| Selling expenses | Assumed aggregate 6% of $475,000; not a standard commission | $28,500 |
| Total project cost | All listed costs, including sale expenses | $409,900 |
| Sale proceeds before costs | Assumed resale price | $475,000 |
| Project surplus | Before income taxes and any omitted costs | $65,100 |
The carrying allowance must be replaced by actual taxes, appropriate insurance, utilities, HOA charges and other obligations. Selling costs need a written estimate covering negotiated brokerage compensation, title and escrow items, transfer charges and any buyer concession. There is no standard commission embedded in this example. Keep contractor overhead and your own compensation visible rather than assuming free labor.
If part of the contingency is unspent, actual results may improve; do not treat that possibility as available cash before the uncertainty is resolved. The example also excludes income taxes and does not assign a wage to the investor's time. Compare it with a seller's net calculation to understand why the headline resale price and the money retained are different measures.
How much can a slower sale or repair surprise change the result?
Test several things going wrong together. A lower resale can coincide with extra work and a longer hold. Examining each risk alone can make a project look resilient even though the combination consumes its entire margin. Use a written downside case before deciding whether the base case is attractive.
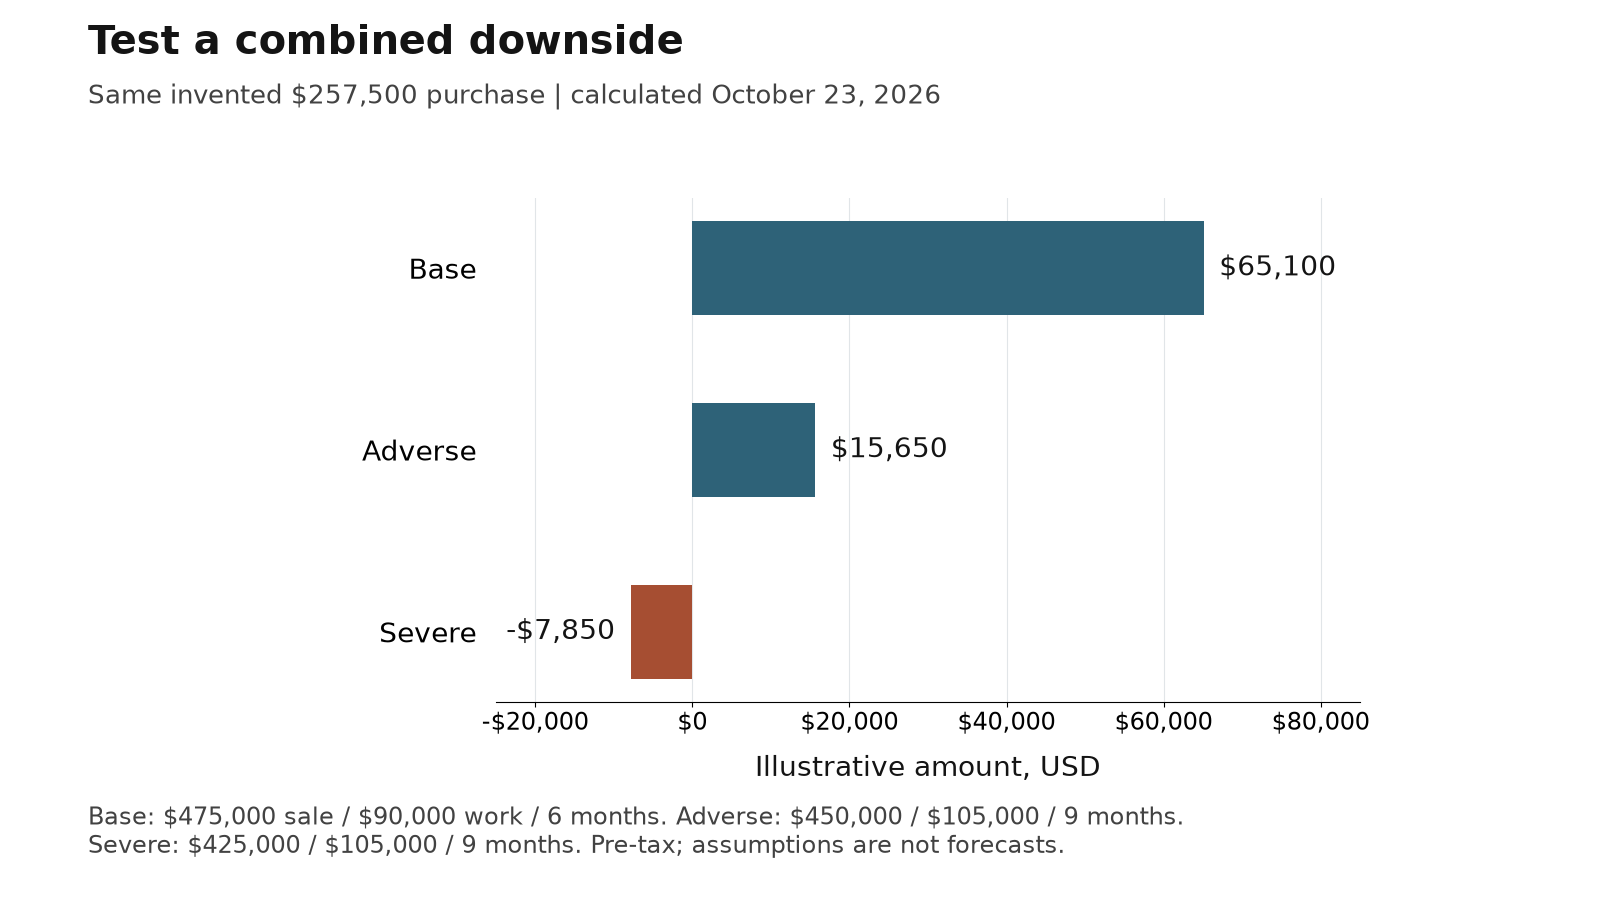
In the October 23, 2026 stress model below, the purchase stays at $257,500. The adverse case increases total repair spending from $90,000 to $105,000, extends ownership from six to nine months and reduces the sale to $450,000. The assumed average debt balance and rate remain unchanged solely to isolate the effects. In a real loan, an extra draw or extension could also change financing costs.
| Scenario | Resale | Total repairs | Hold | Pre-tax result |
|---|---|---|---|---|
| Base | $475,000 | $90,000 | 6 months | $65,100 |
| Adverse | $450,000 | $105,000 | 9 months | $15,650 |
| Severe | $425,000 | $105,000 | 9 months | -$7,850 |
Under the base assumptions, costs before selling expenses total $381,400. With selling expenses fixed at 6% of the eventual price, the calculated break-even resale is approximately $405,744.68. This is a model output, not an appraised value or a price you can necessarily obtain. A lender extension fee, additional repair or seller credit raises that break-even point.
Decide whether you can tolerate the adverse result and fund the severe case without relying on another uncertain sale. Set a review date for revised comparables and the remaining construction budget. If the resale case deteriorates, reassess the unfinished work before committing more money to discretionary finishes. An attractive original spreadsheet should not become a reason to ignore newer evidence.
How should you compare financing and available cash?
Compare complete written terms, including the property's intended investment use. Cash, private credit, renovation financing and equity borrowed against another property create different obligations. An owner-occupied loan cannot simply be treated as a short-term investor product if you do not intend to satisfy its occupancy requirements. Conversely, not every conventional loan is limited to owner-occupants; investment-property eligibility depends on the program and condition.
Ask what funds at purchase, what funds after work, and what you must pay first. A large loan commitment may include money that remains unavailable until a completed-work inspection. Retainage, draw processing, lien documentation and reimbursement timing can create a cash gap even when the total committed amount looks sufficient. A point is 1% of the specified loan amount; confirm whether that amount is the commitment, initial advance or another contractual basis.
| Structure | What to document | Material tradeoff |
|---|---|---|
| Cash | Acquisition funds, work budget and liquid reserves | No loan interest, but capital remains exposed and unavailable elsewhere |
| Short-term renovation loan | Advance schedule, interest basis, points, maturity, extensions and guarantees | Construction funding can be delayed or conditional |
| Private financing | Written loan terms, security, remedies and agreed repayment | A personal relationship does not remove legal or repayment risk |
| Equity from another property | Payment changes, lien exposure and repayment source | The project can put another property at risk |
In an additional invented cash-planning example, an initial advance of $206,000 against the $257,500 purchase leaves $51,500 of purchase equity. Adding $6,000 acquisition costs, $6,000 points, a $20,000 temporary draw bridge, $21,900 for modeled interest and carrying costs, and $15,000 of separate reserve totals $120,400 of planned cash availability. The temporary bridge is a liquidity allowance, not another project expense; adding it again to the profit budget would double count work funded later.
This amount is not a minimum required by a lender or a sufficient reserve for every project. Build a dated cash-flow schedule showing each payment, reimbursement and maturity. The owner-occupant fixer-upper financing guide addresses a different purchase purpose; verify eligibility instead of borrowing its down-payment assumptions for a speculative flip.
What should you verify before hiring a Nevada contractor?
Verify the contractor's active license, relevant classification and monetary limit with the Nevada State Contractors Board. Match the business name on the proposal, contract and payment instructions. Ask who is responsible for subcontractors, permits, inspections and closeout documents. A referral or polished portfolio is useful background, but it does not replace those checks.
According to NRS 624.031, the small repair or maintenance exemption is limited and has important exclusions, including work requiring a permit and specified trades. It is not blanket permission to divide a renovation into small unlicensed jobs. The statute also limits the owner-occupancy exemption to qualifying work for the owner's own occupancy, not an intended sale or lease. Check the actual provisions before assuming that ownership itself authorizes you to act as the contractor.
The Board's owner-builder guidance explains the exemption application and the responsibilities that remain with an owner-builder. A speculative resale project should not be underwritten on an assumed exemption. That page also contains a general dollar-threshold statement that differs from the current statute's detailed small-work provision; use the statute and obtain a project-specific Board answer instead of treating either short summary as universal permission.
A useful contract identifies the scope, materials, allowances, payment milestones, change-order process and completion responsibilities. Ask how concealed conditions will be priced and who approves extra work. Keep photographs and written records as construction proceeds. Confirm insurance and any required worker coverage with the relevant professionals, and obtain appropriate lien documentation before releasing payments.
Choose a contractor based on the work you actually need, not only the cheapest total. Two bids are not comparable if one includes demolition, disposal, permit coordination and system work while the other lists only visible finishes. Resolve missing items before using the bid in the acquisition budget.
Which Las Vegas permitting jurisdiction controls the renovation?
Identify the parcel's actual jurisdiction before asking for a permit estimate. A Las Vegas mailing address does not, by itself, establish that the City of Las Vegas issues the building permit. The responsible authority can be an incorporated city or unincorporated Clark County. Verify the address with the appropriate department, then ask what your exact work requires.
According to Clark County's permit guidance, regulated construction, alterations and changes to electrical, gas, mechanical or plumbing systems require the applicable application and permit. Exemptions exist, so describe the work instead of assuming every cosmetic task or every replacement has the same treatment. The county page does not set the requirements for a parcel inside another city's jurisdiction.
Request existing permit history, approved plans where available and inspection status before finalizing the renovation. A converted garage, added bathroom or enclosed patio may raise different questions from worn flooring. Determine whether the current configuration can be documented and whether your intended configuration can be approved. Do not count questionable space as legal living area in the resale comparison merely because it appears in a listing description.
Sequence approvals with construction. A permit application is not the same as an issued permit, and an issued permit is not a completed final inspection. Ask the contractor which inspections must occur before work is covered and which documents should be retained for resale. A buyer's lender or insurer may need information beyond what is visible during a tour.
Treat HOA architectural review as a separate question when the property belongs to an association. Association approval does not replace government approval, and a government permit does not settle private restrictions. The Nevada purchase checklist provides a broader document-review framework that remains useful when the buyer is an investor.
How do you set a renovation scope without overspending?
Separate work that addresses safety, functionality and legal condition from work intended to improve presentation. A prospective buyer may appreciate new counters, but that does not remove the need to evaluate a leaking roof, failed equipment or undocumented electrical work. Begin with inspections and the relevant specialist assessments, then price a coherent finished product.
Use a written room-by-room and system-by-system scope. Record quantities, material specifications, preparation, disposal, access needs and finish expectations. Allowances should identify what they include and how an overage is handled. If a bid says only “update kitchen,” it may leave cabinets, appliances, electrical changes and permit-related work undefined. Those omissions can turn a seemingly low bid into an expensive series of changes.
For older housing, according to EPA's guidance for house flippers, covered renovation work on pre-1978 properties is subject to the lead Renovation, Repair and Painting requirements when performed for profit. Doing the work yourself does not automatically create a homeowner exemption. When all work is hired out, the outside renovation firm must satisfy the applicable certification, work-practice and recordkeeping requirements. Resolve this before demolition begins.
The base example's 20% repair contingency is a chosen stress allowance, not a quoted Las Vegas norm. Its adequacy depends on the investigation and scope. A predictable finish refresh and a project with concealed structural uncertainty should not inherit the same contingency simply because their purchase prices match. Obtain specialist advice where the risk cannot be reasonably priced.
Use completed comparable properties to choose an appropriate finish level, while keeping required work intact. Avoid a discretionary upgrade unless you can explain its purpose and budget effect. A more elaborate finish may increase cost without producing an equal resale adjustment. Compare a renovation candidate with new-construction alternatives using total cost, completion risk and intended use rather than assuming either path offers a superior return.
How do the construction schedule and FHA resale rules affect the exit?
Build a schedule that includes acquisition, design or approvals, contractor availability, materials, inspections, marketing, buyer financing and closing. These phases do not always happen independently. A missed inspection can delay the next trade; a replacement material can alter the scope; a buyer's loan condition can extend ownership after you believe the renovation is finished.
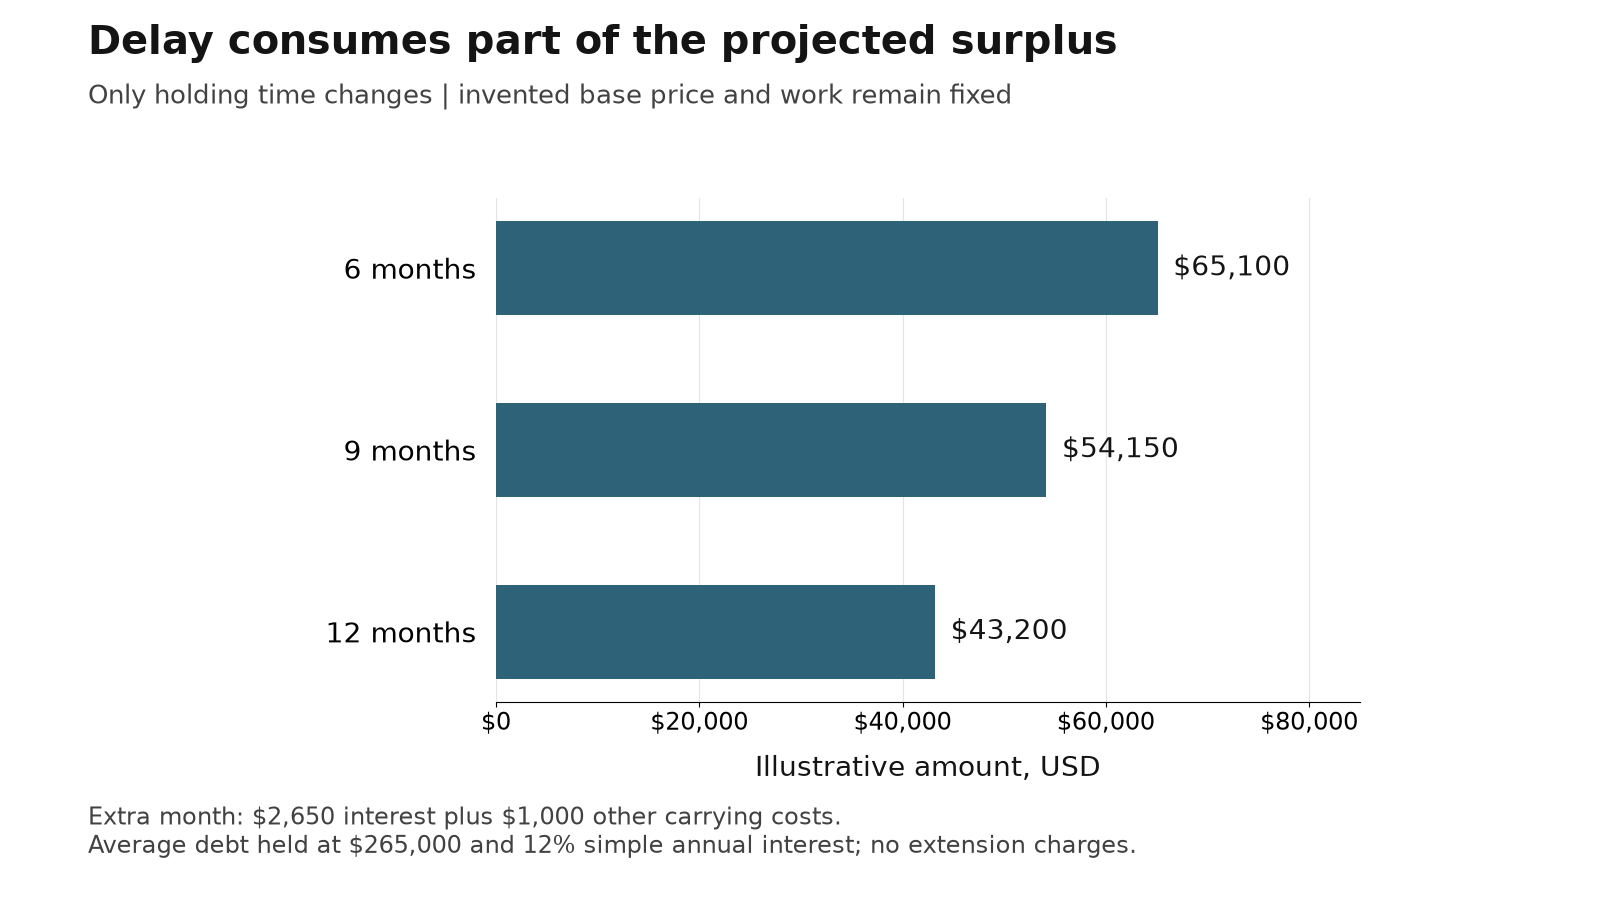
Under the invented financing assumptions, each additional month adds $2,650 interest on the $265,000 average balance plus $1,000 other carrying costs. Three extra months therefore reduce the project result by $10,950, before any extension charge. This calculation does not predict how long a Las Vegas flip takes. It makes the cost of a chosen delay visible.
According to HUD's current FHA Handbook 4000.1, reviewed in its August 12, 2026 edition, ordinary resales within 90 days or fewer of the seller's acquisition are generally ineligible for FHA financing, subject to specified exceptions. The resale date is when all parties execute the resale contract, not simply the later closing date. Check that distinction with the buyer's lender before accepting a contract that assumes FHA eligibility.
For a resale between days 91 and 180 at a price 100% or more above the seller's acquisition price, HUD requires a second appraisal by another appraiser. The borrower cannot be charged for that appraisal. Exceptions and valuation rules matter, so have the lender review the title history and exact transaction. HUD's FHA Connection explanation also describes the timing framework.
These are financing conditions, not a general prohibition on selling a recently acquired home. Other programs and lenders have their own rules. Keep accurate acquisition, contract and renovation records, and include a realistic financing review period in the exit plan rather than promising that every finished home will sell in a fixed number of days.
How are flip profits different from capital gains on an investment?
Tax classification comes before the holding-period calculation. According to IRS Publication 544, property held mainly for sale to customers in a trade or business is not a capital asset. A house acquired and renovated for resale may fall into that business category. It should not automatically be described as a short-term capital gain merely because the sale occurs within a year.
For property that does qualify as a capital asset, IRS Topic 409 explains that a holding period of one year or less generally produces a short-term gain or loss, while more than one year generally produces a long-term one. Net short-term capital gains are taxed at ordinary income rates. Holding business inventory longer does not, by itself, convert it into an investment capital asset.
Business income can also raise self-employment and estimated-tax questions. IRS Publication 334 explains the general small-business framework. Entity structure, activities, other income and the taxpayer's circumstances affect the result. The project surplus in this guide is before income taxes; it is not take-home pay and is not a calculated tax return.
According to the IRS's like-kind exchange guidance, real property held primarily for sale does not qualify for Section 1031 treatment. Do not assume an unsold flip becomes exchange-eligible just because the investor changes the label or waits longer. The Nevada 1031 guide provides related context, but a qualified tax adviser must evaluate the actual facts.
Keep acquisition records, invoices, loan statements, settlement statements and evidence of the property's use. Ask the adviser how costs should be classified and when payments may be due before distributing project cash. Nevada's location does not eliminate federal obligations, and a general article cannot settle every business, entity or local filing requirement.
When is holding the property a credible alternative to selling?
A rental fallback needs its own underwriting. It should not be a sentence added to make a weak resale analysis feel safe. Verify an achievable rent for the specific completed property, likely operating expenses, association restrictions, insurance, management arrangements and the financing needed after the construction loan matures.
Separate net operating income from cash flow after debt service. A property can produce rent above its ordinary operating costs and still require monthly cash because of the loan payment. Maintenance, vacancy and future capital work also matter. The Las Vegas rental-market guide is a starting point for questions; its general discussion cannot substitute for an actual lease proposal or property-level expense file.
Refinancing is a future application, not an automatic exit. An appraisal, loan-to-value limit, income or cash-flow qualification, seasoning requirement and current credit conditions can affect both approval and available proceeds. If a refinance returns less cash than expected, the investor must cover the gap or choose another solution. Confirm the current lender's maturity and extension provisions before relying on a future lender.
Compare the amount of capital that would remain invested with the return and obligations of holding. A home that suits a household moving into North Las Vegas may or may not fit your rental strategy; suitability for an occupant does not establish an investment return. Similarly, a finished property in Henderson needs its own expense and demand evidence.
Wholesaling or assigning a contract is another distinct transaction with contractual and legal questions. Have a Nevada real-estate attorney review the actual rights, disclosures and obligations before marketing an assignment or assuming you can exit without funding a purchase. Neither assignment nor a rental conversion is a guaranteed rescue for an acquisition that did not withstand its initial review.
What should be resolved before you commit to the purchase?
Create a decision file that another professional could follow. It should identify the address, intended work, supported resale range, contractor proposal, permit authority, title issues, financing terms and cash schedule. Record unresolved questions and the date by which each must be answered. A list of attractive finishes is not a substitute for that file.
Review the title commitment, recorded exceptions and any association documents with the appropriate professionals. Ask about liens, unpaid assessments, occupancy and possession. An occupied property, an auction purchase and a conventional vacant-home sale can create very different access and timing issues. Do not assume you can inspect freely, obtain ordinary financing or deliver vacant possession on the same terms in every transaction.
Keep contractual deadlines visible. Discuss the available inspection and financing protections with your agent and attorney, including what happens if a specialist cannot inspect before a deadline. If a material cost remains unknown, decide whether the contract permits more investigation, a revised offer or withdrawal. A desire to move quickly does not establish that a risk has been priced.
Use the Nevada buying process as context for the transaction steps, while recognizing that investor loans and construction work add separate requirements. Reconcile the contractor's scope with the lender's renovation budget and the appraiser's completed-condition assumptions. A project can fail even when each document looks reasonable in isolation if those documents describe different finished properties.
Before committing, sign off on a base case, a downside case and a cash plan. State who updates the file when bids, loan terms or comparable sales change. If a new fact changes the decision, revise the analysis rather than preserving the original result for consistency. Useful discipline means responding to the evidence you have now, not defending the first number you wrote down.
How can Nevada Real Estate Group help evaluate the purchase and resale?
Nevada Real Estate Group is the #1 real estate team in Nevada by RealTrends Verified, with roughly 9,600 closings across the valley and deep experience representing investors on both the buy and the sell. The useful discussion begins with a specific address, the work you intend to complete and the evidence needed to support the resale range. A company track record does not turn an individual project into a guaranteed profit.
Bring the proposed scope and financing assumptions when requesting a property review. Ask which comparable sales support the finished product, which current listings compete with it, and which differences require further investigation. Separate the agent's market analysis from a contractor's construction opinion, a lender's underwriting decision and an attorney's or tax adviser's professional advice. Each answers a different part of the investment question.
Plan the sale while planning the renovation. Preserve the documentation buyers may request, including permits, inspections, invoices and warranties where applicable. Decide how unfinished items will be handled before marketing begins. The seller services page and 7-day listing agreement information explain related services; they do not establish a seven-day sale or an investment return. A moving-to-Las-Vegas resource may help a prospective household evaluate relocation, but it is separate from the investor's financial analysis.
The practical next step is a property-specific comparison with documented assumptions and a clear list of open questions. Call (702) 637-1759 or contact the team to discuss that review. Do not commit capital solely because an example in this guide shows a surplus. The actual property, contracts, costs and resale evidence determine whether the project fits your resources and tolerance for loss.
Frequently Asked Questions
Can you still make money flipping houses in Las Vegas in 2026?
A particular project may produce a profit, but this guide does not establish an average current return. Evaluate supported resale value against the full purchase, renovation, financing, carrying and selling costs. The invented base example produces $65,100 before income taxes; the severe combined scenario loses $7,850. Neither is a prediction or an actual transaction.
Is the 70% rule a safe maximum offer?
It is a screening shortcut, not a safety guarantee. At $475,000 assumed ARV and $75,000 repairs, it gives $257,500. The complete cost model can produce a different purchase allowance, especially when financing, delays or additional work change. Set your actual offer from supported assumptions and an acceptable downside, not the percentage alone.
How much cash do you need for a Las Vegas flip?
There is no universal amount. Include purchase equity, closing expenses, points, work paid before reimbursement, carrying obligations and reserves. One invented cash schedule here totals $120,400, including a temporary $20,000 draw bridge and a separate reserve. That bridge measures liquidity; it is not an additional project expense or a lender's minimum requirement.
Can you do the renovation yourself as the property owner?
Ownership does not automatically authorize unlicensed contracting. Nevada's owner-builder exemption has conditions tied to personal occupancy and the absence of an intended sale or lease. Verify your exact situation with the Contractors Board and permitting authority. Covered pre-1978 work also raises EPA lead-safe certification and work-practice requirements, including for flippers who perform their own work.
Can an FHA buyer purchase the completed flip immediately?
Generally, a resale contract executed 90 days or fewer after the seller's acquisition is ineligible for FHA financing unless a specified exception applies. Days 91–180 can trigger a second appraisal when the resale price is at least double the acquisition price. The buyer's lender must review the dates, title history and applicable rules before the transaction relies on FHA financing.
Are all flip profits short-term capital gains?
No. Property held mainly for sale to customers in a trade or business is not a capital asset. The tax treatment depends on the actual activity and circumstances. The one-year holding-period distinction applies to qualifying capital assets; waiting longer does not automatically convert business inventory into one. Obtain tax advice before relying on a projected after-tax return.
Which Las Vegas ZIP code is best for flipping?
No ZIP code guarantees a workable project. A low asking price can reflect expensive condition, legal or access problems. Compare specific parcels with supported completed sales, repair scopes and realistic exits. Do not treat a ZIP-wide median or another neighborhood's renovated home as proof that your intended resale price is achievable.
Can you rent the home if the flip does not sell?
Only if the property's restrictions, condition, financing and rental economics support that plan. Verify rent and expenses separately and confirm how the construction loan will be repaid or extended. Refinancing and tenant demand are not guaranteed. A rental fallback that requires unavailable capital is not a workable backup.
Which sources and assumptions support this guide?
Primary rules were reviewed October 23, 2026. Sources support the identified requirements, not the invented project amounts or any promise of investment success. HUD coverage uses the relevant forward-mortgage flipping provisions in the August 12, 2026 handbook, alongside its accessible FHA Connection explanation. Our experience includes the roughly 9,600 transactions Nevada Real Estate Group has closed across the valley; these examples do not use a transaction-file study.
- Fannie Mae: Comparable Sales — appraisal selection, condition, timing and supporting evidence.
- Nevada Legislature: NRS Chapter 624 — contractor definitions and exemptions.
- Nevada State Contractors Board: Owner-Builder Information — responsibilities and application context; the statute controls the detailed small-work exemptions.
- Clark County: Do I Need a Permit? — county permit scope; verify the property's jurisdiction.
- EPA: RRP Requirements for House Flippers — covered pre-1978 renovation work.
- HUD: FHA Handbook 4000.1, August 12, 2026 and FHA Connection — resale timing, appraisal conditions and exceptions.
- IRS Publication 544, Topic 409, Publication 334 and like-kind exchange guidance — asset classification, holding period, business taxes and the exclusion for property held primarily for sale.
Original calculations use the explicitly stated prices, repair budgets, average loan balance, interest rate, points, holding periods and selling-cost percentage. Interest equals average balance multiplied by annual rate and years held. Profit equals resale less the listed project costs. The offer comparison subtracts a chosen $50,000 pre-tax target. Figures are rounded for presentation. No MLS sample, actual bid, inspection, client outcome, current mortgage quote is represented.