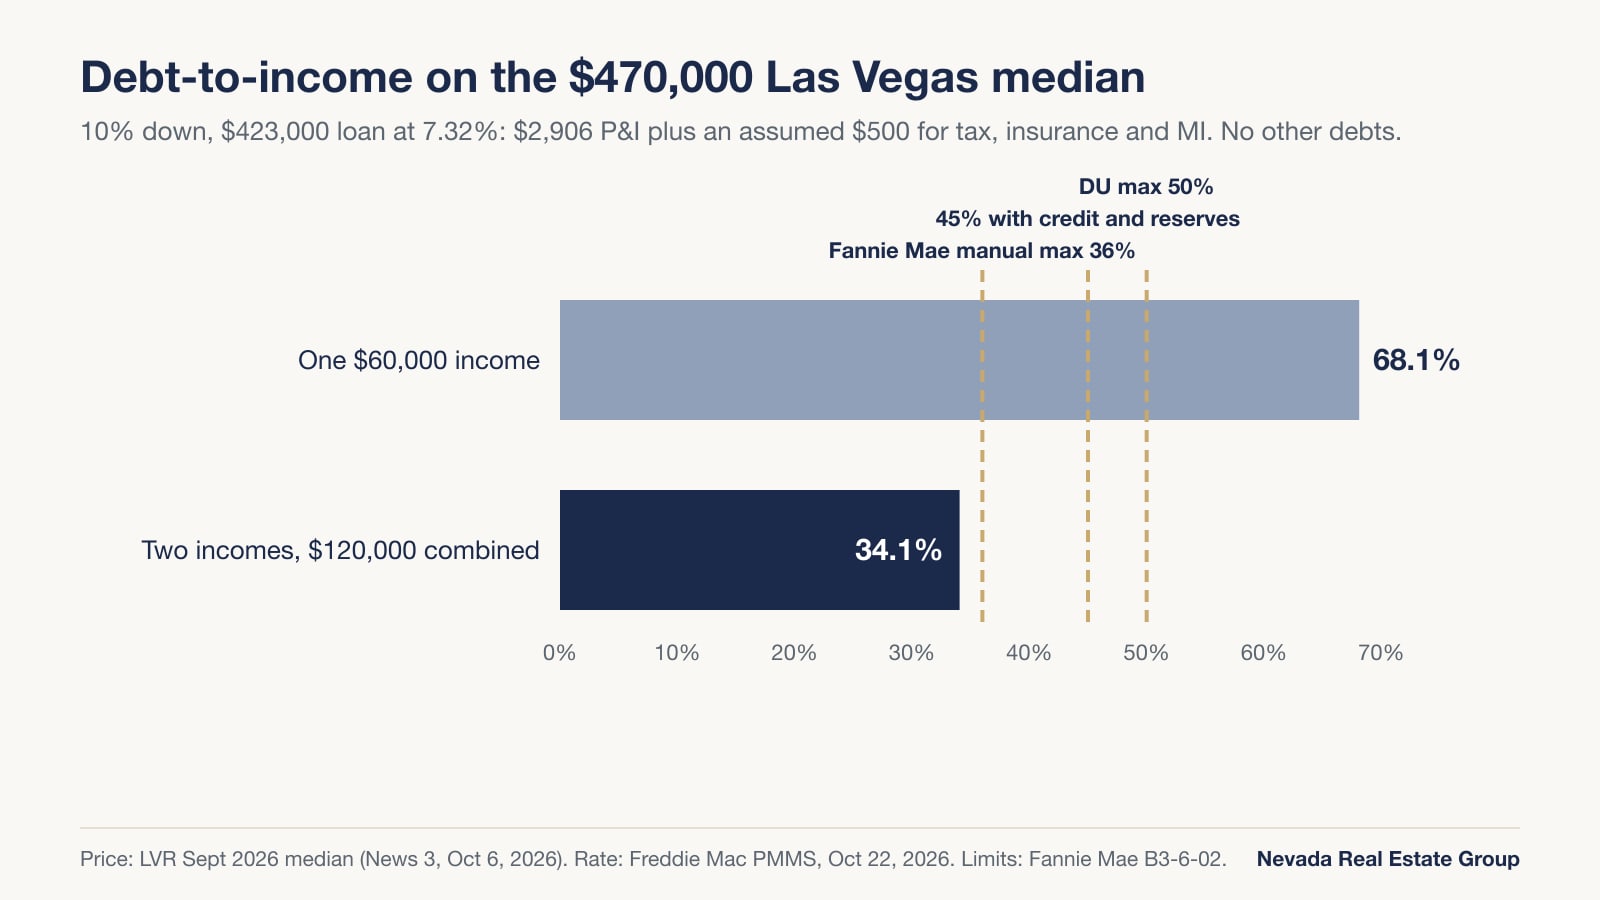
Co-buying comes down to arithmetic. On the $470,000 September 2026 median for an existing single-family home in Southern Nevada, 10% down at the 7.32% rate Freddie Mac reported on October 22, 2026 means $2,906 a month in principal and interest. With an assumed $500 for tax, insurance and mortgage insurance, one buyer with no other debts needs roughly $91,000 to $114,000 of income to keep the payment between 36% and 45% of gross income. Two $60,000 earners land near 34%. That gap is why people pool incomes with friends, siblings or parents, and why the deed, the agreement and the loan all have to be right on day one.
Co-buying works when three things are right: a deed that states how each owner holds title, a signed co-ownership agreement covering payments, buyouts and defaults, and a loan built on lender rules that count every borrower's debts and, at Fannie Mae, price off the lowest borrower's credit score. On the $470,000 September 2026 Las Vegas median at 7.32%, two $60,000 incomes carry the payment at about 34% of income; one alone would sit near 68%.
- Two $60,000 incomes carry the $470,000 median near 34% debt-to-income; one income alone sits near 68%.
- Nevada treats co-owners as tenants in common unless the deed expressly declares a joint tenancy (NRS 111.060).
- Fannie Mae prices the loan off the lowest borrower score, so have your lender quote it both ways.
- Every signer owes the full payment; your side agreement binds the partners, never the lender.
- Before closing, sign the buyout formula, sale trigger, default rules and loan-release requirement in writing.
Why Are Las Vegas Buyers Weighing Co-Buying Right Now?
Affordability, mostly. According to Freddie Mac's Primary Mortgage Market Survey, the 30-year fixed rate averaged 7.32% on October 22, 2026, up from 6.19% a year earlier; on a $423,000 loan that adds about $318 a month ($2,906 versus $2,588). Prices haven't fallen to offset it. According to Las Vegas REALTORS figures reported by News 3, the September 2026 single-family median across Las Vegas and Southern Nevada was $470,000, the same as September 2025, while single-family sales fell 7.4% year over year.
Household formation is the second current. According to the U.S. Census Bureau's December 2025 release, the median age at first marriage reached 30.8 for men and 28.4 for women in 2025, up from 23.5 and 21.1 in 1975. People are marrying later, and a single income has to carry an entire payment at today's rates.
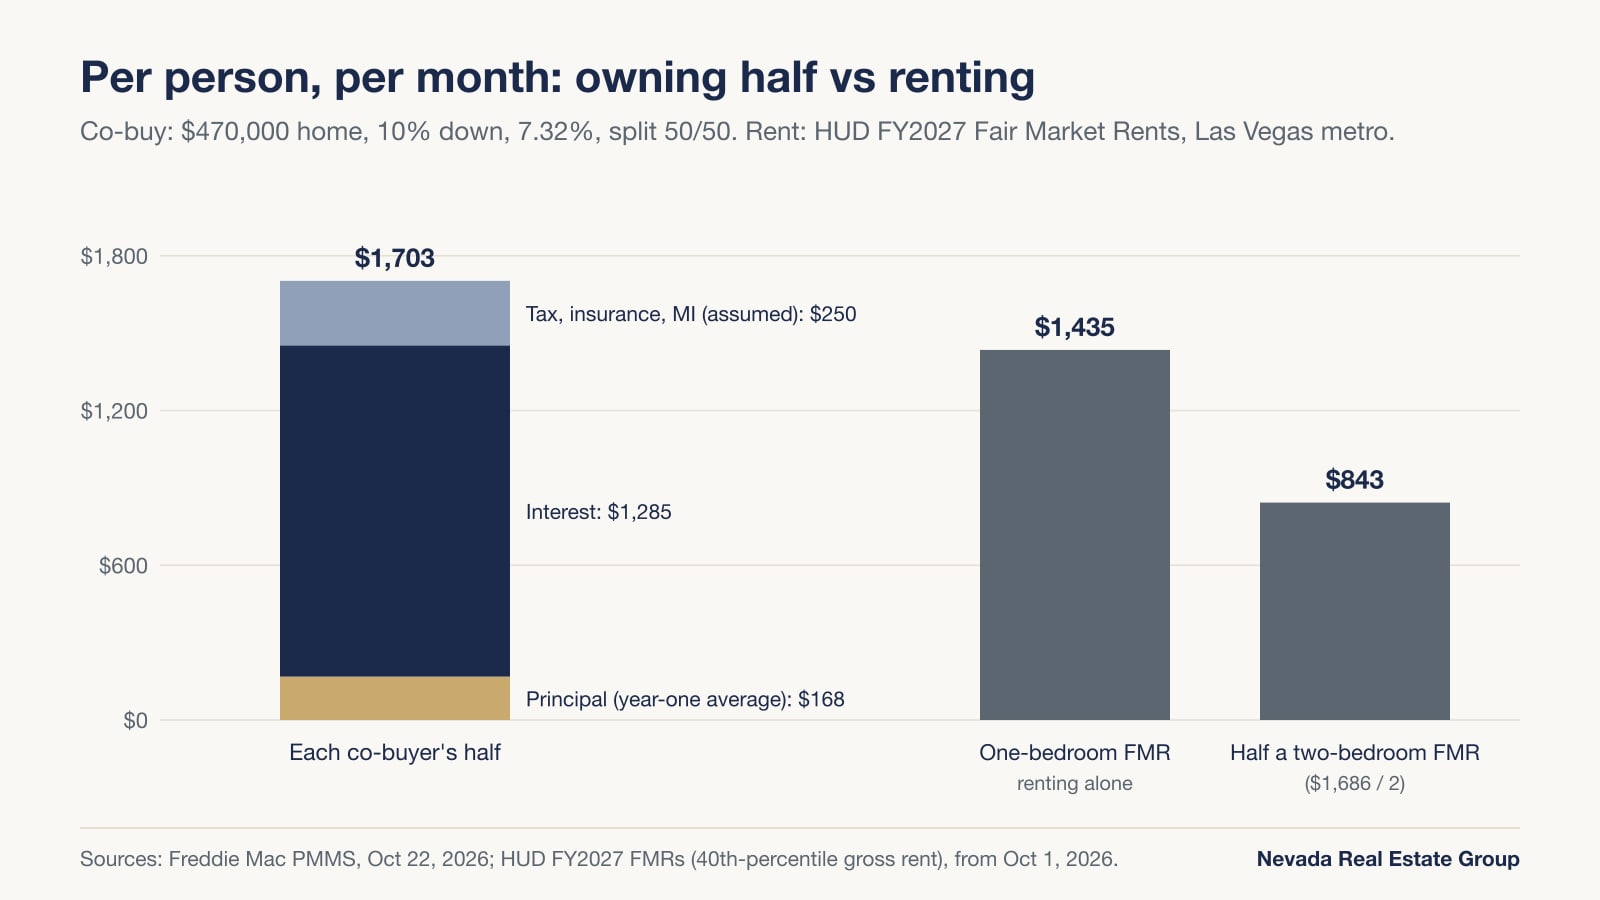
Be honest about rent, too. HUD's fiscal 2027 Fair Market Rents for the Las Vegas metro, in effect since October 1, 2026, are $1,435 for a one-bedroom and $1,686 for a two-bedroom (HUD FY2027 schedule). Each half of the $470,000 example below runs about $1,703 a month, roughly $268 more than the one-bedroom figure, and because FMRs are gross rents that include utilities while the ownership figure doesn't, the real gap is wider. The case for co-buying is ownership and equity, not a lower monthly bill, and prices in North Las Vegas or Henderson change the math, so run it on the actual home. Co-buying also bolts a financial partnership onto a personal relationship, and partnerships fail on ambiguity, not malice. Every risk here is managed with paperwork signed while everyone still likes each other.
How Should Co-Buyers Hold Title in Nevada?
The vesting line on the deed decides who owns what and what happens at a death. Under NRS 111.060, property granted to two or more people is a tenancy in common unless the deed expressly declares a joint tenancy, which NRS 111.065 governs. Our Nevada title guide covers every option; the co-buyer's short list:
| Factor | Tenancy in Common | Joint Tenancy | One on Loan, Both on Title | LLC Ownership |
|---|---|---|---|---|
| Ownership shares | Can be stated on the deed, such as 60/40 | Undivided; courts presume equal shares | As stated on the deed | Per the operating agreement |
| At a co-owner's death | Share passes through that owner's estate | Survivor takes title; an affidavit of death is recorded (NRS 111.365) | Depends on the vesting | Per the operating agreement |
| Financing | Both can borrow on one loan | Both can borrow on one loan | Non-borrower signs the deed of trust but not the note | Fannie Mae buys loans made to natural persons and certain trusts, not LLCs |
| Watch out | Heirs become your co-owners | Your share goes to your co-owner, not your heirs | The non-borrower's share is still collateral | Needs financing outside Fannie Mae's rules |
For unmarried co-buyers who contribute unequally, a tenancy in common with the percentages written on the deed is often the cleaner frame; have a Nevada attorney confirm the vesting wording before closing. Writing it down matters in Nevada: courts presume co-owners share equally, and under Sack v. Tomlin (1994) and Howard v. Hughes (2018) unrelated co-owners can rebut that with unequal contributions only by showing no gift was intended. On March 5, 2026, in an unpublished order in Benton v. Cloutier, the Nevada Court of Appeals reversed an award of 95.83% of a jointly titled home's equity to one unmarried co-owner: the trial court hadn't clearly started from the equal-share presumption, and it applied a preponderance standard where clear and convincing evidence was required.
Two more rules belong on the checklist. If a co-buyer is married, NRS 123.220 makes property acquired during marriage community property unless otherwise provided, and NRS 123.230 bars either spouse from conveying or encumbering community real property unless both join, so ask the title officer early how the spouse's interest will be handled. And under NRS 111.315, recording the deed with the county recorder (the Clark County Recorder for Las Vegas homes) is what gives notice to third parties.
What Belongs in the Co-Ownership Agreement?
An attorney-drafted co-ownership agreement is the highest-leverage document in the purchase; fees vary, so get a written quote before you open escrow. It answers eight questions in writing. Who pays what: mortgage, taxes, insurance, HOA, utilities and the repair fund, with percentages that may differ from ownership shares. What counts as an emergency and who can authorize spending; an air-conditioning failure in July needs a protocol, not a group-chat argument. The exit ramp: a right of first refusal for the co-owner, a buyout price set by appraisal rather than negotiation, and a defined financing window (60 or 90 days, for example). The forced-sale trigger: a listing at appraised value with our seller team or another brokerage, on a timeline nobody can stall. Default mechanics: covered payments become repayment with interest or a share adjustment. Death and disability: buyout options against an owner's estate, coordinated with each owner's estate documents. Occupancy rules: who lives there and whether partners can move in. Dispute resolution: mediation before litigation.
The fallback without an agreement is a courtroom. Under NRS 39.010, any co-owner can sue for partition, and under NRS 39.120 the court may order a sale when the property can't be divided without great prejudice, which is usually the case with a single-family home. NRS 39.480 charges partition costs, and in the court's discretion reasonable counsel fees spent for the common benefit, against the owners' shares. If an owner dies and their share passes to a relative with no agreement in a record binding all co-owners, the home can become "heirs property" under NRS 39.630, which adds a court-set value and a 45-day buyout election (NRS 39.675). Ask your attorney whether and how your agreement binds heirs.
Treat a co-buyer's reluctance to sign a written agreement as a warning sign. "We don't need all that, we trust each other" means the partnership runs on assumptions, and the agreement is what turns those assumptions into commitments that settle disputes later.
How Do Lenders Underwrite Two Co-Buyers on One Loan?
Everyone's debts count. Two borrowers means two full debt pictures merged into one debt-to-income ratio. According to Fannie Mae's Selling Guide B3-6-02, the maximum is 36% on a manually underwritten loan, up to 45% with the required credit score and reserves, and 50% through Desktop Underwriter (DU).
Pricing follows the lowest score. Fannie Mae's B3-5.1-02 (April 22, 2026) takes each borrower's score, then uses the lowest as the loan's representative score "for pricing purposes (i.e., assessing LLPAs) on all loans." LLPAs are loan-level price adjustments that show up in your rate or points. We couldn't open Fannie Mae's current matrix, so we don't quote a dollar figure here. Ask your lender to price the loan with and without the lower-score borrower. FHA uses the lowest borrower's score for eligibility instead: a score from 500 to 579 caps the loan at 90% loan-to-value (HUD Handbook 4000.1, revised August 12, 2026, pages 151 and 179). That makes the 90-day credit tune-up a team sport.
Everyone owes the whole payment. The standard fixed-rate note (Form 3200, section 8) makes each signer "fully and personally obligated" for the full amount, and the Nevada deed of trust (Form 3029, section 14) makes liability joint and several (Freddie Mac uniform instruments). An owner who signs the deed of trust but not the note pledges their interest and is "not personally obligated to pay," which is how one-on-loan, both-on-title works; lenders differ on allowing it, so confirm before you write an offer.
Occupancy is non-negotiable. Fannie Mae's occupancy rule (B2-1.1-01) says "only one borrower must occupy and take title" for a principal-residence loan, and the deed of trust (section 6) requires moving in within 60 days and staying at least one year unless the lender agrees otherwise. If nobody moves in, it's an investment loan. Forward Lending's Fannie Mae matrix dated September 2, 2026 shows a one-unit investment purchase capped at 85% loan-to-value, and Fannie Mae's occupancy topic says an LLPA applies to all loans on investment property, on top of other adjustments. Under 18 U.S.C. § 1014, a knowingly false statement to a mortgage lender or the FHA carries up to 30 years in prison, a fine of up to $1,000,000, or both.
What Does the Co-Buying Math Look Like in Practice?
Here is the example for October 2026: two people earning $60,000 each buy at the $470,000 September median with 10% down at the 7.32% PMMS rate. The $500 monthly tax, insurance and mortgage-insurance allowance is an assumption; replace it with real quotes and run your own numbers in our mortgage calculator.
| Line | Solo ($60,000 income) | Co-Buy ($120,000 combined) |
|---|---|---|
| Down payment at 10% | $47,000 alone | $47,000 ($23,500 each) |
| Principal and interest, $423,000 at 7.32% | $2,906 | $2,906 ($1,453 each) |
| Total with assumed $500 allowance | $3,406 | $3,406 ($1,703 each) |
| Debt-to-income, no other debts | 68.1%, over every Fannie Mae limit | 34.1%, under the 36% manual limit |
| Price reachable at 45% debt-to-income | About $283,000 | The full $470,000 |
| Principal paid down in year one | Not applicable | $4,039 (about $168 a month each) |
| Equity after year one, flat prices | Not applicable | About $51,000 combined, before selling costs |
The per-person row is the honest headline: about $1,703 a month each, roughly $268 more than HUD's one-bedroom Fair Market Rent, with about $168 going to principal in year one. The median was flat from September 2025 to September 2026, so the table assumes no appreciation; any gain is upside, not a promise. That equity is illiquid and jointly held, and it leaves only through the agreement's machinery.
How Do Co-Buyers Exit Cleanly When Life Changes?
Every co-ownership ends, and the endings sort into four patterns. The buyout: one partner's life changes, whether marriage, relocation or a new-build home in Las Vegas of their own, and the other buys their share at appraised value, usually by refinancing; appraisal instead of negotiation keeps the friendship intact. The joint sale: the home lists and proceeds split per the deed, which is why the shares were recorded correctly at closing. The conversion: the departing partner keeps their share as an investment, which works only with payment, maintenance and eventual-sale terms rewritten. The collision: no agreement, no cooperation, and a partition suit under NRS chapter 39, where the court can order a sale and the costs come out of the owners' shares.
One step matters more than any other: get the departing partner off the loan. Under the note's joint-liability clause, a co-borrower stays fully obligated until the loan is paid off, refinanced or the lender releases them, so a partner who leaves the house but stays on the mortgage carries that debt into their next application. Write the release-from-loan requirement into the buyout clause, with a deadline. And test the buyout before you promise it: the partner who stays must qualify alone for the new loan at that day's rate, not the rate you bought at.
What Money Habits Keep a Co-Ownership Healthy After Closing?
The agreement is the constitution; the monthly rhythm is the government. One joint house account, funded by automatic transfers, pays the mortgage and HOA, so nobody ever requests half a mortgage at 11 p.m. A real reserve from month one turns the worst co-ownership fight, surprise money, into a transfer. An annual reconciliation trues up the contribution ledger against the agreement's percentages and gives "I've been thinking about next year" a standing forum twelve months before it becomes a crisis. A written ledger of every extra payment and fronted repair lets generosity stay generous: a covered month that's written down is a favor, and one that's half-remembered three years later is a resentment. Put the account's rules in the agreement too: who can withdraw, what needs both signatures, and what happens to the balance at a buyout.
| Mechanism | Setup | Why It Works |
|---|---|---|
| Joint house account | Automatic transfers on a fixed date; all housing costs pull from it | Removes the monthly ask entirely |
| Repair reserve | For example, $150-$250 a month each toward a $5,000-$8,000 floor | Pre-decides the air-conditioning emergency |
| Contribution ledger | Shared sheet; every uneven dollar logged | Keeps favors from fermenting |
| Annual reconciliation | Fixed date; equity, ledger and plans reviewed | Surfaces exits a year early, not a week late |
How Does Co-Buying Affect Each Partner's Next Chapter?
The full payment usually counts against each of you. Because each borrower is fully obligated on the note, the whole housing payment generally shows up in each partner's debt-to-income on a later application. According to Fannie Mae's Selling Guide B3-6-05 (August 5, 2026), a lender may leave it out only when the party making the payments is also obligated on the mortgage, there are no delinquencies in the most recent 12 months, 12 months of canceled checks or bank statements prove it, and the borrower isn't using rental income from that property to qualify. A 50/50 split paid from a joint account is unlikely to meet that test, so plan a solo purchase around carrying the full payment, or around a buyout and refinance first. Credit reporting runs both ways: every on-time month builds both files, and a late payment lands on both regardless of whose month it was. The equity is locked up: turning your share into a down payment runs through the buyout machinery and its financing window, so start the exit conversation six months ahead, not six weeks. A marriage changes the file: a share owned before marriage starts as separate property under NRS 123.130, so ask your attorney how payments made after the wedding are treated, and update the agreement.
What Should Parents Know Before Co-Buying With Adult Children?
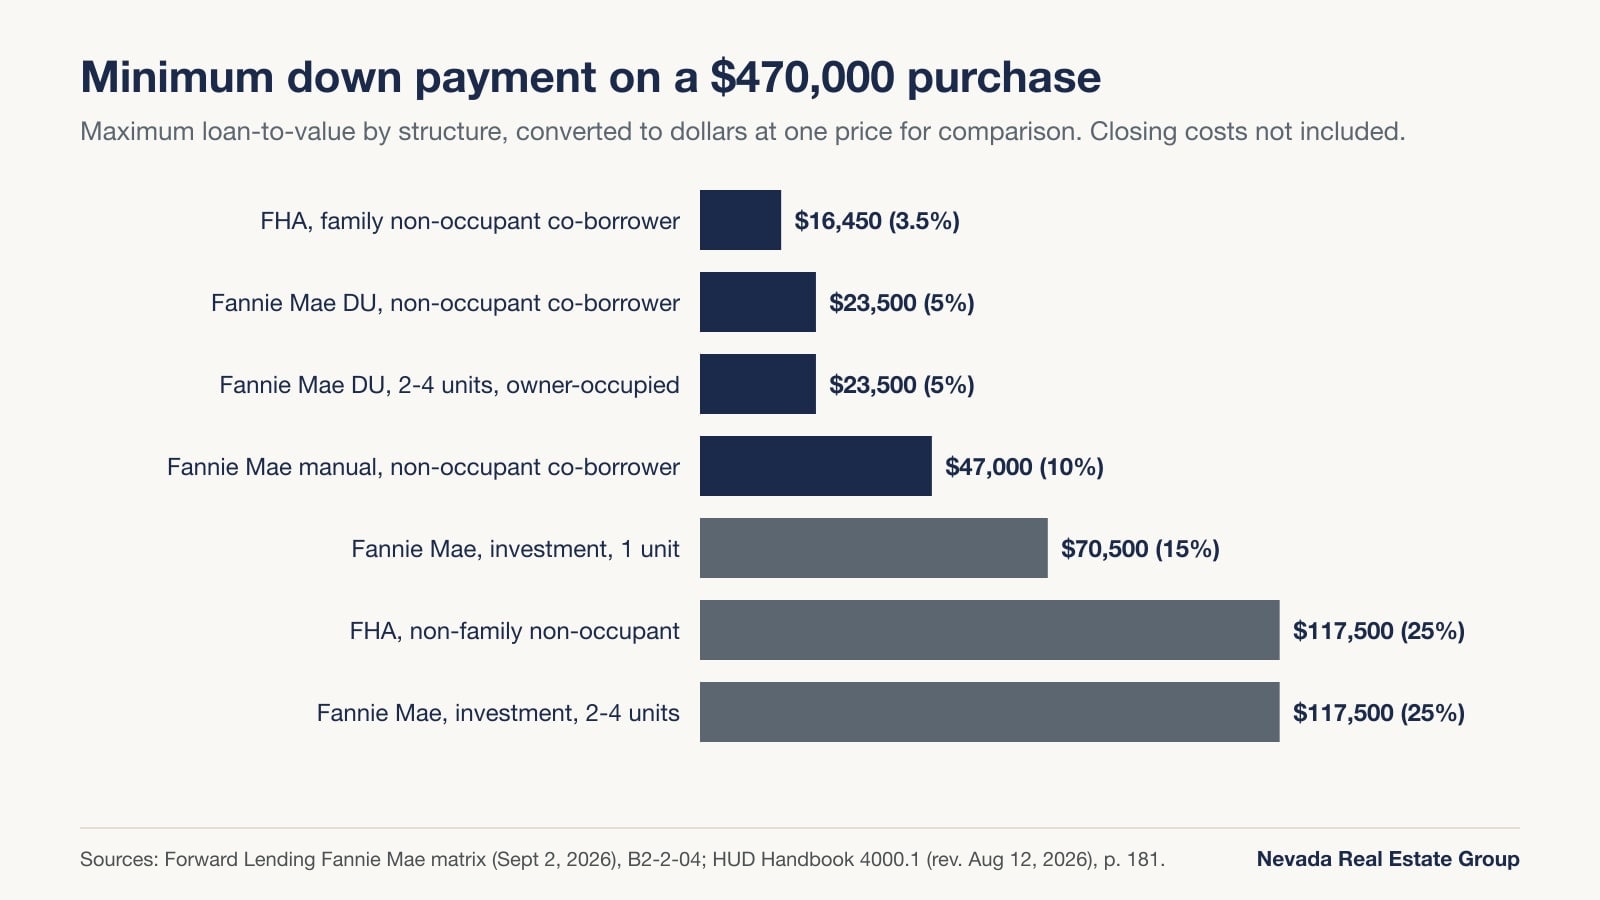
Choose the role deliberately. Co-borrowing means the parent signs the note and is fully liable; gifting means a documented gift funds the down payment and the parent owns nothing; co-owning means the parent holds a deeded share as an investment. Families blur these; lenders never do. A parent who co-borrows without moving in is a non-occupant borrower: according to Fannie Mae's Selling Guide B2-2-04, the loan can still be a principal-residence loan at up to 95% loan-to-value through DU or 90% manually underwritten, and FHA allows 96.5% only when the borrowers are family members and the home isn't two to four units (HUD Handbook 4000.1, page 181).
Document gifts on both sides. Fannie Mae's gift rules (B3-4.3-04) require a signed letter stating the amount and that no repayment is expected. According to the IRS gift-tax FAQ, the 2026 annual exclusion is $19,000 per recipient, and the Form 709 instructions say a donor who gives one person more than that in a year generally must file a gift tax return. Under IRS Publication 551, a gift generally carries the donor's basis while inherited property generally takes its value at death, so how and when a parent transfers a share is a question for a CPA, alongside the estate planning in our title guide. The agreement matters more with family, not less.
Which Alternatives Do Buyers Weigh Against Co-Buying?
Full co-ownership isn't the only way to combine two people's resources, and each alternative has its own lender rule:
| Alternative | Who Owns | Lender Rule | Confirm in Writing |
|---|---|---|---|
| Non-occupant co-borrower | The occupant; the co-borrower may or may not hold title | Fannie Mae 95% LTV (DU) or 90% (manual); FHA 96.5% for family on one unit, 75% otherwise | Title, and how the co-borrower later comes off the loan |
| Gift of down payment | The buyer alone | Signed gift letter; no minimum own funds on a one-unit home | IRS Form 709 if over $19,000 per recipient in 2026 |
| Owner-occupied duplex to fourplex | An owner lives in one unit, rents the rest | Fannie Mae 95% LTV on conforming loan sizes, per a lender's matrix; ask about lower limits on high-balance or manually underwritten loans. Above 80%, a gift can't replace the buyer's own 5%. FHA three- and four-unit homes face a rent self-sufficiency test | How much rent the lender will count |
On three- and four-unit homes, FHA's test (HUD Handbook 4000.1, pages 170–171) requires the appraiser's rent for all units, less at least 25%, to cover principal, interest, taxes and insurance. Our duplex house-hack guide, down payment guide and FHA loan guide go deeper. The chart converts each structure's maximum loan-to-value into dollars at one $470,000 price; read it as a comparison of rules, not a shopping list.
Frequently Asked Questions
Can friends buy a house together in Las Vegas?
Yes. A deed naming two or more buyers without declaring a joint tenancy creates a tenancy in common (NRS 111.060), and it can state each owner's share. You qualify jointly, with combined incomes and debts, and should sign a co-ownership agreement. On the $470,000 September 2026 median at 7.32%, two $60,000 incomes put the payment near 34% of gross income.
How should two friends hold title on a Nevada home?
Often as tenants in common, with the percentages written on the deed; confirm the vesting wording with a Nevada attorney or your title officer. Nevada courts presume co-owners share equally unless the evidence rebuts it, so writing the shares down avoids that fight. Each share passes to its owner's heirs, which the buyout clause should anticipate. Joint tenancy sends your share to your co-owner instead.
Do both credit scores matter when co-buying?
Yes. Lenders merge every borrower's debts into one ratio, and Fannie Mae prices the loan off the lowest score, so ask your lender to price it with and without the lower-score borrower. FHA uses the lowest borrower's score for eligibility: from 500 to 579, the maximum is 90% loan-to-value.
What is a co-ownership agreement and do we really need one?
It's an attorney-drafted contract covering payment splits, emergencies, an appraisal-based buyout, forced-sale triggers, defaults, death, occupancy and dispute resolution. Without one, either owner can sue for partition under NRS 39.010, and the court may order the home sold (NRS 39.120), with partition costs charged against the owners' shares.
What happens if one co-owner stops paying the mortgage?
The standard note makes each signer "fully and personally obligated" for the full amount, so the paying partner covers the whole payment or both credit files take the hit. Between you, the agreement's default clause turns covered payments into a debt with interest or a share adjustment. A funded reserve keeps it from coming to that.
How does one co-buyer exit and get their name off everything?
Through a buyout at appraised value, funded by a refinance that releases the departing partner from the loan. The release matters as much as the money: under Fannie Mae's B3-6-05, a later lender can leave the old payment out of your ratios only with 12 months of proof that another obligated party paid it.
Can parents co-buy with adult children in Las Vegas?
Yes, by co-borrowing, gifting or co-owning. A non-occupying parent can co-borrow on a principal-residence loan up to 95% loan-to-value through Fannie Mae's DU, or 96.5% with FHA when the borrowers are family members. Gifts need a signed gift letter, and gifts above $19,000 per recipient in 2026 generally require an IRS Form 709.
Is co-buying a good investment or just an affordability move?
It can be both, but year one is modest. On the $470,000 example each partner pays about $1,703 a month, about $268 more than HUD's one-bedroom Fair Market Rent, and the pair pays down $4,039 of principal. With prices flat from September 2025 to September 2026, equity comes mostly from the down payment and paydown.
Ready to Structure a Co-Purchase That Survives Real Life?
Bring your co-buyer and your numbers, and we'll walk through the joint qualification with your lender, map the vesting choice, and build the search around the combined budget, from North Las Vegas to Henderson and Summerlin townhomes. Have a Nevada real estate attorney draft the co-ownership agreement before you open escrow. Call (702) 637-1759, start with the buyer team, or browse the live market together tonight. Email info@nevadagroup.com anytime.
Nevada Real Estate Group · 8945 W Russell Rd, Suite 170 · Las Vegas, NV 89148 · (702) 637-1759 · NV License S.181401
Which Sources Inform This Co-Buying Guide?
Market inputs: Freddie Mac PMMS (October 22, 2026); Las Vegas REALTORS September 2026 figures as reported by News 3 and Fox5 on October 6, 2026; HUD FY2027 Fair Market Rents; and the Census Bureau's 2025 families release. Payment, debt-to-income and paydown figures are our calculations from those inputs with the stated $500 allowance.
Nevada law: NRS 111, NRS 39, NRS 123 and Benton v. Cloutier. Lending: Fannie Mae Selling Guide B3-5.1-02, B3-6-02, B3-6-05, B2-2-04, B2-1.1-01, B2-2-01 and B3-4.3-04; Forward Lending's Fannie Mae matrix, used because Fannie Mae's own Eligibility and LLPA matrices refused our fetch, so confirm limits with your lender; HUD Handbook 4000.1; the uniform note and Nevada deed of trust; and 18 U.S.C. § 1014. Gifts: IRS gift-tax FAQ, Form 709 instructions and Publication 551.
This guide is general information, not legal, tax or lending advice. Co-ownership agreements belong with a Nevada attorney, tax questions with a CPA and loan terms with your lender.