Selling a Las Vegas home requires two separate calculations: the money left after closing and the gain reported for tax purposes. A large mortgage payoff can reduce your cash without reducing your taxable gain. A qualifying home-sale exclusion can eliminate eligible gain without eliminating transfer tax, escrow charges or the need to file a return.
Across the 9,600-plus transactions Nevada Real Estate Group has represented statewide — including 789 homes sold in 2025 alone — the practical starting point for this guide is a documented property history. Gather the purchase settlement statement, improvement invoices, occupancy dates, rental records and proposed selling costs before deciding when to list. The tax result depends on those records and your return, rather than a neighborhood's median price.
The rules below were checked against IRS, Nevada and California sources on November 1, 2026, and the market figures come from Las Vegas MLS closings counted by closing date. Every worked example is invented arithmetic. This is general information for Southern Nevada sellers; a CPA or tax attorney should apply the rules to your circumstances.
For a 2026 sale, a qualifying Las Vegas main-home seller may exclude up to $250,000 of gain filing single, or $500,000 as eligible married joint filers, under Section 121. Gain is selling price less selling expenses and adjusted basis, and rental use can shrink the exclusion. Nevada has no individual income tax, but Clark County transfer tax is generally $2.55 per $500 of taxable value as of November 1, 2026.
- A mortgage payoff changes your closing cash, but it does not change adjusted basis or gain.
- The $500,000 joint exclusion requires both spouses to meet the residence test and the two-year look-back.
- The 2026 zero-rate long-term gain band ends at $49,450 for single filers and $98,900 for joint filers.
- Rental use and depreciation can leave taxable gain even when total gain sits below the exclusion cap.
- Nevada has no individual income tax, yet Clark County transfer tax still runs $2.55 per $500.
How Do You Separate Sale Proceeds From Capital Gain?
Start with a sale worksheet and a tax worksheet beside each other. According to IRS Publication 523, gain is the amount realized from a sale minus adjusted basis. Amount realized generally begins with selling price less selling expenses. The bank balance left after paying your mortgage is a different number, even when both calculations start with the same contract price.
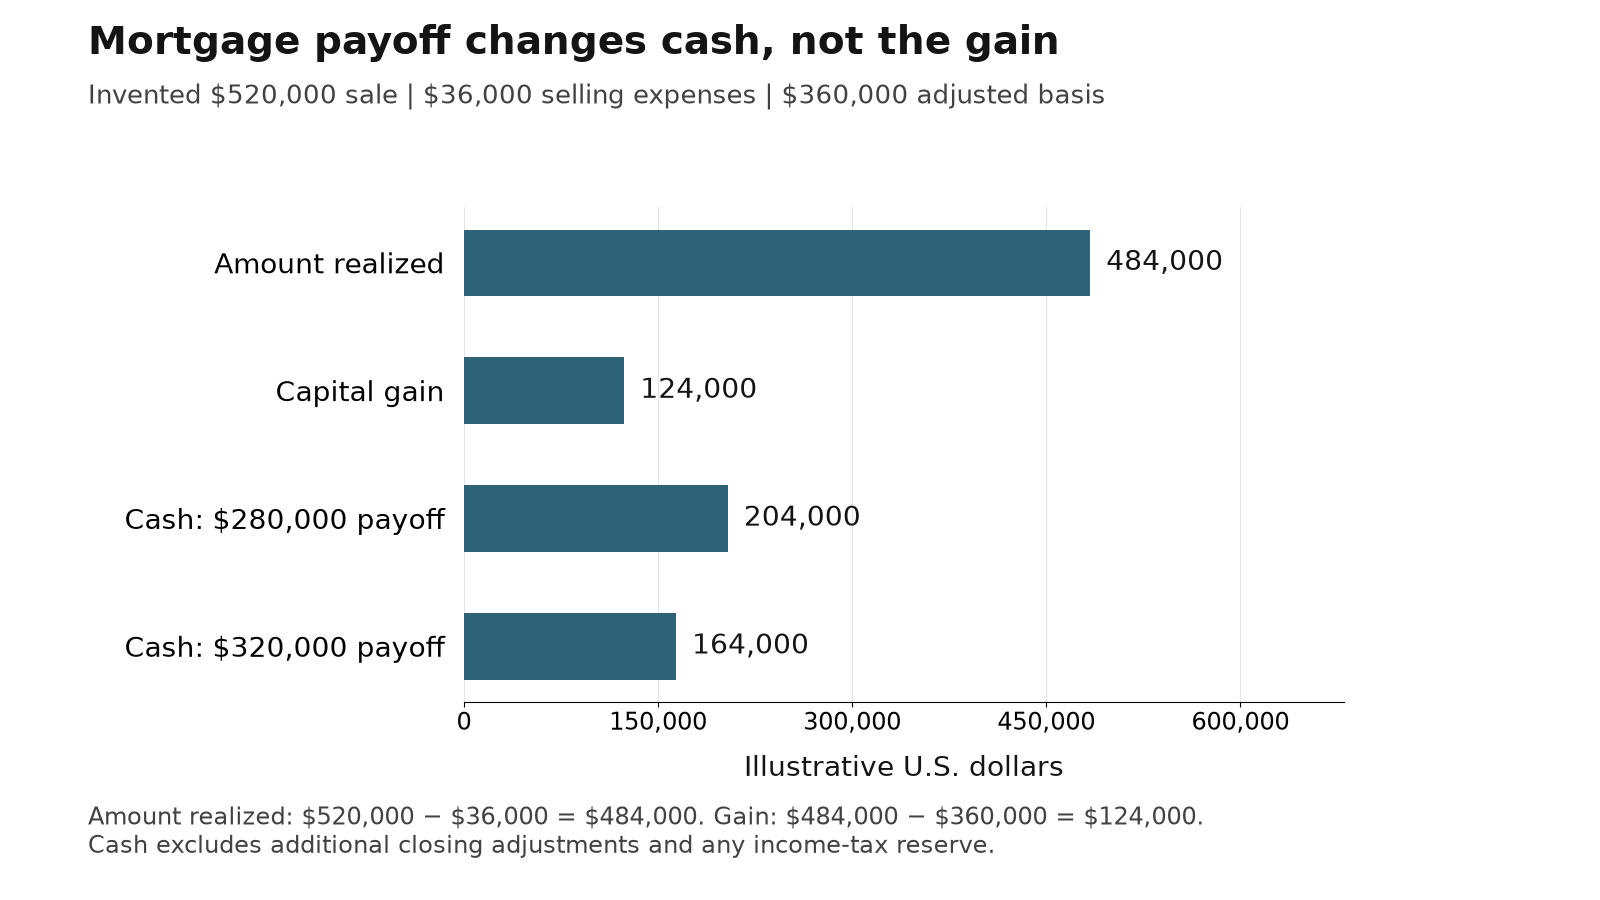
Consider an invented Summerlin transaction: a $520,000 sale, $36,000 of assumed selling expenses and a $360,000 adjusted basis. Amount realized is $484,000 and gain is $124,000. If the mortgage payoff is $280,000, cash after those two deductions is $204,000 before any additional adjustments or tax reserve. A $320,000 payoff would reduce that cash to $164,000 while leaving the $124,000 gain unchanged. No actual listing, fee quote or client outcome is represented.
A cash-out refinance does not itself add its proceeds to basis. If borrowed money funded qualifying improvements, the documented improvement expenditure may affect basis under the applicable rules. Keep the loan statement and the contractor invoice separate; treating both as additions would count the same spending twice. Likewise, mortgage principal payments are not a second purchase of the property.
Use the Nevada seller net-sheet guide for the closing-cash side of the decision. Give the tax preparer the same proposed contract and cost assumptions. When a price or concession changes, revise both worksheets so the estimated tax reserve and the amount available for your next home remain consistent.
Who Qualifies for the $250,000 or $500,000 Home-Sale Exclusion?
Section 121 concerns a qualifying main home, not every residential property an owner sells. According to IRS Topic 701, the general ownership and use requirements each cover at least two years within the five years ending on the sale date. The qualifying periods need not be the same continuous two-year block, but both tests must be satisfied within the relevant window.
For eligible married joint filers, either spouse may satisfy ownership while both must satisfy use. Both also need to satisfy the look-back requirement for the full joint exclusion: a prior exclusion within the preceding two years can change the result. Marriage by itself does not turn one person's eligibility into an automatic $500,000 allowance. A newly married couple should review each person's residence and prior-sale history separately.
The IRS considers facts and circumstances when someone uses more than one home. Time spent there, tax-return addresses and other records matter. A mailing address, Nevada driver's license or homestead declaration alone does not replace the federal occupancy analysis. A condominium can qualify as a main home just as a detached house can; its building type does not determine the exclusion.
There are additional restrictions and exceptions, including certain properties acquired through a 1031 exchange and some service-related absences. Treat the table as a screening checklist before completing the IRS worksheets. For a Henderson property with several owners, identify each legal owner's interest and ask the preparer which return reports each share. Do not apply one owner's exclusion automatically to another owner's gain.
| Question | Individual full exclusion | Married joint full exclusion |
|---|---|---|
| Maximum eligible gain excluded | Up to $250,000 | Up to $500,000 |
| Ownership | Generally two of the preceding five years | Either spouse generally meets ownership |
| Use as main home | Generally two of the preceding five years | Both spouses generally meet use |
| Prior excluded sale | Generally no exclusion in preceding two years | Both spouses meet look-back for full amount |
| Rental or business history | Review depreciation and nonqualified use | Same review; joint filing does not erase it |
Which Purchase Costs Belong in Your Adjusted Basis?
Begin with the acquisition documents rather than the current mortgage balance or an online value estimate. According to IRS Topic 703, basis generally starts with cost and changes for events such as qualifying improvements, depreciation and certain reimbursements. A home received by gift or inheritance may start under different rules, so the amount a previous owner paid is not always the right opening entry.
Publication 523 distinguishes eligible acquisition charges from financing expenses. Certain title, legal, recording, survey and transfer-tax costs may enter basis. Mortgage points, lender-required appraisal costs, credit-report fees and refinancing fees generally do not belong in the home's basis. Amounts deposited into escrow for future insurance or taxes are not automatically acquisition costs merely because they appear on the settlement statement.
Take a hypothetical purchase: $206,000 for the home, $6,000 in assumed eligible acquisition costs, a $45,000 pool and casita, and an $18,000 roof. With no other adjustments, basis totals $275,000. The improvements total $63,000; the separate $6,000 is acquisition cost. At a $470,000 sale with $33,000 of selling expenses, amount realized is $437,000 and gain is $162,000. Eligibility must still be checked before calling that gain excluded.
Create a ledger with the invoice date, description, amount, supporting document and the preparer's treatment. For a North Las Vegas home, county records and the purchase file may help identify the property and transaction, but they do not certify every tax-basis entry. Preserve uncertain items for review instead of rounding the total upward to match a desired tax outcome.
When Do Improvements Reduce Gain Without Creating a Dollar-for-Dollar Tax Saving?
A qualifying improvement increases basis; it does not usually reduce tax by the full amount spent. According to IRS Publication 523's improvement rules, improvements generally add value, extend useful life or adapt a home to a new use. Routine maintenance usually differs, although repair work performed as part of an extensive remodeling or restoration project can receive different treatment.
Suppose an otherwise eligible seller has $280,000 of gain before recognizing $30,000 of documented qualifying improvements. The gain would fall to $250,000, assuming no offsets or other adjustments. That could eliminate $30,000 of taxable gain for a seller entitled to the full individual exclusion. At an assumed 15% federal rate on that entire amount, the arithmetic saving is $4,500, not $30,000. If all the gain was already excluded, those improvements might produce no additional federal capital-gains saving.
Do not count improvements that have been removed, the value of your unpaid labor, or costs already deducted where the tax rules prevent double counting. Energy credits, subsidies, insurance reimbursements and casualty adjustments can also affect the basis entry. A solar invoice should travel with the relevant credit and ownership documents; a leased system is not the same transaction as buying the equipment outright.
Use the home-improvement planning guide to consider resale practicality, then let the preparer determine tax treatment. A project can be useful to a buyer without recovering its full cost in price. Before spending solely to reduce a future gain, compare the actual cash outlay, likely selling benefit and modeled tax effect. Keeping an existing receipt is different from undertaking a new renovation to obtain a deduction.
How Do Holding Periods, Occupancy Dates and Early Moves Interact?
The long-term holding-period test and the home-sale exclusion are separate clocks. According to IRS Topic 409, an asset generally must be held more than one year for long-term treatment. Failing to reach two years of home occupancy does not automatically make the gain short-term. A sale after eighteen months can involve long-term gain while failing the ordinary full-exclusion requirements.
A qualifying work, health or unforeseen circumstance may permit a reduced exclusion. The work-location safe harbor is more specific than moving fifty miles: the new workplace generally must be at least fifty miles farther from the home than the old workplace. Publication 523 also addresses someone without a previous workplace and qualifying events affecting certain other residents. A voluntary move for a preferred climate should not be treated as automatically meeting those exceptions.
For a reduced exclusion, the IRS worksheet uses the shortest applicable ownership, residence and prior-exclusion interval, divided by twenty-four months or 730 days. In an invented individual case where all applicable intervals permit twelve months and a qualifying reason exists, $250,000 multiplied by 12/24 produces a $125,000 maximum. Joint filers calculate the spouses' eligible amounts separately rather than assuming the same dates for both.
Put purchase, move-in, move-out, earlier excluded sale and proposed closing dates on one calendar. Keep the employment or health documentation that supports the reason for an early sale. Ask the preparer to evaluate the actual closing date before accepting a schedule. Our leaving-Las-Vegas cost guide addresses the broader move budget; this timing analysis determines a different part of the sale decision.
Which Federal Capital-Gains Thresholds Apply to a 2026 Sale?
Use the sale's tax year and filing status. According to IRS Revenue Procedure 2025-32, Section 4.03, the 2026 maximum zero-rate amount is $49,450 for single filers and $98,900 for married joint filers. These are taxable-income thresholds for the ordinary long-term capital-gains structure, not additional home-sale exclusions or limits on the property's selling price.
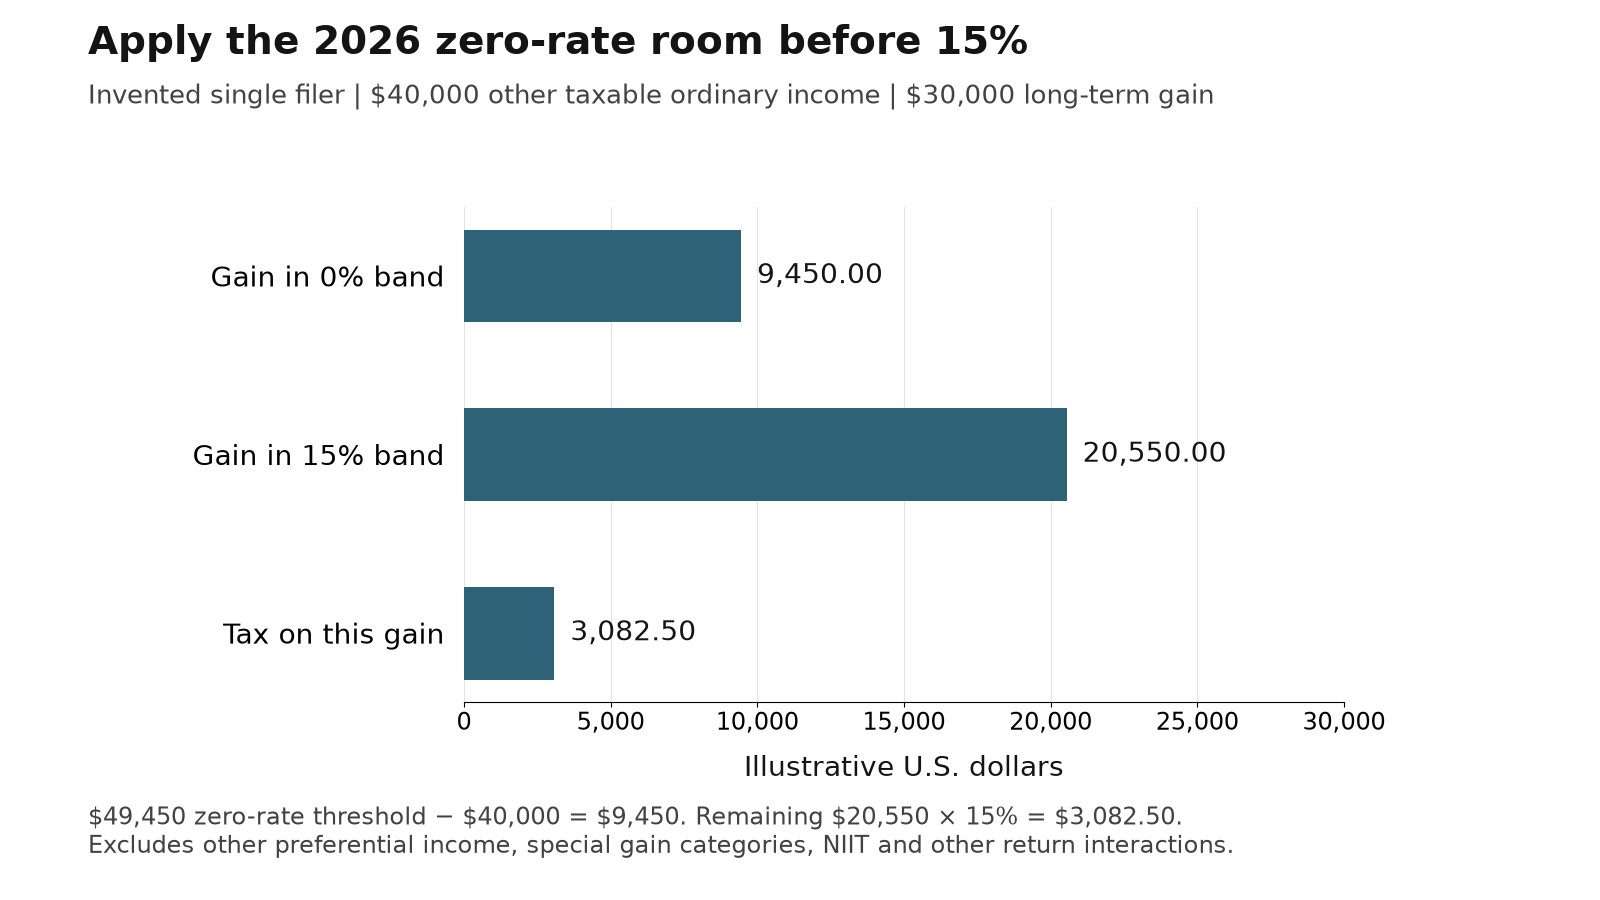
Taxable gain generally sits alongside the rest of the return's taxable income. A simplified single-filer example assumes $40,000 of other taxable ordinary income and $30,000 of ordinary long-term gain after any exclusion, with no other preferential income or special gain categories. The zero-rate room is $9,450. The remaining $20,550 is in the 15% band, producing $3,082.50 under those assumptions. Applying 15% to the full $30,000 would incorrectly produce $4,500.
The table does not calculate ordinary income tax, the Net Investment Income Tax, unrecaptured Section 1250 gain, capital-loss netting or every worksheet interaction. Those distinctions matter for a seller who also has stock gains, business income or prior depreciation. A property's location in Summerlin does not assign its owner to a federal bracket; the return determines that result.
IRS Topic 409 still showed 2025 figures, such as $48,350 for single filers, when it was checked on November 1, 2026. Its holding-period explanation is useful, but don't reuse those brackets for a 2026 sale. Save the preparer's calculation with its tax-year label and update it if the expected sale crosses into another year. A December contract followed by a later closing needs an actual tax-year review rather than an assumption based on the listing date.
| Filing status | Maximum income for 0% band | Maximum income for 15% band |
|---|---|---|
| Single | $49,450 | $545,500 |
| Married filing jointly / qualifying surviving spouse | $98,900 | $613,700 |
| Married filing separately | $49,450 | $306,850 |
| Head of household | $66,200 | $579,600 |
When Can the Additional 3.8% Investment-Income Tax Apply?
The Net Investment Income Tax requires its own calculation. According to the IRS NIIT questions and answers, individual thresholds include $200,000 of modified adjusted gross income for single filers, $250,000 for married joint filers and $125,000 for married separate filers. These thresholds are not indexed for inflation. Taxable income used for capital-gains brackets and modified adjusted gross income used here are different measures.
For individuals, the tax generally applies at 3.8% to the lesser of net investment income or the amount by which modified adjusted gross income exceeds the relevant threshold. Gain excluded under Section 121 does not enter NIIT merely because the seller has high wages. Conversely, gain that remains taxable may be included in net investment income, subject to the applicable rules and offsets.
An invented single filer has $220,000 of modified adjusted gross income and $60,000 of net investment income. The threshold excess is $20,000, so the smaller base is $20,000 and the illustrated NIIT is $760. Multiplying the whole $60,000 by 3.8% would produce $2,280 and overstate this example. The result could differ if the seller has other investment income, deductions or a different filing status.
Ask for NIIT as a separate line in the preparer's estimate instead of adding a universal 3.8% surcharge to every sale. This is especially useful when a luxury property sale occurs in a year with a business sale, retirement distribution or other substantial income. The house price alone does not establish liability, and a large excluded gain alone does not establish it either. Preserve the income assumptions used to produce the estimate.
Does Nevada's Lack of Income Tax Eliminate Every Sale Tax?
Nevada does not impose an individual state income tax, according to the Nevada Department of Taxation. That does not make every amount charged at a home closing disappear. Federal income tax, transfer tax, property-tax adjustments and another state's income-tax jurisdiction address different obligations. A seller needs to identify each rather than labeling the transaction simply tax-free.
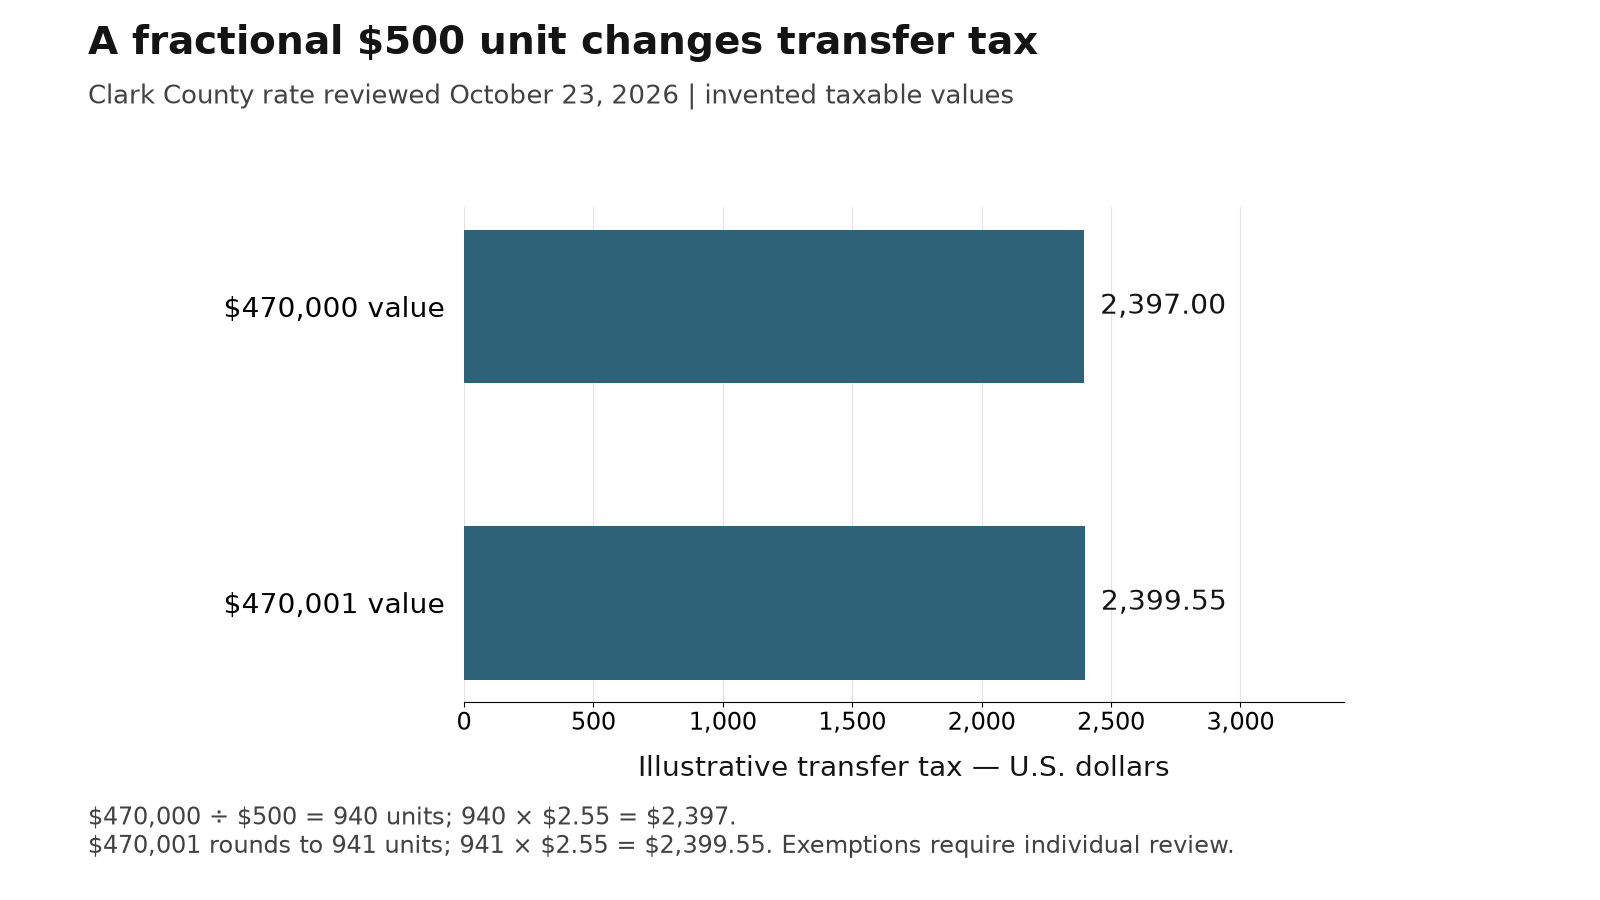
According to Nevada's real-property transfer-tax guidance, the base rate is $1.95 per $500 of value or fraction thereof when applicable, with an additional $0.60 in Clark County. The resulting Clark County rate is $2.55. At an invented taxable value of $470,000, 940 units produce $2,397. At $470,001, rounding to 941 units produces $2,399.55. Exemptions, declared taxable value and the allocation of payment require the actual closing file.
Another state's residency rules can still matter. California's Office of Tax Appeals said in Appeal of Catanzarite, a 2023 nonprecedential opinion, that California residents are taxed on their entire income regardless of source, and that domicile is presumed to continue until shown to have changed. A Nevada address on a return was not enough there to show the taxpayer had left. A Nevada property address does not automatically remove a California resident's filing obligation, and moving does not by itself set the residency date you want.
A headline top rate can't tell you what one seller would save. Use an actual residency and return analysis when moving between California and Las Vegas. Give your preparer the move dates, property locations and income history. Ask the closing professional for transfer tax separately so it is neither omitted from cash planning nor confused with the federal gain calculation.
How Much Have Las Vegas Home Prices Risen Since 2016?
Las Vegas MLS closings show how far prices have moved, and why long-time owners now run into the exclusion. Counted by closing date, the median residential sale in Las Vegas, Henderson, North Las Vegas and Boulder City was $212,000 in 2016, $365,000 in 2021, $443,000 in 2025 and $445,000 for January through September 2026. The $233,000 difference between 2016 and 2026 is about 110% of the 2016 median.
That comparison concerns two sets of transactions. It does not establish that a specific house appreciated by that amount, nor that an owner's gain sits near an exclusion cap. For scale, $233,000 is below the $250,000 single-filer maximum before any selling expenses or improvements, but it measures no individual seller's gain. An expensive home bought recently may have less gain than a modest home held for decades, and a higher median says nothing about exclusion headroom without the seller's basis and eligible expenses.
For an actual listing decision, compare recent relevant closed sales and your property's condition in Las Vegas or Boulder City, then use your own tax records. Inventory pages show available properties, not a closed-sale analysis. Use the table below for context, and get a dated property-specific estimate before accepting a price.
| City | 2016 median | January-September 2026 median | Change | 2026 closings |
|---|---|---|---|---|
| Las Vegas | $206,000 | $437,000 | +112% | 14,363 |
| Henderson | $256,348 | $492,500 | +92% | 4,359 |
| North Las Vegas | $192,000 | $417,000 | +117% | 2,363 |
| Boulder City | $238,238 | $468,000 | +96% | 178 |
How Would a $560,000 Henderson Sale Change for Different Sellers?
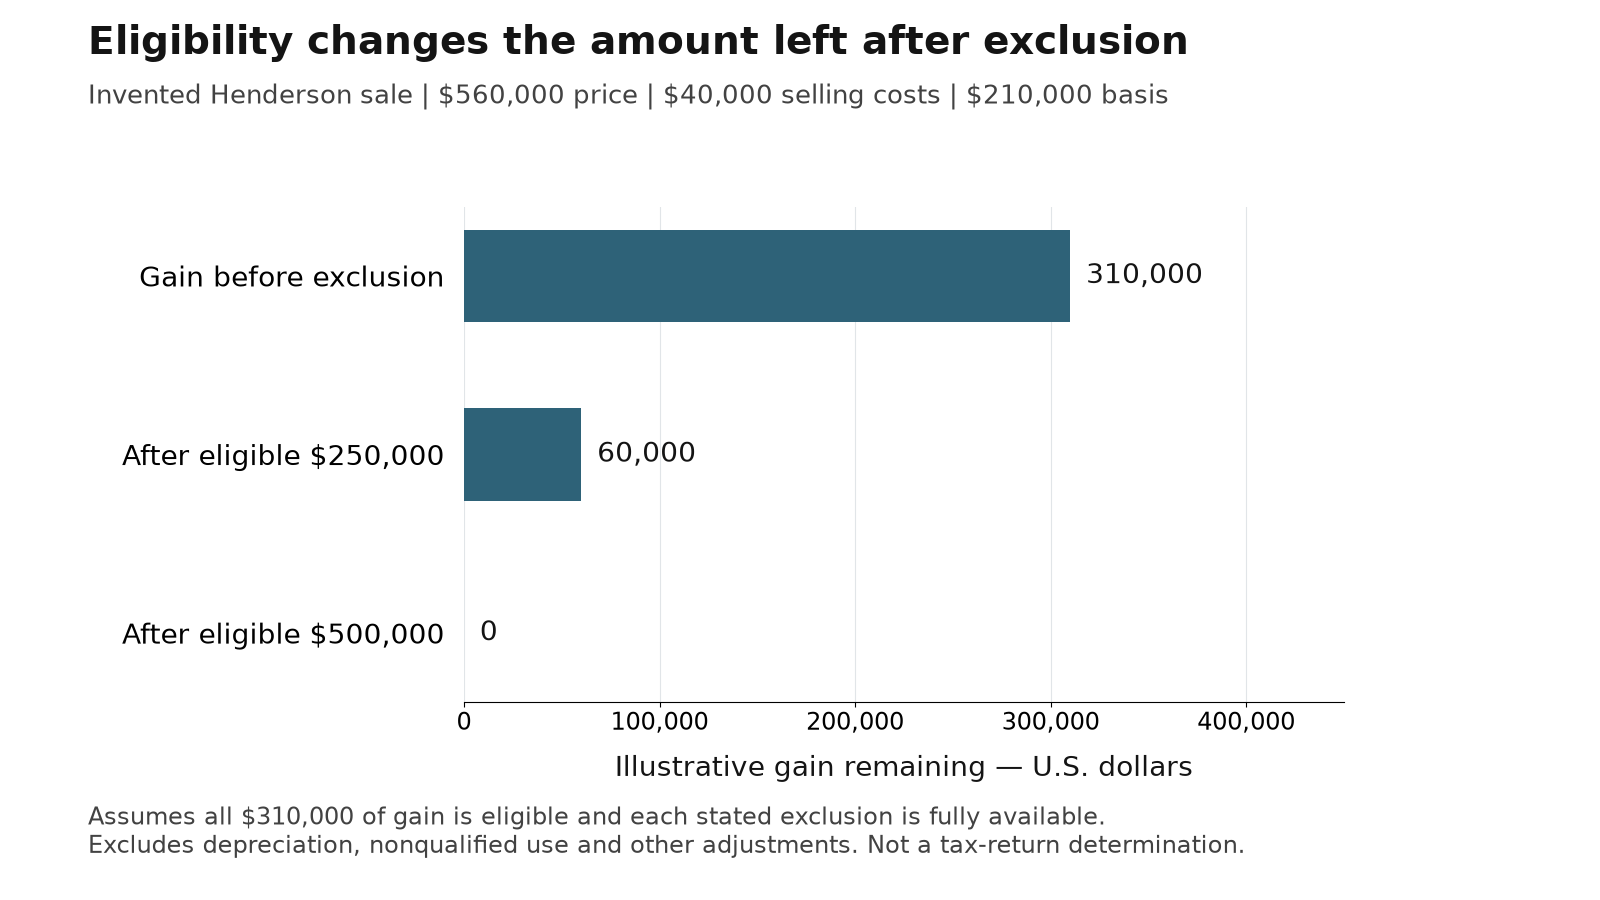
An invented Henderson example isolates the tax decision. The assumed purchase price is $180,000, documented improvements are $30,000, selling price is $560,000 and selling expenses are $40,000. With no additional basis adjustments, amount realized is $520,000 and adjusted basis is $210,000. The resulting gain is $310,000. These assumptions describe arithmetic, not an actual client or current market valuation.
If an individual qualifies for the full $250,000 exclusion and all the gain is eligible, $60,000 remains. If eligible married joint filers qualify for the full $500,000 exclusion under the same property assumptions, the eligible $310,000 could be excluded. If no full or partial exclusion applies, the calculation does not receive either allowance. Rental depreciation and nonqualified use can further change the eligible portion.
At an assumed 15% rate on the entire $60,000, the federal capital-gains component would be $9,000. At 20%, it would be $12,000; a zero-rate band or split bands can change it again. Those numbers are rate illustrations, not a statement that a single retiree necessarily owes $9,000. NIIT, other income, loss netting and any additional tax categories still need the return calculation.
This is why guard-gated properties and other higher-priced homes should not be assigned a tax reserve from price alone. Ask for a range based on documented eligibility and income assumptions, then compare that reserve with the cash needed for the next purchase. A tax difference may affect timing or spending, but it does not justify reducing the asking price mechanically by the exclusion amount.
What Changes If You Rented the Home Before or After Living There?
A qualifying main home can exclude up to $250,000 or $500,000 of gain under Section 121. A Las Vegas rental you never lived in can't exclude any, so its gain is generally taxable in the year of sale unless you defer it, as with a 1031 exchange. Mixed histories fall between the two, which is what the rest of this section covers.
| Question | Qualifying main home | Rental you never lived in |
|---|---|---|
| Section 121 exclusion | Up to $250,000 single, or $500,000 for eligible joint filers | None; the two-year use test isn't met |
| Rate on long-term gain | On gain above the exclusion: 0%, 15% or 20% under the 2026 thresholds above | The same 0%, 15% and 20% on gain that isn't depreciation, if held more than a year; net Section 1231 gain is generally long-term after any recapture of past 1231 losses |
| Depreciation | None, unless it had rental or business use | Basis falls by depreciation you deducted or could have deducted; that part of the gain is taxed at a maximum 25% |
| 3.8% NIIT | Excluded gain is out; taxable gain above the exclusion can count | Gain on investment real estate counts when modified adjusted gross income tops $200,000 single or $250,000 joint; ask your preparer if the rental is a nonpassive business |
| 1031 exchange | Not available for a personal residence | Available for qualifying investment property: 45 days to identify, and 180 days or the return's due date with extensions, if earlier, to receive |
| Nevada income tax | None | None; a resident of a taxing state may still owe that state |
| Clark County transfer tax | $2.55 per $500 of taxable value, unless exempt | The same |
| Reporting | Report if you get a Form 1099-S or have taxable gain; Form 8949 and Schedule D commonly apply | Reported on Form 4797, per IRS Publication 544 |
The answer turns on your occupancy dates, depreciation schedule, income and home state, so take those to your preparer. The 2026 rate table and NIIT section are above, and the depreciation and 1031 sections follow.
Rental timing can affect two separate questions: whether the ownership and use tests are satisfied, and how much gain is eligible for exclusion. According to IRS Publication 523, certain periods after 2008 when neither the owner nor a qualifying spouse used the property as a main home constitute nonqualified use. Gain allocated to those periods may remain taxable even when the seller later satisfies the basic two-year tests.
The order of events matters. Buying a rental and later moving into it is not automatically equivalent to living there first and renting after moving out. The publication provides an exception from nonqualified-use allocation for the relevant period after the last main-home use within the five-year period ending at sale. That exception does not erase depreciation or extend the ordinary ownership and use window indefinitely.
An owner who lived in the property for several years and then rented it may still qualify when selling within the applicable window. But “sell within three years” is only a rough planning shorthand, not a substitute for exact occupancy dates and all the other requirements. Earlier absences, another excluded sale, separate business space or service-related rules can change the analysis. Ask the preparer to compare realistic proposed closing dates.
Before choosing to sell or rent a Las Vegas home, assemble leases, move dates, vacancy periods and depreciation schedules. Model both the carrying costs and the future sale treatment. A favorable rent estimate does not establish that the eventual gain will be fully excluded. Conversely, a past rental period does not automatically mean the entire gain loses every potential home-sale benefit. A dated occupancy timeline is the most useful starting evidence.
How Do Depreciation and Home-Office Deductions Affect the Sale?
Depreciation requires separate attention even if you expect the rest of the gain to fit under an exclusion. According to IRS Publication 523, gain attributable to depreciation allowed or allowable for business or rental use after May 6, 1997 cannot be excluded under Section 121. Failing to claim a deduction does not necessarily avoid the basis adjustment or the later consequence.
According to IRS Topic 409, the unrecaptured Section 1250 portion of gain has a maximum 25% rate. That is a special treatment for the relevant portion, not an automatic additional 25 percentage points stacked on top of the ordinary long-term rate on the same dollars. Additional depreciation subject to ordinary-income recapture and other special cases require the relevant worksheets. NIIT may separately apply when its conditions are met.
If an invented sale has sufficient recognized gain and $120,000 belongs in the unrecaptured Section 1250 category, multiplying by the 25% maximum yields $30,000. This is an upper-rate arithmetic illustration for that portion, not a guaranteed bill. The actual calculation depends on the taxpayer's income and the property's complete history; a loss or a different allocation changes the question.
The IRS simplified home-office guidance states that simplified-method years do not produce home depreciation or later recapture for those years. Earlier regular-method years do not vanish when a taxpayer switches methods. Send all depreciation schedules and home-office records to the preparer, including years handled by another accountant. A sale estimate built from only the latest return may omit part of the property's tax history.
Could a 1031 Exchange Help, and What Does It Not Do?
A replacement purchase does not automatically shelter a primary-home gain. According to the IRS real-estate exchange guidance, Section 1031 concerns qualifying real property held for investment or business use. Real property held primarily for sale does not qualify. Buying another personal residence with the proceeds of the old one is not, by itself, an exchange that defers tax.
For a qualifying deferred exchange, the IRS Form 8824 instructions require identification within forty-five days and receipt within 180 days or the return's due date including extensions, whichever is earlier. The clocks run from the relevant transfer; the 180-day period does not begin after the forty-five-day period finishes. A qualified intermediary arrangement has its own requirements, and receiving cash or other non-like-kind property can leave recognized gain.
A mixed-use property or a former main home can involve both Section 121 and Section 1031. That is not permission to recast every home sale as an investment transaction. The IRS instructions expressly address the interaction, including circumstances where the relinquished property no longer serves as the principal residence at the exchange date. The property's actual use and the transaction structure need professional review before closing.
Use the dedicated Nevada 1031 exchange guide for identification, intermediary and replacement-property decisions. This homeowner guide's task is to recognize when specialist planning is needed. Have the tax adviser and appropriate exchange professional review a proposed structure before funds are disbursed. An exchange can defer qualifying gain; it does not promise that all taxes, closing expenses or future obligations disappear, and it should not drive an unsuitable replacement purchase.
Why Do Inheritance, Divorce and a Spouse's Death Need Different Records?
Not every seller starts with a purchase-price basis. According to IRS Publication 523, inherited property generally uses the applicable date-of-death fair market value or an eligible alternate valuation, subject to its specific rules. A gift generally raises a different basis question. Do not treat a transfer by gift as an inheritance simply because the recipient eventually becomes the sole owner.
Nevada's community-property context can matter after a spouse dies. The IRS describes circumstances in which both halves of qualifying community property receive a basis adjustment, subject to estate-inclusion conditions. Joint ownership alone does not establish that every property has that treatment. The deed, marital-property characterization, estate documents and valuation evidence should be examined together. Preserve the appraisal and relevant estate-return materials rather than substituting today's listing estimate.
Divorce can involve carryover basis and special ownership or residence rules. A settlement payment to a former spouse should not be assumed to create the same basis result as an unrelated open-market purchase. Provide the decree, transfer instruments and both parties' available acquisition and improvement records. Also disclose whether either person previously used a home-sale exclusion during the relevant period.
The Las Vegas inherited-property guide addresses the separate sale-authority and estate process. For this tax decision, establish who owns what interest, how that interest was acquired and which records support basis. A surviving spouse may also have a special exclusion opportunity subject to timing and eligibility conditions. Review it promptly with the preparer rather than assuming that filing as a single person necessarily determines the only available maximum.
What Should You Assemble Before Listing and Before Filing the Return?
Build one sale file that the closing professional and tax preparer can reconcile. Include the acquisition settlement statement, ownership records, improvement ledger, reimbursement and credit records, occupancy timeline, prior exclusion details and rental schedules. Add the proposed sale contract and a cost estimate, then replace estimates with the final settlement statement after closing. Mark which figures remain assumptions so an early estimate is not mistaken for a final tax return.
According to IRS Topic 701, receiving Form 1099-S generally requires reporting the sale even when gain is excludable. Taxable gain also requires reporting. Form 8949 and Schedule D commonly apply, while business use, depreciation or installment terms can require additional forms. A reporting obligation is different from owing tax; do not discard the form because the estimated exclusion covers the gain.
According to Publication 523's record guidance, basis records generally remain relevant until three years after the due date of the return for the year of sale. That is more precise than throwing documents away three years after closing. Other circumstances can require longer retention, so have the preparer set the schedule. Also discuss withholding or estimated payments when a taxable sale changes the year's expected liability.
For the real-estate portion, our seller resources and contact page can help organize a property-specific pricing and closing-cost discussion. Southern Nevada's office number is (702) 637-1759. Bring the tax professional's eligibility and reserve assumptions into that discussion. The useful outcome is a sale plan with documented costs, dates and responsibilities, not a promise that every seller will close without a tax bill.
Frequently Asked Questions
Is the $250,000 home-sale exclusion based on the sale price?
No. It concerns eligible gain after the amount realized and adjusted basis are calculated. A $600,000 selling price does not itself mean $350,000 is taxable. Your purchase history, eligible costs, improvements, depreciation and exclusion qualifications determine the result. Use the property records, not price alone.
Does paying off my mortgage reduce capital gain?
The payoff reduces available closing cash but does not ordinarily reduce the gain calculation. Gain uses selling price, selling expenses and adjusted basis. Qualifying improvements financed with borrowed money may affect basis, but the loan payoff itself is a different item. Avoid counting the same expenditure twice.
Do married sellers automatically receive a $500,000 exclusion?
No. Full joint eligibility generally requires either spouse to meet ownership and both to meet residence and look-back requirements, with other restrictions and exceptions considered. If the full joint amount is unavailable, evaluate each spouse's circumstances using the IRS worksheets instead of assuming no benefit or the full maximum.
If I sell after eighteen months, is the gain short-term?
Not necessarily. General long-term treatment requires holding the property more than one year. The full home-sale exclusion usually requires a separate two-year ownership and residence analysis. A qualifying early-sale reason may allow a reduced exclusion. Exact dates and the property's history still matter.
Can I owe tax when the gain is less than $250,000?
Yes. You might not qualify for the exclusion, or some gain may relate to depreciation or nonqualified use. The exclusion maximum is not a blanket exemption for every residential sale. Conversely, taxable ordinary long-term gain can fall in a zero-rate band depending on the full return.
Does buying another house eliminate the tax?
A replacement personal-home purchase does not automatically eliminate gain on the first sale. Section 121 has its own eligibility rules. Section 1031 applies to qualifying business or investment real property under a different structure. Review any proposed exchange before closing rather than trying to create one after receiving proceeds.
Does Nevada charge capital-gains income tax or transfer tax?
Nevada has no individual state income tax. A Clark County transfer may still incur real-property transfer tax at $2.55 per $500 of taxable value or fraction thereof, subject to exemptions. Federal income tax and another state's jurisdiction can also matter. These are separate calculations with different bases.
Must I report the sale if all eligible gain is excluded?
Generally, a Form 1099-S means the sale must still be reported. Taxable gain and certain other circumstances also trigger reporting. Give the preparer the closing statement and all tax forms so the exclusion and reporting are reconciled. Keep basis records under the applicable retention rules.
Which Sources and Review Limits Support This Guide?
Rules were checked November 1, 2026. IRS Publication 523 and the Form 8824 instructions are their 2025 editions, the latest available; 2026 long-term capital-gains thresholds come from Revenue Procedure 2025-32. Market figures are Las Vegas MLS closings pulled through Repliers, counted by closing date. All worked examples are invented arithmetic, not client results, quoted fees or tax-return determinations.
- IRS Publication 523: eligibility, basis, rental use and sale reporting
- IRS Topic 701: sale of your home
- IRS Topic 703: basis of assets
- IRS Publication 527: residential rental property, basis and depreciation
- IRS Publication 544: Section 1231, Section 1250 and Form 4797
- IRS Topic 409: holding periods and capital-gain categories
- IRS Revenue Procedure 2025-32: 2026 adjusted amounts
- IRS: Net Investment Income Tax questions and answers
- IRS: simplified home-office method
- IRS: real-estate like-kind exchanges
- IRS Form 8824 instructions: exchange timing and home-sale interaction
- Nevada Department of Taxation: individual income tax
- Nevada Department of Taxation: real-property transfer tax
- California Office of Tax Appeals: Appeal of Catanzarite, 2023-OTA-511, nonprecedential
General information, not individualized tax or legal advice. Nevada Real Estate Group, brokered by LPT Realty, license S.181401.