Henderson can be a good place to retire when the home, ongoing expenses, healthcare arrangements and daily routine fit your needs. Nevada's lack of an individual state income tax is useful, but it does not tell you whether a particular house is affordable or whether a needed specialist will accept your insurance. A retirement move works better when those questions are settled before the purchase.
This guide focuses on the Henderson decision: comparing communities, replacing advertised starting prices with a household worksheet, checking the property-tax bill, arranging care and testing ordinary life. Figures and public sources were reviewed October 22, 2026. The examples are transparent planning calculations, not measured retiree spending, home-price estimates or advice to withdraw a particular amount from savings.
Nevada Real Estate Group has closed more than 9,600 transactions, and helping retirees right-size into Henderson is one of the things we do most.
Henderson can suit retirees who want Southern Nevada community choices and can manage housing costs, healthcare logistics and summer heat. Nevada has no individual state income tax. Clark County's 3% primary-residence property-tax abatement has eligibility conditions and exceptions; it does not cap every ownership cost. Compare actual homes, insurance networks, HOA documents and a complete household budget before choosing Henderson over another retirement destination.
- Start with your income and actual property expenses; there is no universal Henderson retirement budget.
- Confirm the primary-residence tax abatement and separate every HOA or assessment charge.
- Verify age, occupancy, guest and amenity rules for the specific association.
- Arrange insurance and appointments before relying on a nearby hospital.
- Test summer living, daily routes and a backup transportation plan before committing.
Is Henderson a good place to retire for your daily routine?
The strongest reason to choose Henderson is a good match between a specific home and the life you intend to lead. Start with an ordinary week: where you buy groceries, which clinicians you see, how you spend time outside the house and how often you visit family. Then look at homes that make that routine practical. A citywide retirement ranking cannot answer those address-level questions.
Use a short list of requirements you can observe. Examples include a bedroom and bathroom on the entry level, manageable yard work, a place to pursue a particular hobby, a workable route to an established doctor and enough cash remaining after the move. Separate essential requirements from preferences. A view might be attractive, but it should not quietly displace a requirement for a step-free entrance or an affordable recurring payment.
The Henderson community overview helps orient the search, while the broader Las Vegas retirement relocation guide covers valley-wide planning. Henderson and Summerlin are different search areas; compare actual destinations and property features rather than treating either name as a guarantee of convenience.
Make the shortlist reversible while research is incomplete. Keep a second community and a rental option under consideration until healthcare, housing and daily access are resolved. If the move only works with uninterrupted driving, unusually low maintenance costs or an unconfirmed insurance arrangement, identify that dependency now. A good fit should remain workable when a normal inconvenience occurs, not only during an attractive model-home tour.
How much money do you need to retire in Henderson?
Build the answer from your actual retirement income and the expenses of the home you are considering. A paid-off house still has taxes, insurance, maintenance and possibly association assessments. A financed house adds principal and interest. Neither case can be described accurately by one citywide annual spending range without knowing the household's circumstances.
The following worksheet, prepared as of October 22, 2026, uses deliberately hypothetical monthly inputs. It is an arithmetic example for a household with no mortgage or rent payment, not an estimate of typical Henderson costs. Substitute written quotes and your own spending records before using the result. Healthcare includes a placeholder for the household's chosen coverage and expenses; it is not a Medicare quote.
| Expense | Assumed monthly amount | Evidence to substitute |
|---|---|---|
| Property tax, homeowners insurance and association charges | $650 | Parcel bill, insurance quote and association documents |
| Home maintenance reserve | $350 | Inspection, equipment ages and replacement estimates |
| Utilities and communications | $350 | Address-specific usage and service quotes |
| Food and household purchases | $850 | Recent household spending |
| Healthcare | $800 | Coverage premiums and personal expense allowance |
| Transportation | $450 | Vehicle, insurance, maintenance and ride costs |
| Recreation and travel | $500 | Chosen activities and planned trips |
| Other expenses and contingency | $350 | Personal commitments and extra cushion |
| Total before mortgage or rent | $4,300 | $51,600 for twelve months using these assumptions |
An additional hypothetical $1,600 monthly principal-and-interest payment increases this worksheet to $5,900 monthly, or $70,800 annually. Those totals are calculations, not a recommendation or an affordability finding. Avoid counting taxes and insurance twice if a quoted mortgage payment includes escrow.
Compare spendable income after the deductions that actually apply, rather than substituting an average Social Security benefit for your award amount. Keep moving costs, purchase closing costs and major initial repairs outside the recurring monthly total. The Henderson cost-of-living guide supplies additional budgeting context; your chosen home and coverage still need their own figures.
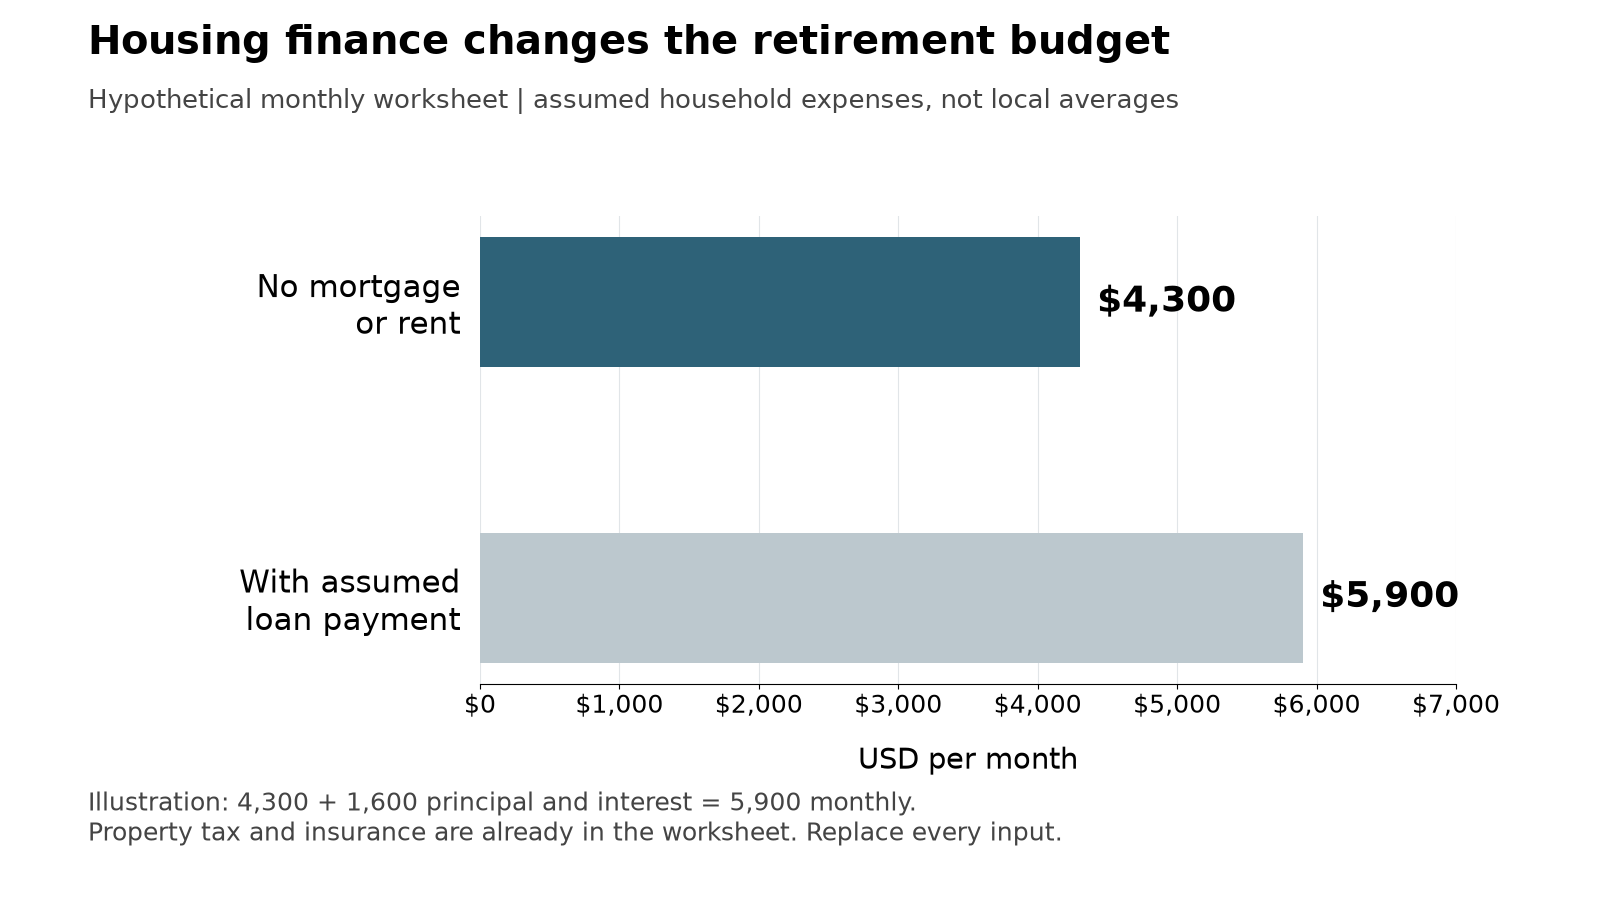
How do Nevada income taxes affect a retirement move?
According to the Nevada Department of Taxation, Nevada does not impose an individual state income tax. Consequently, Nevada does not impose that tax on a resident's Social Security benefits, pension income or retirement-account distributions. Federal taxes and any applicable obligations to another state are separate questions. Sales and property taxes also remain part of living here.
The practical comparison is your projected total tax position before and after the move. Do not multiply every dollar of retirement income by another state's highest published tax bracket. A household's filing status, taxable income, deductions and income sources matter, and a headline marginal rate does not establish the tax actually paid. Use a qualified tax professional's calculation when tax savings materially affect the home budget.
Moving from California needs particular care. According to the California Franchise Tax Board's residency guidance, part-year residents generally owe California tax on worldwide income during the resident period and California-source income during the nonresident period. Rental income from California property is among the listed California sources. A Nevada address does not by itself erase those obligations.
For a household keeping a former home, write down whether it will be sold, rented or retained for personal visits, then obtain advice on the consequences of that exact plan. Keep records of the actual move and relevant financial events. A simple day-count slogan is not a substitute for determining residency under the rules that apply. Treat any anticipated savings as provisional until the calculation and move facts support them, especially before committing those savings to a larger mortgage or recurring community fees.
Does the 3% property-tax abatement protect every retirement home?
According to the Clark County Assessor's tax-abatement explanation, the partial abatement applies a 3% cap to the tax bill of an eligible owner's primary residence. Only one Nevada property can be designated as the primary residence. The county describes a cap of up to 8% for non-owner-occupied property and first-year exceptions for new construction or a change of use. The rule concerns the tax bill, not a 3% tax rate on the purchase price.
The same county page says a recorded ownership document removes the owner-occupied abatement designation and requires a new postcard to retain the 3% treatment for the next year. Obtain the parcel record and ask the Assessor which designation and filing apply to your purchase. Do not assume the seller's owner-occupied status automatically carries over, or assume that buying the house resets its tax bill to a fixed percentage of your offer.
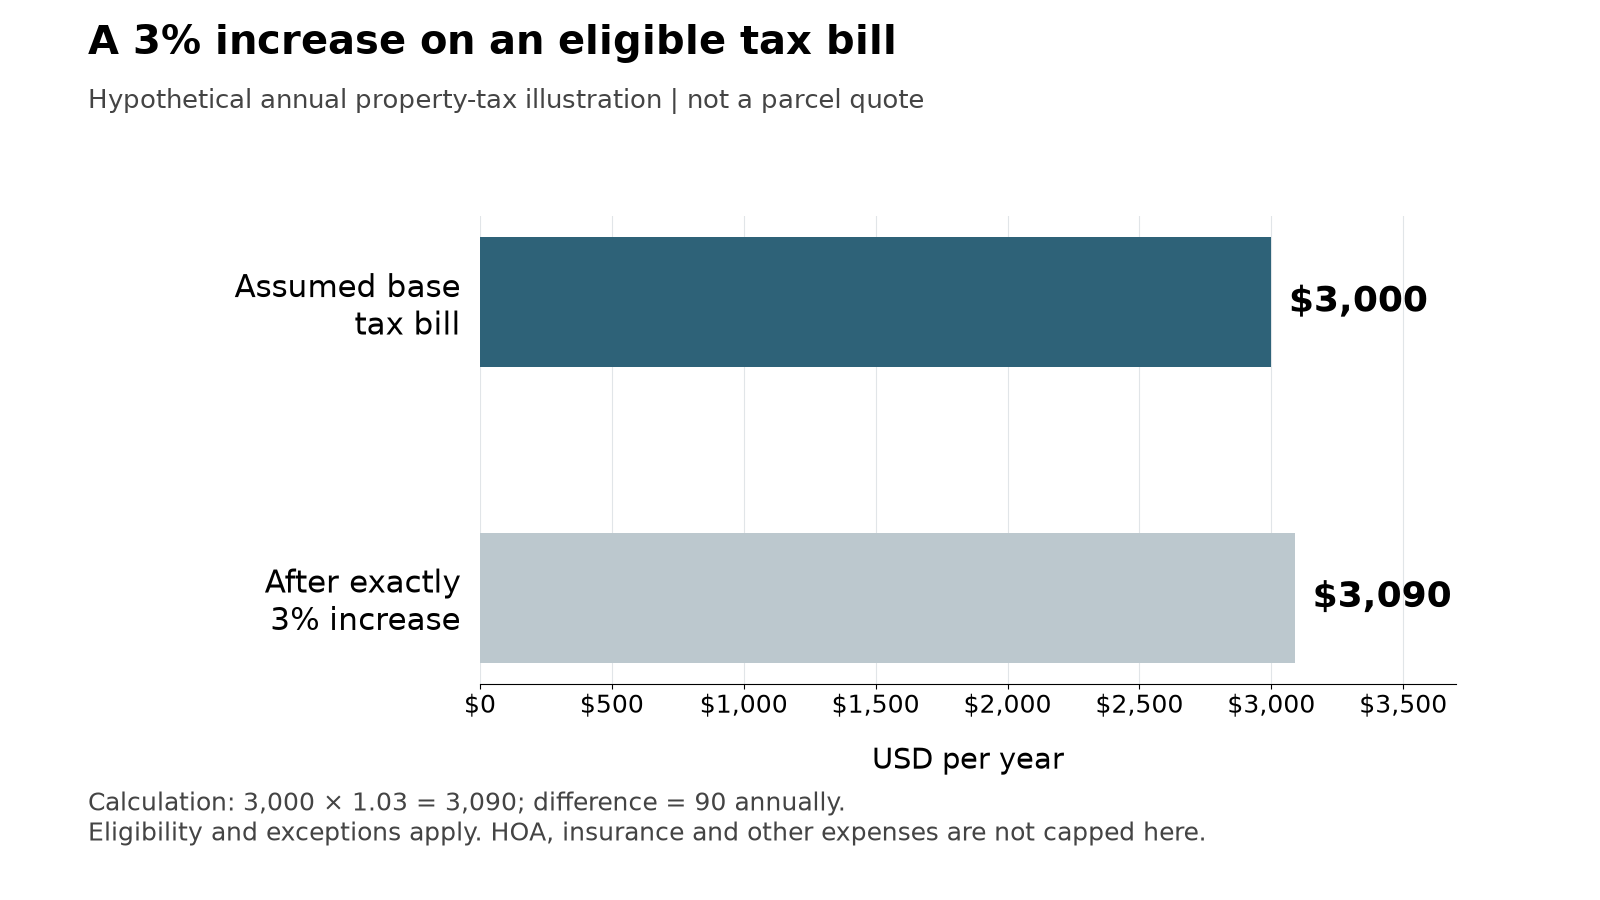
An illustrative calculation prepared as of October 22, 2026 helps explain the distinction: if an otherwise eligible $3,000 annual tax bill increased by exactly 3%, the result would be $3,090, a $90 annual difference. This example assumes qualification and no applicable exception. It predicts neither a particular parcel's bill nor the actual annual increase.
HOA assessments, insurance premiums, repairs and utilities are outside that example. A modest tax increase can coexist with a much larger increase in another expense. Check homestead protection separately from property-tax abatement; filing one document is not evidence that all protections have been established. Our buyer resources help organize the property documents, but the county's parcel-specific determination should drive the tax line in your worksheet.
Which Henderson communities should you compare for retirement?
Compare communities by features you will use and documents you can verify. The names in the table are research starting points, not a ranking or a claim that every property has the same age rules, gate access or expenses. A larger master plan and a separately governed age-qualified neighborhood within it are different things. Identify the exact association before drawing conclusions from a listing's marketing description.
According to Solera at Anthem's association amenities page, its facilities include tennis, billiards and an indoor swimming pool. That supports evaluating those activities there; it does not establish current class availability, visitor privileges or every charge. Cadence's October 21, 2015 Heritage announcement specifically identified Heritage as an age-qualified neighborhood. It is historical evidence of the development's identity, not current new-home availability or pricing.
| Search area | Useful comparison | What could change the choice |
|---|---|---|
| Sun City Anthem | Compare individual floor plans, association responsibilities and the activities you intend to use. | Property condition, separate assessments, guest rules or a route that does not work for you. |
| Solera at Anthem | Review the association's published amenities and clubs against your own routine. | Actual access rules, class availability, ownership costs and maintenance responsibilities. |
| Sun City MacDonald Ranch | Obtain current association documents and compare specific homes before relying on general descriptions. | Resale inspection findings, current fees and the route to your destinations. |
| Heritage within Cadence | Distinguish Heritage's association and occupancy rules from the wider master plan. | Parcel-specific membership, available resale inventory and documented recurring charges. |
| Del Webb at Lake Las Vegas | Compare that specific neighborhood with other Lake Las Vegas properties. | Association layers, actual club access and the time needed for routine trips. |
Use the 55+ community hub and the Sun City Anthem guide for further orientation. Then verify the shortlist against current documents. If you also consider Inspirada or another broader master plan, do not infer age restrictions merely because some marketing mentions active living. Similarly, new construction describes the property, not automatic eligibility for a particular retirement community or its amenities.
What do 55+ occupancy rules actually mean?
According to 24 CFR 100.305, qualifying housing for older persons must generally have at least one person aged 55 or older in at least 80% of its occupied units. This is one element of the federal framework, not an automatic right for any household under 55 to occupy the remaining units. The regulation permits communities to determine age restrictions for those other units subject to the applicable requirements.
For a real purchase, ask for the current declaration, rules and written eligibility information from the actual association. Establish who may own the home, who may occupy it, how eligibility is documented and what restrictions apply to guests. A visiting grandchild, a younger spouse, a tenant and an adult family member moving in permanently are different situations. Do not treat a salesperson's informal summary as the complete occupancy rule.
The age designation also does not answer whether the development has controlled entry, whether a yard is maintained for the owner or whether a tenant receives recreation privileges. Those features arise from separate property and association arrangements. Compare them explicitly instead of using “55+” as shorthand for all of them.
Before an offer, write down the household arrangement you actually expect over the next several years, including extended visits and any likely support needs. Request clarification of that scenario without assuming an exception will be approved. If the documents do not fit the planned occupancy, look at other housing options. Retirement itself does not require living in an age-qualified community, and an otherwise suitable home outside one can remain on the shortlist.
How should retirees evaluate HOA dues and home maintenance?
Ask what each recurring charge pays for, who can change it and what maintenance remains your responsibility. A low advertised assessment can exclude a second association, a separate club membership, paid classes or work on the house itself. Conversely, a larger assessment may include services that you would otherwise purchase separately. The useful comparison is the total cost and actual responsibility, not which listing shows the smallest monthly HOA number.
Read the budget, available reserve information, current assessments, relevant meeting records and the resale documents with the professionals helping your purchase. Look for announced projects, maintenance obligations, restrictions affecting planned modifications and any disclosed special assessment. Obtain answers for the actual property and all associations that apply. Do not assume an optional golf or social membership automatically transfers with the deed.
The guard-gated community search and luxury community overview identify different property features from an age-qualified search. If you compare Anthem Country Club with a 55+ community, separate real-estate ownership, gate access, club privileges and any membership charges. Neither the word “club” nor a photograph of a golf course explains those contracts.
For maintenance, build an inspection list around roof condition, cooling equipment, drainage, irrigation, appliances and any private pool. A smaller floor plan may reduce some work without eliminating expensive replacements. Ask for repair estimates before assuming that a home is inexpensive to maintain. For travel, determine who will inspect the property, address a water leak and respond if cooling fails. “Lock-and-leave” should describe a specific workable arrangement, not a promise that an unoccupied house requires no attention.
How do you verify healthcare access before moving?
Start with your clinicians, medication needs, insurance plan and preferred pharmacy. A nearby hospital is useful information, but it does not establish that the physician you need is accepting patients, that a particular treatment is offered at that campus or that the provider participates in your exact plan. Ask the plan and provider directly, and keep the confirmation date with your moving checklist.
According to Dignity Health Nevada's regional information, its network serves Henderson and the wider Las Vegas Valley. The provider-directory notice itself advises calling the doctor's office to verify information. Separately, West Henderson Hospital's opening announcement records its December 3, 2024 opening at 1155 Raiders Way. These are facility and network facts, not guarantees of appointment availability, individual coverage or outcomes.
Several of my retiree clients specifically chose a home within ten minutes of a St. Rose Dominican campus, prioritizing proximity to care the same way younger buyers prioritize school zones — a sensible way to plan for the years ahead.
For your own home, measure the actual trip at the time you expect to travel, including parking and the walk to the clinic entrance. Identify a backup driver or transportation arrangement if you cannot drive temporarily.
Before the move, request instructions for transferring records, arranging refills and scheduling the first local appointment. If ongoing specialist care is essential, establish that continuity before closing rather than hoping the new location will solve it afterward. Keep emergency care, routine primary care and specialist follow-up as separate planning questions; one does not substitute for the others.
What Medicare costs and enrollment questions belong in the budget?
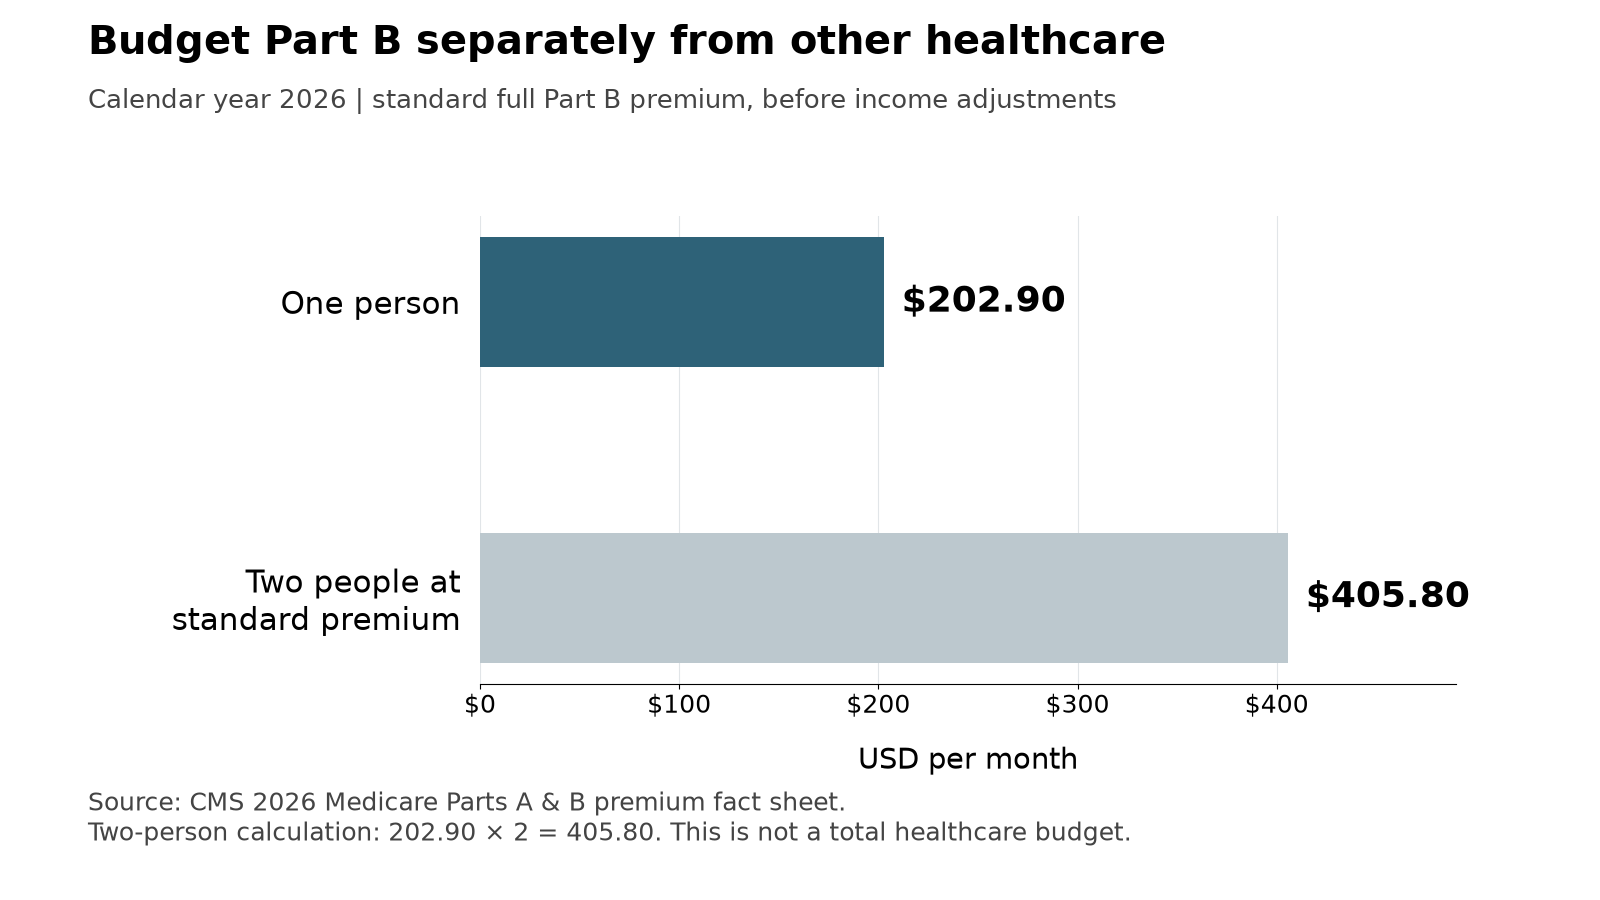
According to CMS's 2026 premium and deductible fact sheet, the standard Part B premium is $202.90 per person per month in calendar year 2026, and the annual Part B deductible is $283. Higher-income beneficiaries can pay an income-related adjustment. These national figures, checked as of October 22, 2026, apply to the stated year; they are neither a Henderson insurance quote nor a complete healthcare budget.
| Item | Verified figure or distinction | Household follow-up |
|---|---|---|
| Standard full Part B premium | $202.90 per person monthly | Confirm the premium actually applicable to each person. |
| Two standard Part B premiums | $405.80 monthly, calculated as two times $202.90 | Do not treat this as the household's total healthcare expense. |
| Part B deductible | $283 per beneficiary annually | Review coverage and other cost sharing separately. |
| Additional coverage and prescriptions | Costs depend on the coverage and personal circumstances | Compare actual plan documents, pharmacies and medications. |
| Moving outside an existing plan's service area | May create a Special Enrollment Period | Notify the plan and confirm timing, effective dates and replacement coverage. |
According to Medicare's Special Enrollment Period guidance, moving outside a plan's service area generally opens a chance to switch beginning with the move and continuing for two full months afterward. If you tell the plan before moving, that opportunity can begin in the month before the move. Confirm the rule for your circumstances and the coverage effective date with Medicare or the plan; this is not a statement that every type of supplemental coverage follows identical enrollment rules.
Create a separate line for each person's coverage rather than assuming a couple has matching costs or eligibility. Check dental, vision, hearing, prescriptions and anticipated support needs individually. A premium amount does not show every deductible, copayment or uncovered expense. Revisit the worksheet when official figures for the next calendar year and your selected plan become available; the 2026 amounts here should not be carried into a later year's budget as confirmed costs.
How should summer heat affect your retirement housing choice?
Evaluate summer comfort as part of the home and daily routine, not simply as a preference for sunshine. Ask how the cooling equipment performs, how old it is, which rooms receive afternoon sun and whether the outdoor areas you expect to use offer shade. Request available utility history with the seller's permission and consider how your occupancy and thermostat settings could differ. A bill from a lightly occupied home does not predict a full-time household's usage.
According to the CDC's clinical overview of heat, heat can harm health, adults over 65 are among the groups at greater risk, and some medications affect heat tolerance. Discuss personal precautions with your healthcare professional. Do not assume dry air makes heat harmless, change medication on the basis of a relocation article or treat early morning as automatically safe during every heat event.
Inspect the practical backup plan as carefully as the patio. If cooling fails, where could you stay and how would you get there? Who can respond while you are away? Could you reach groceries, a pharmacy and medical appointments without a long exposed walk? Ask about accessible indoor activities that you would actually use when outdoor plans are unsuitable.
A summer visit can reveal conditions a winter tour misses, but it cannot guarantee that every future summer will feel the same or that you will never regret the choice. Test ordinary errands safely and use current weather and health guidance to plan the day. If heat management would require frequent travel, include those trips in the budget. The retirement decision should account for that recurring adjustment rather than treating it as a cost-free escape.
How can you assess safety and transportation without relying on rankings?
No citywide “safest” label establishes the conditions around a particular home or predicts an individual's safety. Examine the property, the route to your usual destinations and the available official information together. Crime comparisons need matching dates, geography, definitions and reporting coverage. This guide does not publish an unverified Henderson crime rate or promise that a gate, an HOA or an age-qualified designation prevents crime.
On a scouting visit, look for observable features: lighting at the entrance, visibility when backing out, sidewalk condition, road crossings, the distance from parking to the door and how deliveries reach the property. Ask how a controlled entrance actually operates if one exists. Consider whether a visitor, emergency responder or caregiver would need instructions and whether those procedures are documented. These are property questions, not assumptions about the people living in a neighborhood.
Transport deserves its own comparison. Test the route to the grocery store, pharmacy and regular appointments at useful times. Record the actual start and destination, date, time and conditions rather than reporting one favorable drive as a permanent citywide travel time. Try a backup route and investigate the cost and availability of alternatives to driving.
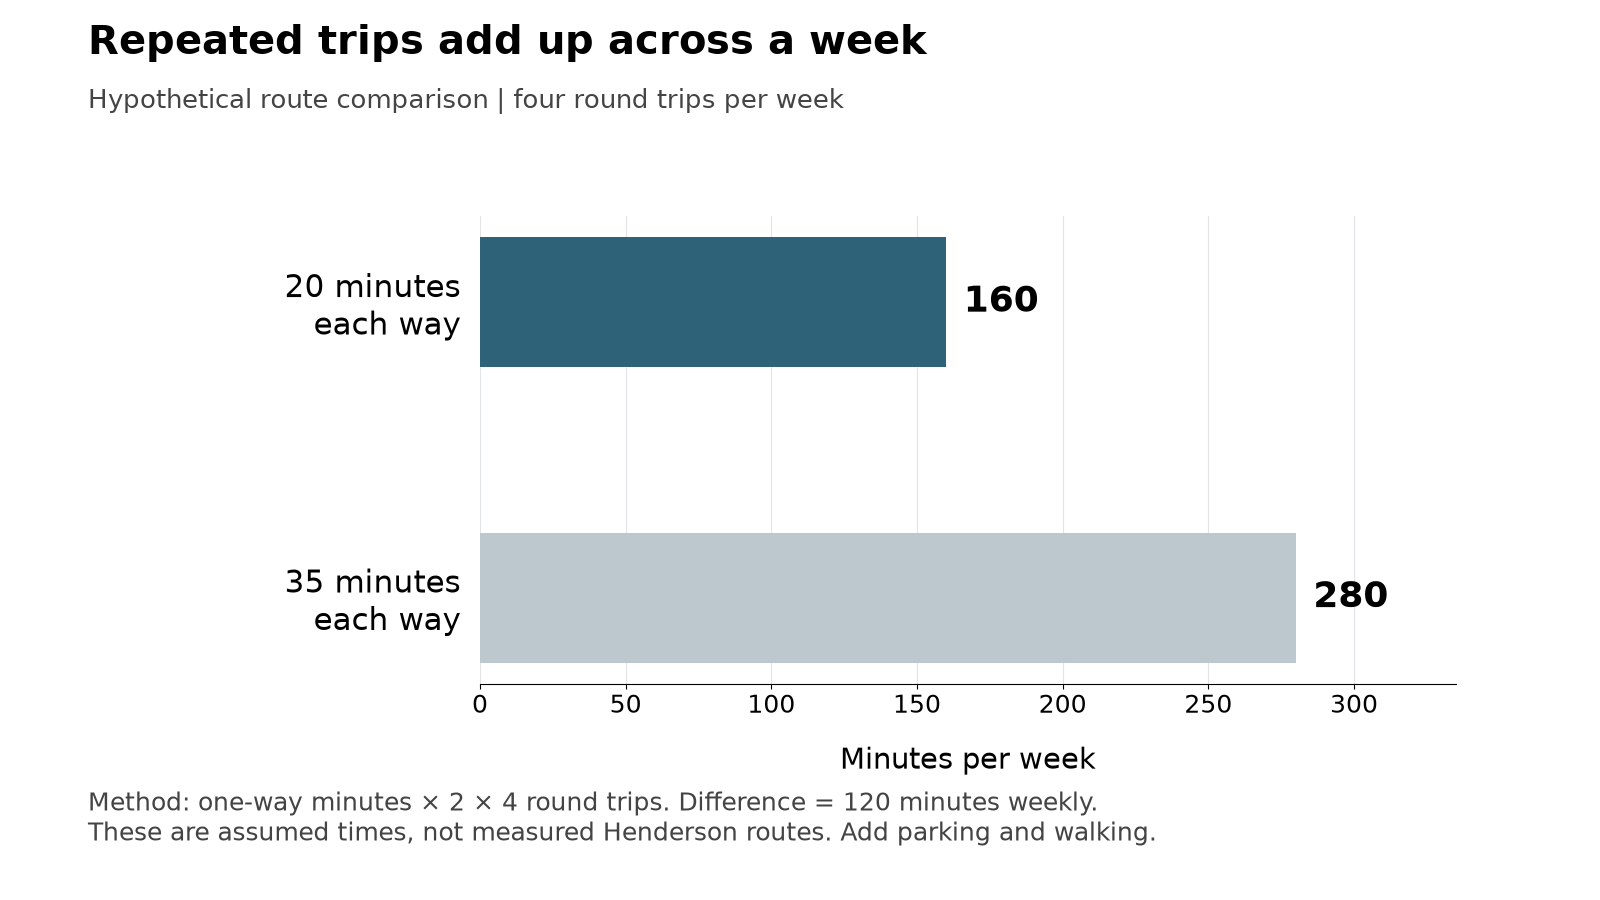
A transparent example shows why repeated trips matter. Four hypothetical weekly round trips taking 20 minutes each way total 160 minutes in transit. At 35 minutes each way, the same trips total 280 minutes, a two-hour weekly difference. These are assumed times, not measured Henderson routes. The calculation helps compare homes once you have your own observations. A home that makes an ordinary week easier may be more valuable to you than one with an appealing address but inconvenient essential trips.
What activities can help you judge community fit?
Choose activities from an actual calendar and access policy rather than a long amenity list. If swimming matters, ask about the pool you would use, its current schedule, entry requirements and any limitations relevant to you. If you prefer classes or clubs, check meeting times, whether newcomers can attend and whether membership or participation costs are separate from the association assessment. The existence of a room does not establish that your preferred activity is available there.
According to Solera at Anthem's clubs and groups directory, examples include a book club, fine arts, pickleball, billiards and chair yoga. Use the current association contact and calendar to investigate activities that interest you. The directory supports those named options, not a promise of immediate availability, particular instruction quality or an automatic social outcome after moving.
Plan time outside the association as well. The Henderson activities guide distinguishes public attractions, seasonal access and practical outing costs. A Lake Las Vegas search may appeal for particular surroundings, but property ownership does not automatically include every nearby recreation service. Confirm the actual access arrangement and the cost of the activities you expect to repeat.
Build a sample week with realistic travel, rest and household tasks. Include something indoors and something that does not require another person's schedule to line up. If a community's main attraction is an activity you rarely do, compare that assessment with a different home plus an independently purchased membership. Conversely, a program you would use frequently may be worth paying for. Judge the relationship between your own preferences, available activities and actual costs; a count of amenities is not a measure of how well you will enjoy living there.
How does Henderson compare with Arizona or Florida for your retirement?
Compare actual homes and the same categories of expense, not Henderson with an entire state's average. A property near your family, a specialist or a regular activity may deserve a different weight from one that requires repeated long trips. Choose representative addresses in each destination and apply the same worksheet, including insurance, ownership costs, transport and the cost of maintaining relationships that matter to you.
Treat climate as a practical living requirement. For each location, review the home's systems, relevant hazard information, insurance terms and the conditions during the season you find hardest. Do not presume Henderson insurance is permanently stable or that a different state's premium applies to every home there. Obtain property-specific quotes with comparable coverage and deductibles. An apparently cheaper premium can reflect different protection rather than a better value.
For taxes, have the same professional compare the same household assumptions in each destination. Avoid combining one state's marginal income-tax rate with another's average property-tax ratio and calling the result an annual savings estimate. Specify the income sources, ownership arrangement and tax year. Similarly, compare actual clinicians and insurance arrangements rather than assigning a general healthcare grade to an entire state.
Write down the reason each option remains on the shortlist and what new information could reverse the decision. Perhaps Henderson offers a suitable house near a desired activity, while another location makes family support easier. Those are legitimate competing priorities. The choice does not require declaring one destination universally superior. Keep the comparison current as quotes, family circumstances or care needs change, and budget the cost of any regular travel that the move would create.
Should you rent first or buy a retirement home in Henderson?
Renting can provide time to test a community and routine before committing purchase funds, but the trial itself has costs and restrictions. Confirm lease terms, deposits, utility responsibilities, renewal provisions, pet rules and the association privileges available to tenants. A rental near a community does not necessarily let you evaluate the experience of using its private facilities. A short stay also may miss the season you most need to understand.
Buying can provide more control over a home, subject to applicable rules, while creating transaction costs and maintenance responsibilities. It does not freeze every housing expense. Insurance, association assessments, taxes and repairs can change even when mortgage principal and interest are fixed. Nor does an intended five-year stay automatically establish that buying will cost less than renting; that result depends on actual prices, financing, expenses and eventual sale proceeds.
Run both scenarios over the period you realistically expect to stay. Include purchase and sale costs, repairs, likely cash remaining after closing and the rent you would pay during a trial. Keep any assumed appreciation clearly separate from known expenses. Ask whether the purchase remains workable without relying on a future refinance or a particular resale gain.
Our moving-to-Las-Vegas-area guide and seller resources can help coordinate the relocation and disposition of a current home. Use the valley home search to collect actual properties for comparison. If uncertainty about care, climate or daily access remains substantial, resolve it before treating ownership as the default. If those questions are settled, a specific home's cost and condition can be evaluated on their own merits.
What should you verify on a Henderson retirement scouting visit?
Organize the visit around evidence you still need. Tour candidate homes, but reserve time for the clinic route, groceries, pharmacy, a preferred activity and ordinary travel. Ask permission before entering private community facilities and confirm visitor access in advance. Bring the same checklist to each property so an attractive presentation does not crowd out a less visible requirement.
Inside the home, examine how you would enter, reach the bedroom, use the bathroom, carry groceries and move through the kitchen. A single-story description does not guarantee a step-free entrance, accessible shower or doors suitable for your needs. Measure the relevant features and ask qualified professionals about feasible modifications and approvals. Avoid assuming the home will accommodate every future change without additional work.
After each tour, separate observations from unresolved items. A viewed doorway is an observation; an association fee mentioned without documents is an item to confirm. Record who supplied each consequential fact and when. Compare the total recurring cost, available cash after the move, essential routes and healthcare arrangements before deciding which property remains suitable.
The Henderson home-buying guide helps organize the next property-level questions. When you are ready to review a shortlist, contact Nevada Real Estate Group or call (702) 637-1759 and describe your budget, required home features and destinations. The useful next step is a documented comparison of real options, with remaining questions assigned to the association, provider, county or relevant professional who can answer them. A retirement move deserves that specific preparation before it becomes a purchase commitment.
Frequently Asked Questions
Is Henderson, Nevada a good place to retire?
It can be if the home, total expenses, healthcare arrangements and routine fit your needs. Nevada has no individual state income tax, but that does not establish a household's overall savings. Evaluate real properties, insurance arrangements and summer living before choosing Henderson.
How much money do you need to retire in Henderson?
There is no single amount that fits every household. This guide's hypothetical worksheet totals $4,300 monthly before mortgage or rent and $5,900 with an assumed $1,600 principal-and-interest payment. Those are examples, not local averages; replace every input with your income, spending and written quotes.
Does Nevada tax Social Security or pension income?
Nevada does not impose an individual state income tax, including on Social Security or pension income. Federal tax and any applicable obligations to another state remain separate. A move from California requires attention to actual residency and California-source income rather than just changing an address.
Does every Henderson homeowner receive the 3% tax cap?
No. Clark County describes the 3% partial abatement for an eligible primary residence, with designation requirements and exceptions such as first-year new construction or a change of use. Confirm the specific parcel with the Assessor. The rule does not cap insurance, HOA assessments or maintenance expenses.
Which Henderson 55+ community is best?
There is no universal choice. Compare Sun City Anthem, Solera at Anthem, Sun City MacDonald Ranch and specific age-qualified neighborhoods such as Heritage at Cadence and Del Webb at Lake Las Vegas against your requirements. Verify the actual association, occupancy rules, home condition, fees and access before choosing.
How should I check healthcare before retiring in Henderson?
Confirm that your needed clinicians accept your exact insurance plan and new patients, arrange continuity of prescriptions and records, and test the trip to appointments. A nearby hospital does not guarantee specialist availability or coverage. Review Medicare enrollment options before moving if your plan's service area will change.
Is a gated or 55+ community a guarantee of safety?
No. Age eligibility and controlled entry are separate features, and neither guarantees safety. Inspect the property and routes, understand access procedures and examine official crime information with matching dates and geographic definitions. This guide does not assign an unverified safety rank or crime rate to Henderson.
Should retirees rent in Henderson before buying?
A rental can help test daily life and seasonal conditions, but check its cost, terms and actual community privileges. Buying can make sense when the property and full financial plan work. Neither a five-year stay nor a low advertised payment automatically establishes that buying is the cheaper option.
Which sources and methods inform this retirement guide?
Public sources were reviewed October 22, 2026. Medicare figures are for calendar year 2026; West Henderson Hospital's opening and Cadence's Heritage announcement retain their original historical dates. Association pages describe published facilities or activities, not verified availability, fees or a property-specific contract. No current citywide home-price, rent, crime-rate or typical retiree-spending estimate is asserted here.
The household budget, tax illustration, two-person Part B calculation and weekly travel comparison are original arithmetic examples with explicit assumptions. They are not client cases, observed route tests or representative household statistics. No field visit, personal medical assessment or individual tax calculation was performed for this update. The cover is conceptual. Property documents, insurance terms and professional advice must resolve an individual decision.
- Nevada Department of Taxation: individual income-tax explanation.
- California Franchise Tax Board: part-year residents and nonresidents.
- Clark County Assessor: property-tax abatement and ownership-document changes.
- CMS: calendar-year 2026 Medicare Parts A and B premiums and deductibles.
- Medicare: Special Enrollment Periods, including moves.
- 24 CFR 100.305: occupancy requirements for qualifying housing for older persons.
- Solera at Anthem: association amenities, clubs and groups, and governing-document reference page.
- Cadence: October 21, 2015 Heritage development announcement.
- Dignity Health Nevada: regional services and provider-verification notice.
- West Henderson Hospital: December 3, 2024 opening announcement.
- CDC: clinical overview of heat, dated September 18, 2025.