The credit score you need for a Las Vegas home depends on the loan, and the score rules moved three times this fall. On September 9, 2026, Fannie Mae and Freddie Mac opened VantageScore 4.0 to every approved lender. On September 30, they aligned their upfront fees across Classic FICO and VantageScore 4.0. On October 8, HUD said FHA will accept VantageScore 4.0 and FICO 10T for case numbers assigned from January 1, 2027. None of those changes lowered a minimum score.
I checked this guide against the agency documents on November 1, 2026. It gives each program's floor from its own handbook, separates what lenders can use now from what is only announced, and shows what a score costs each month. A score is one requirement. It doesn't settle your income, your cash, the property or final approval.
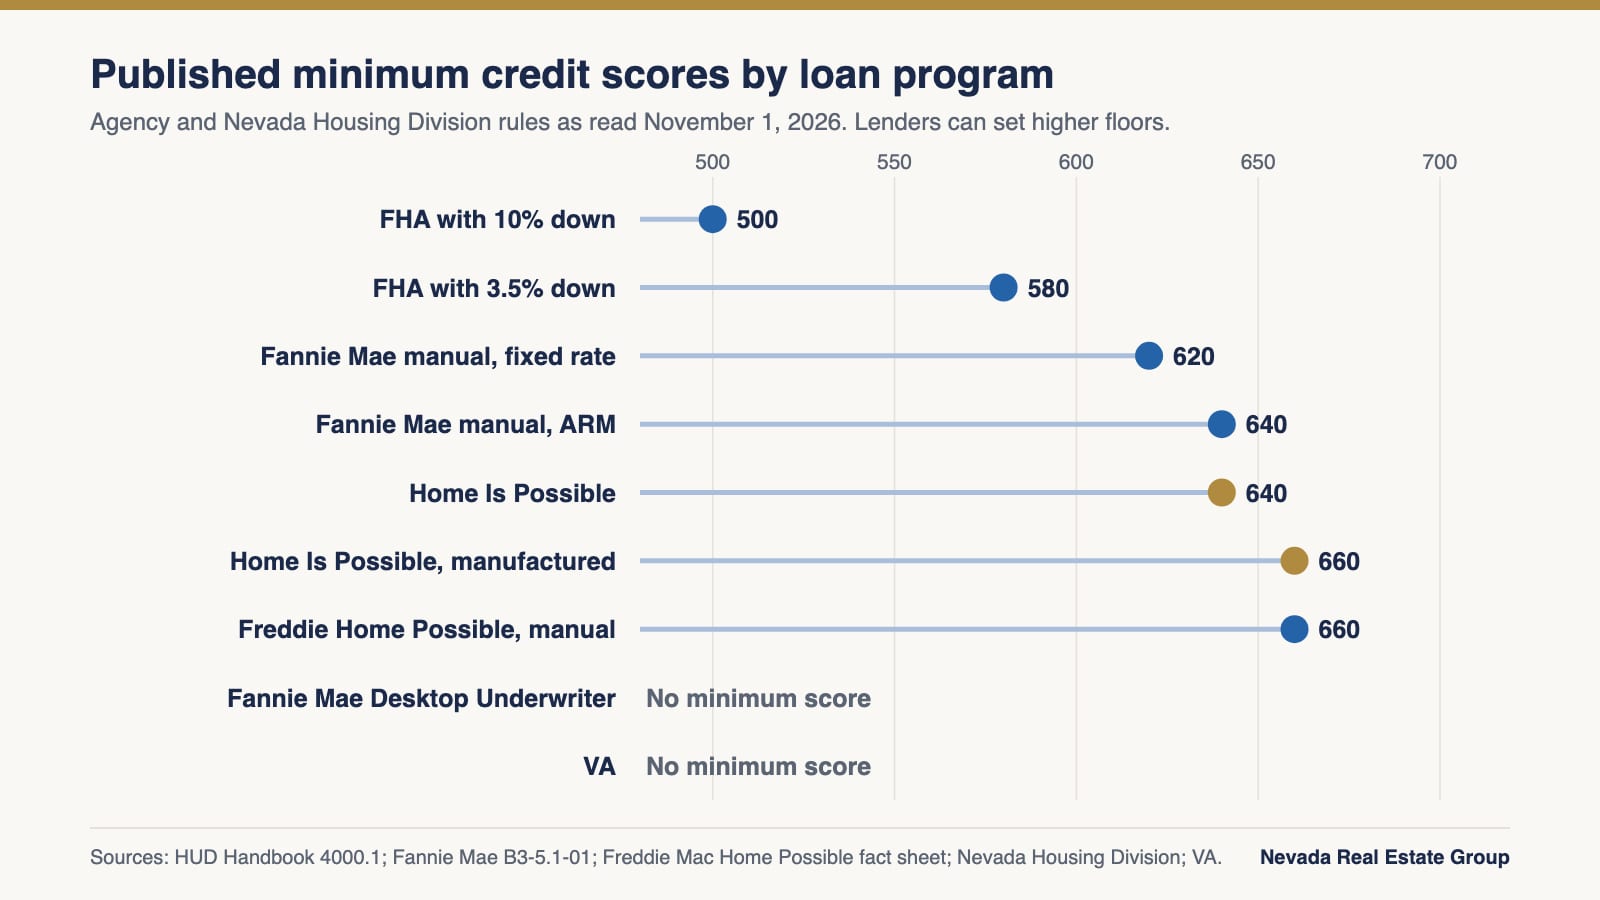
As of November 1, 2026, the published floor for a Las Vegas FHA loan is 580 with 3.5% down, or 500 with 10% down, under HUD Handbook 4000.1. Fannie Mae sets no minimum for Desktop Underwriter files and 620 for manual fixed-rate loans. VA sets none. Nevada's Home Is Possible needs 640. VantageScore 4.0 is usable today on automated Fannie Mae and Freddie Mac loans; FHA starts January 1, 2027.
- FHA needs 580 for 3.5% down under Handbook 4000.1; 500 to 579 caps financing at 90%.
- VantageScore 4.0 opened to all Fannie and Freddie lenders September 9, 2026, but none must adopt it.
- FHA accepts VantageScore 4.0 and FICO 10T only for case numbers assigned from January 1, 2027.
- FICO 10T is approved for Fannie and Freddie loans but still cannot be delivered to them.
- Home Is Possible loans through U.S. Bank take Classic FICO only, with a 640 minimum.
Which credit score matters when you apply for a Las Vegas mortgage?
According to the Consumer Financial Protection Bureau's credit-score explanation, you don't have just one score. The number changes with the model, the data source and the day it was calculated, and most scores run from 300 to 850. The number in a consumer app need not be the one a mortgage lender uses.
Lenders turn three bureau scores into one number by rule. The September 2026 Fannie Mae and Freddie Mac playbook takes the middle of three scores for each borrower, then the lowest of those to represent the loan. FHA works the same way under HUD Handbook 4000.1: the median of three, the lower of two differing scores, then the lowest among the borrowers.
Co-borrowers should ask about one exception. On manually underwritten Fannie Mae loans with more than one borrower, the Selling Guide tests eligibility against the average median credit score. The lender still delivers the representative score, and Fannie Mae's price adjustments are based on that score. So on an FHA file a co-borrower's low score sets the number, while on a manual Fannie Mae file it pulls an average down for eligibility and the representative score still drives the price.
Ask the lender to name the score model, the report date and the underwriting route for each option it quotes. An app alert that your score rose isn't a revised approval or a rate lock. Our mortgage preapproval resources help organize the wider application, and the self-employed and tipped-income guide covers income that varies.
How do the 2026 credit-model changes affect your application?
The headline is that lenders have a second model to choose from. The minimums stayed where they were. This table separates what a lender can use now from what has only been announced.
| Program | Usable today | Announced, not in effect |
|---|---|---|
| Fannie Mae and Freddie Mac, automated | Classic FICO or VantageScore 4.0, one model for all borrowers | FICO 10T delivery, no date. Classic FICO retirement, no date. Two-bureau reports, date to be determined |
| Fannie Mae and Freddie Mac, manual | Classic FICO only | Nothing announced |
| FHA | Classic FICO under the current handbook | VantageScore 4.0 and FICO 10T for case numbers assigned on or after January 1, 2027, with the thresholds unchanged |
| VA | The credit chapter names no score model and no minimum | No 2026 circular on score models in VA's index |
| Home Is Possible through U.S. Bank | Classic FICO only; VantageScore 4.0 is not accepted | Nothing in the October 1 notice |
According to FHFA's credit-score page, updated October 2, 2026, "lenders may choose between Classic FICO or VantageScore 4.0 for loans sold to the Enterprises." The same page says all approved lenders may now use VantageScore 4.0, that "FICO 10T is not currently eligible for delivery," and that Classic FICO is expected to retire at a date nobody has announced. Optional two-bureau credit reports have moved to a date to be determined, so the three-bureau report stays. A limited rollout started earlier: HUD and FHFA's joint April 22, 2026 announcement had the Enterprises accepting VantageScore loans from approved lenders.
Permission isn't adoption. The Enterprise playbook says a lender doesn't have to use VantageScore 4.0 and may stay on Classic FICO if it or its technology vendors aren't ready. It also says manually underwritten loans must stay on Classic FICO. The same model must cover every borrower on the loan, and the lender picks it loan by loan. So ask which model your lender runs before you assume a higher VantageScore number helps you.
The playbook gives one real reason to care. It says VantageScore 4.0 and FICO 10T consider trended credit data and rent payments, which Classic FICO doesn't. It also says both Enterprises' automated systems already weigh trended data and rental payments when available. A renter with a thin file may gain from the new model, but that isn't a promise for any file.
FHA runs on its own calendar. Mortgagee Letter 2026-11, dated October 8, applies to case numbers assigned on or after January 1, 2027. It keeps the three-bureau report and says the minimum thresholds "remain unchanged regardless of Credit Score Model Type." Under the letter, a lender may submit more than one model, but each borrower's score becomes the lowest across the models submitted. FHA's preparedness guide adds that all submitted models must pass for the file to get an Accept. Two models can therefore hurt a file, so ask how your lender plans to submit it if your case number will land in 2027.
Price is the question to raise last, and it changed on September 30. FHFA says the Enterprises published fee adjustments that day to align upfront fees across Classic FICO and VantageScore 4.0, and Freddie Mac's credit-score page says credit fees across the two models are aligned. Scotsman Guide reported that the new fees apply to loans settled or issued on or after October 1. So the model no longer changes the fee schedule, but your score can differ by model and the fee follows the score. Ask for the price under each model on the same day. Fannie Mae's credit-score page, price matrix and lender letter and Freddie Mac's Exhibit 19 and bulletin refused my requests, so I can't quote the adjustments themselves.
What does FHA's 580 threshold actually allow?
According to HUD Handbook 4000.1, revised August 12, 2026, a minimum decision credit score at or above 580 is eligible for maximum financing, and a score from 500 to 579 is limited to 90% loan-to-value. Below 500, the borrower isn't eligible. The maximum on a purchase is 96.5% of adjusted value. Buyers with non-traditional or insufficient credit can still reach maximum financing, but only through manual underwriting. On a manual file, a score under 580 or no score at all caps the ratios at 31/43.
Here is what that gap costs. FOX5's report on Las Vegas REALTORS data put the September 2026 single-family median at $470,000. At that price, 3.5% down is $16,450 and 10% down is $47,000, a difference of $30,550 before closing costs. Moving from 579 to 580 is one point, and no guide can promise you that point.
FHA also caps the loan. The HUD 2026 limit for Clark County is $541,287, which reaches a price of about $560,900 at 3.5% down. On November 1, 2026, 8,607 of 13,009 Clark County residential listings in our MLS feed were asking that much or less. The share runs from 89.0% in North Las Vegas to 33.9% in the Summerlin ZIP codes. The Nevada FHA guide explains the wider cost structure, and first-time buyer resources connect the financing to a plan.
Renters have one FHA detail worth raising. The handbook lets a lender submit a Positive Rental Payment History to the scorecard on a first-time purchase with a score of 620 or more and 12 months of rent at $300 or more.
Is 620 still a universal minimum for a conventional mortgage?
No. According to Fannie Mae's Selling Guide, "A minimum credit score is not required for DU loan casefiles," because Desktop Underwriter weighs its own risk factors. Manual underwriting keeps a minimum of 620 for fixed-rate loans and 640 for adjustable-rate loans, and the Eligibility Matrix can ask for more. The automated minimum went away for files created on or after November 16, 2025. That doesn't mean approval below 620, and a lender can set its own floor.
Freddie Mac is harder to quote. Its Seller/Servicer Guide refused my requests on November 1, so I'm using its February 2026 Home Possible fact sheet. That sheet treats a Loan Product Advisor Accept as acceptable credit. For manual Home Possible loans it sets 660 on a fixed-rate purchase, 680 on an adjustable-rate or no-cash-out refinance, 680 on a manufactured home and 700 on two to four units. Borrowers without scores can go up to 95% loan-to-value. Those numbers cover Home Possible, not every Freddie Mac loan.
| Route | Program floor | Rule source |
|---|---|---|
| FHA, 3.5% down | 580 | HUD Handbook 4000.1 |
| FHA, 10% down | 500 to 579, limited to 90% loan-to-value | HUD Handbook 4000.1 |
| Fannie Mae Desktop Underwriter | No minimum | Selling Guide B3-5.1-01 |
| Fannie Mae manual | 620 fixed; 640 adjustable | Selling Guide B3-5.1-01 |
| Freddie Home Possible manual | 660 fixed purchase; 680 adjustable or manufactured; 700 on two to four units | February 2026 fact sheet |
| VA | No minimum | VA buyer page |
| USDA guaranteed | "An acceptable credit score," with no eligibility number in the rule | 7 CFR 3555.151 |
| Home Is Possible | 640; 660 on manufactured homes | Nevada Housing Division notice |
| Jumbo | No program floor; set by each lender | The written quote |
If you receive a decline or a conditional response, ask for the specific unmet requirement and any alternatives. A buyer comparing Las Vegas homes should settle a payment and cash limit before using a price filter, and our FHA-versus-conventional guide covers the wider comparison.
What should VA and USDA buyers ask beyond the score?
VA's buyer page, updated August 12, 2025, says, "We don't require a minimum credit score, but some lenders do have a requirement," so contact more than one. VA's underwriting rule, 38 CFR 36.4340, calls for a careful analysis of the available credit data and never uses the word "score." It also says a lack of credit history generally isn't an adverse factor for recently discharged veterans. The titles of VA's 2026 circulars don't address a score model, so that question goes to the lender.
For USDA, the regulation is the document I could read. 7 CFR 3555.151 says applicants must show an acceptable credit score and that lenders use scores to underwrite manually, without setting a number for eligibility. The 680 in that section is a compensating factor for a repayment-ratio exception. USDA's own program pages refused my requests on November 1, so I can't confirm how its automated system treats a 640. Ask an approved lender. Household income and a rural address are separate tests.
A financing benefit doesn't assign you to a neighborhood, and it doesn't replace the review of condition, layout and daily travel. The Nevada VA guide has more questions to ask, and North Las Vegas homes are one search area if the price range fits.
Does buying an expensive home automatically require a jumbo loan?
The amount borrowed matters, not the purchase price. FHFA's 2026 baseline for a one-unit home is $832,750, and 20% down keeps a price of about $1,040,900 inside it. On November 1, 88.7% of Clark County residential listings in our feed were priced at or below that figure. A $1,000,000 purchase with $200,000 down leaves $800,000 before any financed charges, which is below the limit.
Jumbo products have no program floor, so the 700-plus figures you see quoted online are lender terms. Get the written minimum score, reserve calculation, down payment and property limits for your actual quote. A buyer in Summerlin or Henderson should compare a jumbo quote with a larger down payment that stays conforming, and check what cash remains after closing.
What credit rules apply to Nevada's Home Is Possible assistance?
The Nevada Housing Division's October 1, 2026 notice says U.S. Bank "currently ONLY accepts Classic FICO" for Home Is Possible loans, and that VantageScore 4.0 is not accepted. The minimum is 640, or 660 for manufactured homes. A buyer whose lender runs VantageScore 4.0 on the first mortgage can't assume that number carries into this program.
The program's rate page, as of October 30, 2026, shows the trade-off between assistance and rate. On FHA, VA and USDA first mortgages, the first-time buyer product pairs 2% assistance with 6.625% and 4% with 6.875%. The HIP-DPA product pairs 3% with 7.375% and 5% with 7.625%. The second mortgage carries no interest and no payment over 30 years, and it's non-forgivable. The teacher option is $7,500 on a five-year prorated forgivable note. First-time status means you haven't owned a home in the past three years.
Set those rates beside the 7.24% Freddie Mac weekly average for October 29: the bigger the assistance, the higher the rate. Ask for a comparison with and without assistance on the same home. The comparison should show both liens, the required cash and what happens when you sell or refinance. The assistance guide gives wider orientation.
How much does a different interest rate change the payment?
Freddie Mac's weekly survey has no credit tiers, so I use Optimal Blue's indexes of actual conforming 30-year rate locks, published on FRED. These are the October 29, 2026 readings, with the payment on a $400,000 loan at each rate.
| FICO band | Over 80% loan-to-value | Monthly payment | At or under 80% loan-to-value | Monthly payment |
|---|---|---|---|---|
| 740 or higher | 7.141% | $2,699 | 7.068% | $2,680 |
| 720 to 739 | 7.280% | $2,737 | 7.077% | $2,682 |
| 700 to 719 | 7.246% | $2,728 | 7.237% | $2,725 |
| 680 to 699 | 7.564% | $2,814 | 7.211% | $2,718 |
| Under 680 | 7.220% | $2,721 | 7.326% | $2,749 |
The gap between 740 or higher and 680 to 699 above 80% loan-to-value is $115 a month on that loan. The under-680 reading is lower than 680 to 699 on the same day, and that tells you how to read the table. These indexes track loans that actually locked, with their own mix of points and products. They aren't a lender's price sheet, and one day's gap isn't what a higher score will save you.
For scale, the Freddie Mac weekly average of 7.24% on October 29 gives $2,726 on the same loan. The FHA index read 7.039% that day. Ask for current written quotes on the same loan structure, and keep each rate next to its points, because a lower advertised rate may cost more cash at closing. The preapproval process turns these indexes into a quote on your own file.
How should you compare conventional PMI with FHA mortgage insurance?
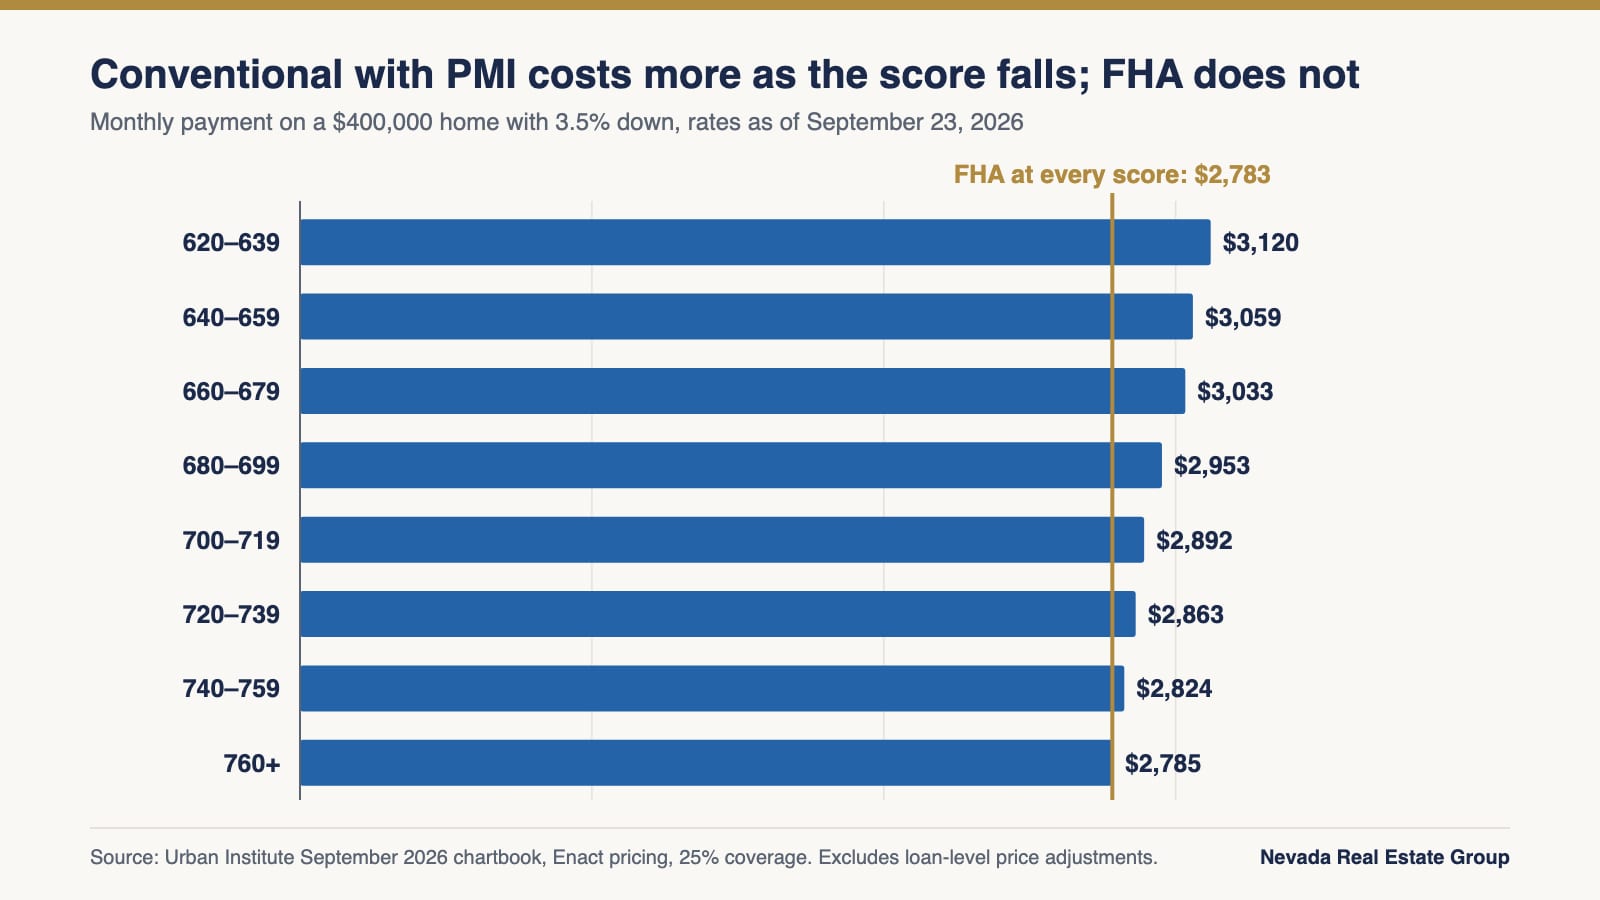
This is where a score moves real money, and there is a published table for it. The Urban Institute's September 2026 chartbook prices a $400,000 home at 96.5% loan-to-value with rates as of September 23, 2026. FHA costs the same at every score: $2,783 a month with 1.75% upfront and 0.55% a year. Conventional private mortgage insurance runs from 0.46% a year at 760 or higher to 1.50% at 620 to 639, which moves the payment from $2,785 to $3,120.
So at 620 to 639, FHA is $337 a month cheaper on that example. At 760 or higher, the two are $2 apart. The table excludes the Enterprises' loan-level price adjustments and uses the 25% coverage that applies to HomeReady and Home Possible, so treat it as a guide. Your own premium comes from the insurer.
Ending the insurance differs too. According to the CFPB's PMI guidance, you can ask to cancel when the balance is scheduled to reach 80% of original value, if you meet the conditions, and the servicer must end it at the scheduled 78% point if you're current. HUD's handbook schedule keeps FHA's annual premium for the mortgage term on a typical low-down purchase. It ends after 11 years only when the original loan-to-value is 90% or less. Don't plan around a future refinance to remove it. Our FHA guide has more on those questions.
What does the complete monthly housing budget include?
Principal and interest is only the start. The CFPB's Loan Estimate explainer notes that taxes, insurance and mortgage insurance raise the payment, and that costs outside escrow are often paid in lump sums.
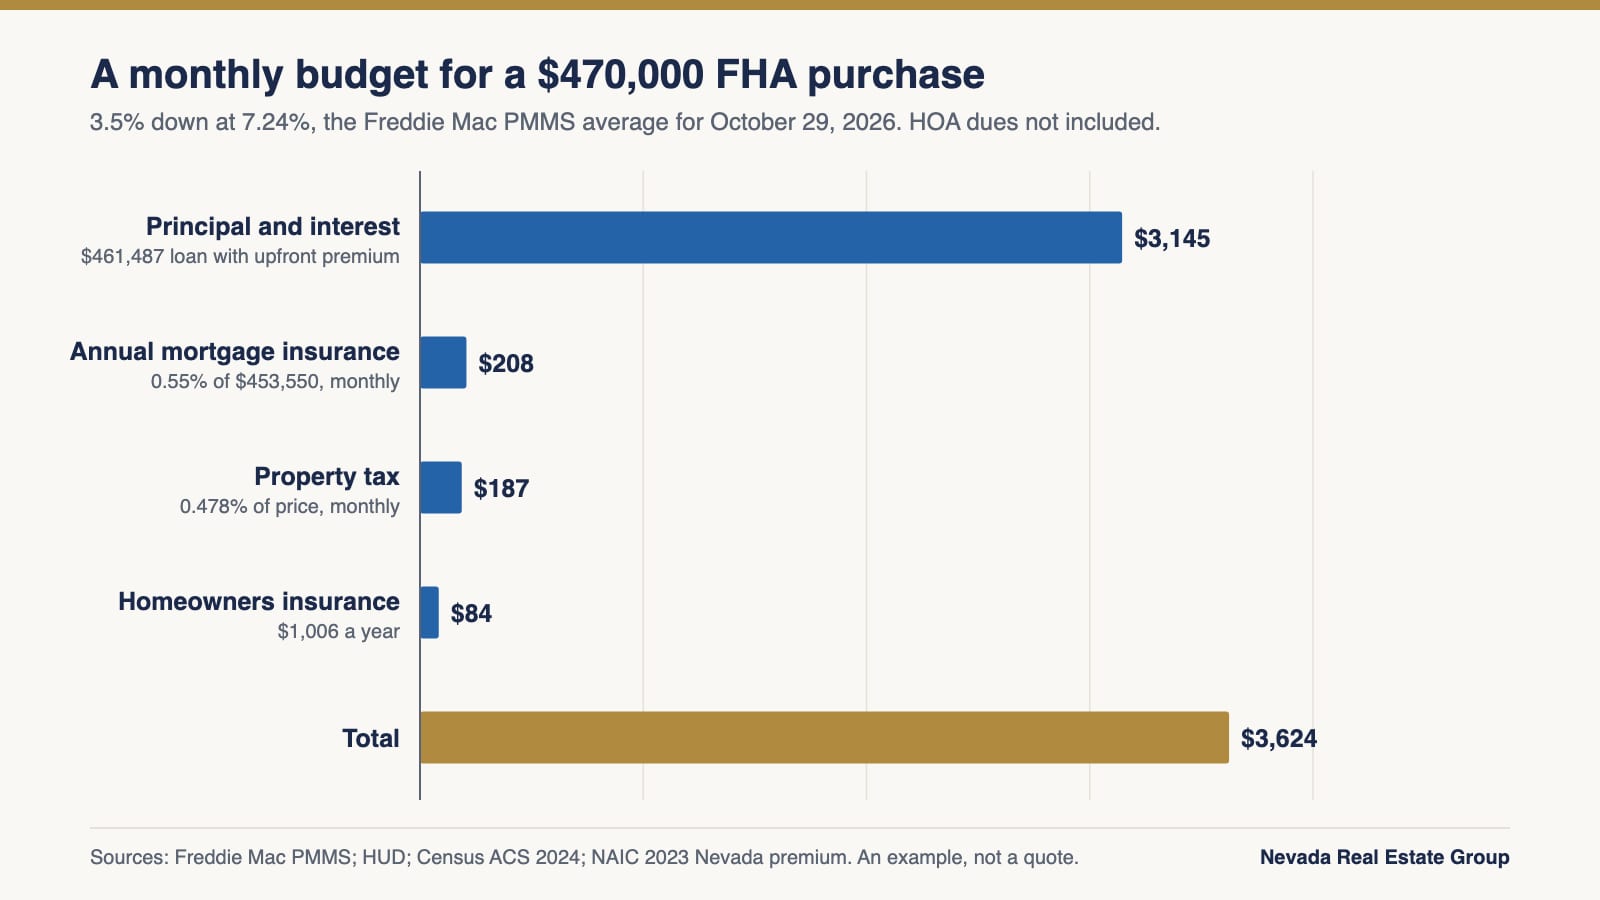
Take the $470,000 September median with FHA and 3.5% down. The base loan is $453,550, and the 1.75% upfront premium makes it $461,487 if financed. At the 7.24% Freddie Mac average, principal and interest is $3,145. Annual mortgage insurance at 0.55% adds $208 a month. Property tax at the 0.478% Clark County effective rate from the Census Bureau's 2024 survey adds about $187, and the NAIC's 2023 Nevada average of $1,006 a year for $450,000 to $499,999 of coverage adds $84. That totals about $3,624 a month, before any HOA dues, utilities or repairs.
That's an example with named inputs, not a quote. Your tax bill, insurance premium and rate will differ, so replace each line with figures for the actual home. A temporary payment reduction needs the later full payment beside it, and a loan a lender will approve can still exceed what you want to spend. The buyer hub helps organize this, and new-construction listings need the same review even when an incentive looks attractive.
What do Las Vegas homes cost by area?
Credit sets how much you can borrow and at what cost, and the market sets what that buys. These figures come from our GLVAR MLS feed: all residential types in Clark County, listings on November 1, 2026, including those under contract or coming soon, and closings by closing date from July 1 through September 30, 2026. Late-posted September closings could still change the count slightly.
| Area | Listings | Median asking price | Share at or under $560,900 | Third-quarter closings | Median closed price |
|---|---|---|---|---|---|
| Clark County | 13,009 | $459,990 | 66.2% | 7,038 | $442,500 |
| Las Vegas | 8,845 | $453,100 | 66.2% | 4,628 | $435,000 |
| North Las Vegas | 1,072 | $425,000 | 89.0% | 780 | $415,000 |
| Henderson | 2,581 | $532,000 | 54.9% | 1,444 | $492,250 |
| Summerlin ZIP codes 89134, 89135, 89138, 89144 | 1,107 | $699,900 | 33.9% | 652 | $645,587 |
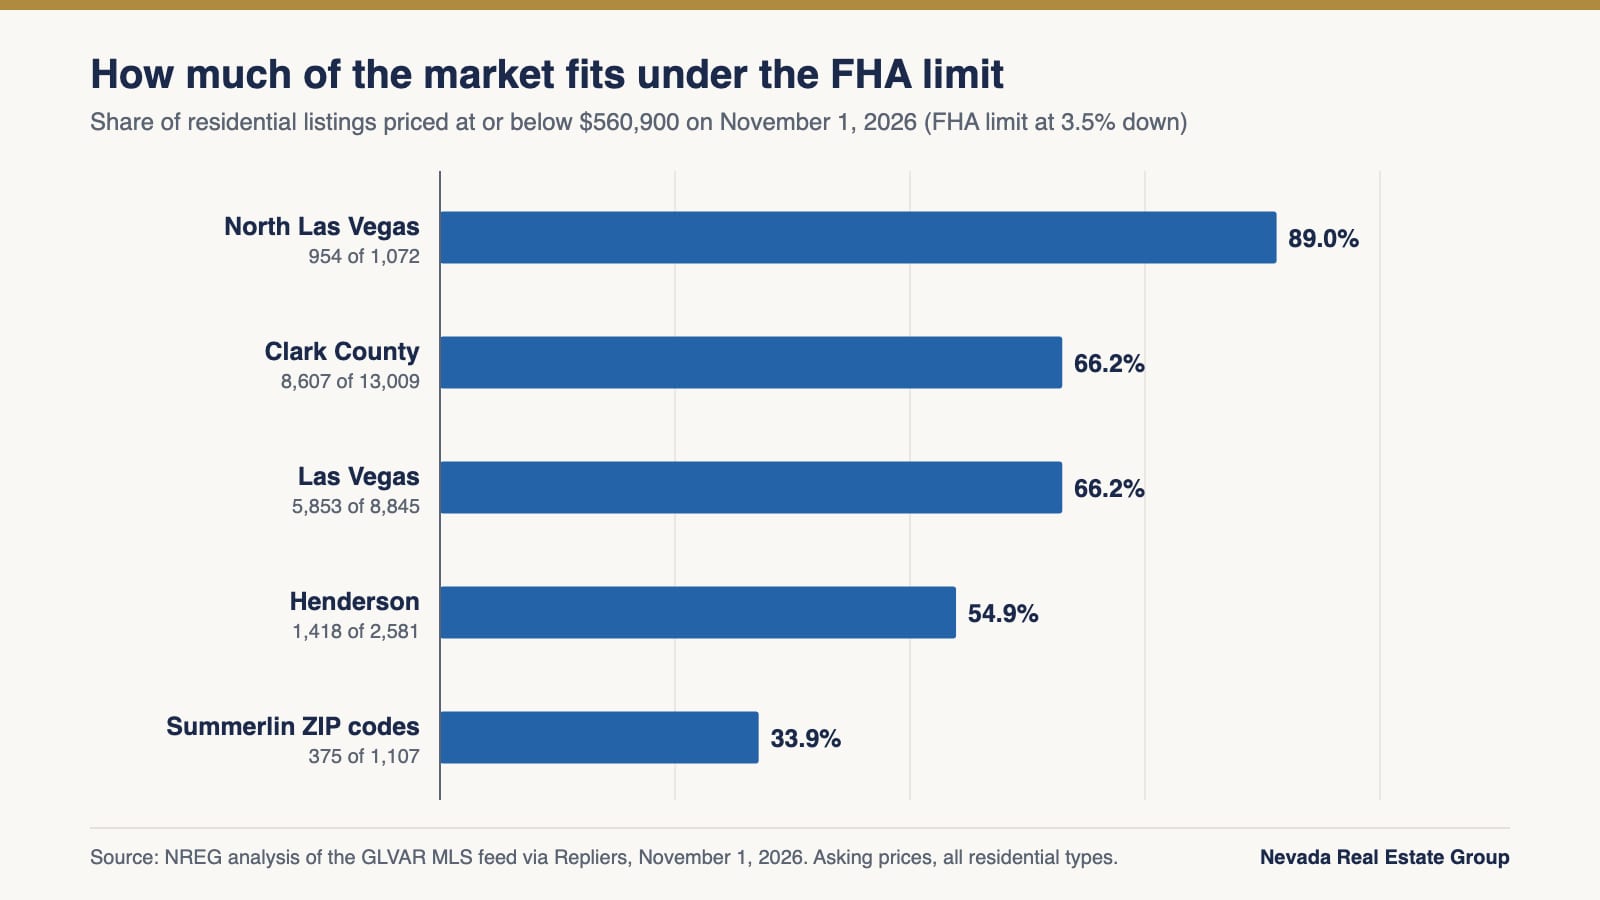
A score doesn't decide where you can buy. Property condition, loan amount, appraisal, the association and your file all count. A cheap listing can need repairs or carry obligations that change the financing, and an expensive one can involve a smaller loan than its price suggests. Whether your search points to North Las Vegas, Henderson homes or Summerlin, check asking prices against closed sales for the actual property type.
How can you improve the credit file without relying on a promised point increase?
The CFPB's credit-building guidance lists the habits that count: pay on time, keep balances low, apply only for credit you need and check your reports. Experts often suggest using under 30% of your limits, and the page says top scorers often stay under 10%. You don't need to carry a balance or any debt to get a good score.
According to the Federal Trade Commission, the three bureaus let you check your report from each once a week for free at AnnualCreditReport.com, and you can dispute mistakes with the bureau and the business that supplied the information. A report isn't a score, so keep copies of what you send.
Ask the lender which actions matter for your application and what they do to your closing cash. Paying down a card may help the score while reducing funds you need for closing or reserves, so a plan has to weigh both. Be wary of anyone promising a guaranteed point jump or a fixed timeline. The credit-preparation companion lays out a planning sequence, and its examples are illustrations, not guarantees.
How should you compare lenders without confusing the offers?
The CFPB's Loan Estimate comparison guide tells you to compare the loan amount, rate, mortgage insurance, total monthly payment, upfront costs, lender credits and cash to close. Rates change daily, so offers from different days can differ for that reason alone. Add two 2026 questions: which score model did you use, and would the price change under the other one?
Shopping won't hurt the way many buyers fear. According to the CFPB's mortgage-credit-check guidance, checking your own credit doesn't affect your scores, and multiple mortgage checks within a 45-day window are recorded as a single inquiry. A check after the window still has only a small effect, the page says, so shopping is usually worth it.
Keep a short written comparison of unresolved questions as well as prices. If one offer needs more documentation or treats the property differently, that can matter more than a small payment gap. If assistance is included, compare the second mortgage too. Our preapproval-versus-prequalification guide explains the stages, but the actual letter and its conditions show how far your file has progressed.
What should stay stable between preapproval and closing?
Tell the lender about changes that could affect the application. A new debt, a job change, a large transfer or altered purchase terms can trigger more review. You don't have to freeze ordinary life, but discuss material changes before you assume the earlier approval still stands, and keep records for the funds you use.
Ask which conditions remain attached to the preapproval, what property review is still required and when updated information may be requested. For a condo, project documents can matter even with strong credit. For a home needing repairs, the lender's property rules can change the available loan. An appraisal, an inspection, an association review and final loan approval answer different questions, and none replaces the others.
Our team closed 789 homes in 2025, more than $361.5 million in volume, and that doesn't tell you a seller will prefer your offer or that your financing will close without conditions. Don't waive a protection because your score looks strong. The buyer resources give a process overview; the contract and the lender's requirements set the actual steps.
How do you decide whether to buy now or prepare further?
Start with the lender's current answer and your own budget. If an acceptable proposal is available, compare it with a reasonable alternative. If a requirement is unmet, identify what would resolve it and whether the timeline fits. Don't let the decision rest on a future refinance, guaranteed appreciation or a score increase that hasn't happened.
Separate three questions: can the loan be approved, can you comfortably carry the costs, and does this home meet your needs? A yes to one doesn't settle the others. If a lower price or a different property eases the budget, compare it directly, and don't treat the maximum approval as a spending target. Review the Las Vegas search with those limits in place.
If your case number could land after January 1, 2027, raise that now, because it changes which score models an FHA file can use. For help organizing a search and the lender questions that go with it, call (702) 637-1759 or use our contact page. We can connect the financing review with the home decision. The lender sets the loan requirements and makes the approval.
Frequently asked questions
Is 620 always required for a conventional mortgage?
No. Fannie Mae's Selling Guide says a minimum score isn't required for Desktop Underwriter casefiles. Its manual minimums are 620 for fixed-rate and 640 for adjustable-rate loans. Other investors and lenders can differ, and approval below 620 isn't promised.
Does a 580 score guarantee an FHA loan with 3.5% down?
No. HUD's handbook makes a 580 eligible for maximum financing, but the lender, borrower, property and transaction must meet other requirements. Assistance programs can add their own, and a lender can set a higher floor.
Can I use VantageScore 4.0 for a Las Vegas mortgage today?
On automated Fannie Mae and Freddie Mac loans, yes, if your lender has adopted it. Manual loans stay on Classic FICO, FHA starts with case numbers assigned on or after January 1, 2027, and Home Is Possible through U.S. Bank doesn't accept it.
When will FICO 10T count?
FHA accepts it for case numbers assigned from January 1, 2027. Fannie Mae and Freddie Mac have approved it, but FHFA says it isn't currently eligible for delivery, and no date has been announced.
Does VA have a federal minimum credit score?
No. VA's buyer page says it doesn't require a minimum credit score, though some lenders do. Entitlement, income, debt and the property still matter, so compare more than one lender.
Will raising my score forty points save a fixed monthly amount?
Nobody can promise that. On the Urban Institute's September table, moving from 620 to 639 up to 660 to 679 cuts a conventional low-down payment by $87 a month on a $400,000 home. Your own result depends on the lender, the insurer and the day.
Does conventional PMI automatically end when my home gains 22% equity?
Not on market value alone. The CFPB says automatic termination ties to the scheduled 78% of original value with current payments, and you can request cancellation at the scheduled 80% point if you meet the conditions. Ask your servicer which rules apply.
What should I bring to the first lender conversation?
Ask for the lender's document list and secure submission method. Explain the intended purchase, income pattern, debts, available funds and any interest in assistance. Then ask for the score model, the underwriting route, the remaining conditions and a complete cost comparison.
Sources and evidence periods
All sources were read November 1, 2026, unless noted.
- Score models: FHFA credit-score page, updated October 2, 2026; Fannie Mae and Freddie Mac partner playbook, September 9, 2026; HUD and FHFA announcement, April 22, 2026; Freddie Mac's credit-score page on the fee alignment; Scotsman Guide, October 1, 2026, on its start date.
- FHA: HUD Handbook 4000.1, revised August 12, 2026; Mortgagee Letter 2026-11; FHA preparedness guide; HUD 2026 limits.
- Conventional: Fannie Mae Selling Guide B3-5.1-01, dated April 22, 2026; Freddie Mac Home Possible fact sheet, February 2026; FHFA 2026 conforming limit. Freddie Mac's Seller/Servicer Guide, Exhibit 19 and bulletin, and Fannie Mae's credit-score page, lender letter and price matrix, refused my requests, so this guide doesn't quote them.
- VA and USDA: VA buyer page, updated August 12, 2025; 38 CFR 36.4340; VA circulars; 7 CFR 3555.151, last amended August 31, 2022. VA's online Lenders Handbook didn't load for my reader, and USDA's own pages refused my requests.
- Nevada: Housing Division notice, October 1, 2026; program rates, as of October 30, 2026.
- Costs: Freddie Mac PMMS, October 29, 2026; Optimal Blue indexes on FRED, October 29, 2026; Urban Institute chartbook, September 2026.
- Consumer guidance: CFPB credit scores, credit habits, PMI cancellation and mortgage credit checks; FTC free credit reports.
- Market data: NREG analysis of the GLVAR MLS feed through Repliers, all Clark County residential types, listings pulled November 1, 2026 and closings by closing date, with medians computed from the records. Las Vegas REALTORS' September 2026 median comes from FOX5's report.