A Reno home budget should describe more than a price filter. A house that provides the right rooms may need immediate work; a smaller home may suit your routine but carry different association obligations. Winter access, the actual insurance proposal and cash remaining after closing can change the decision. Use dated market evidence to frame the search, then compare what each candidate provides and what you will be responsible for owning.
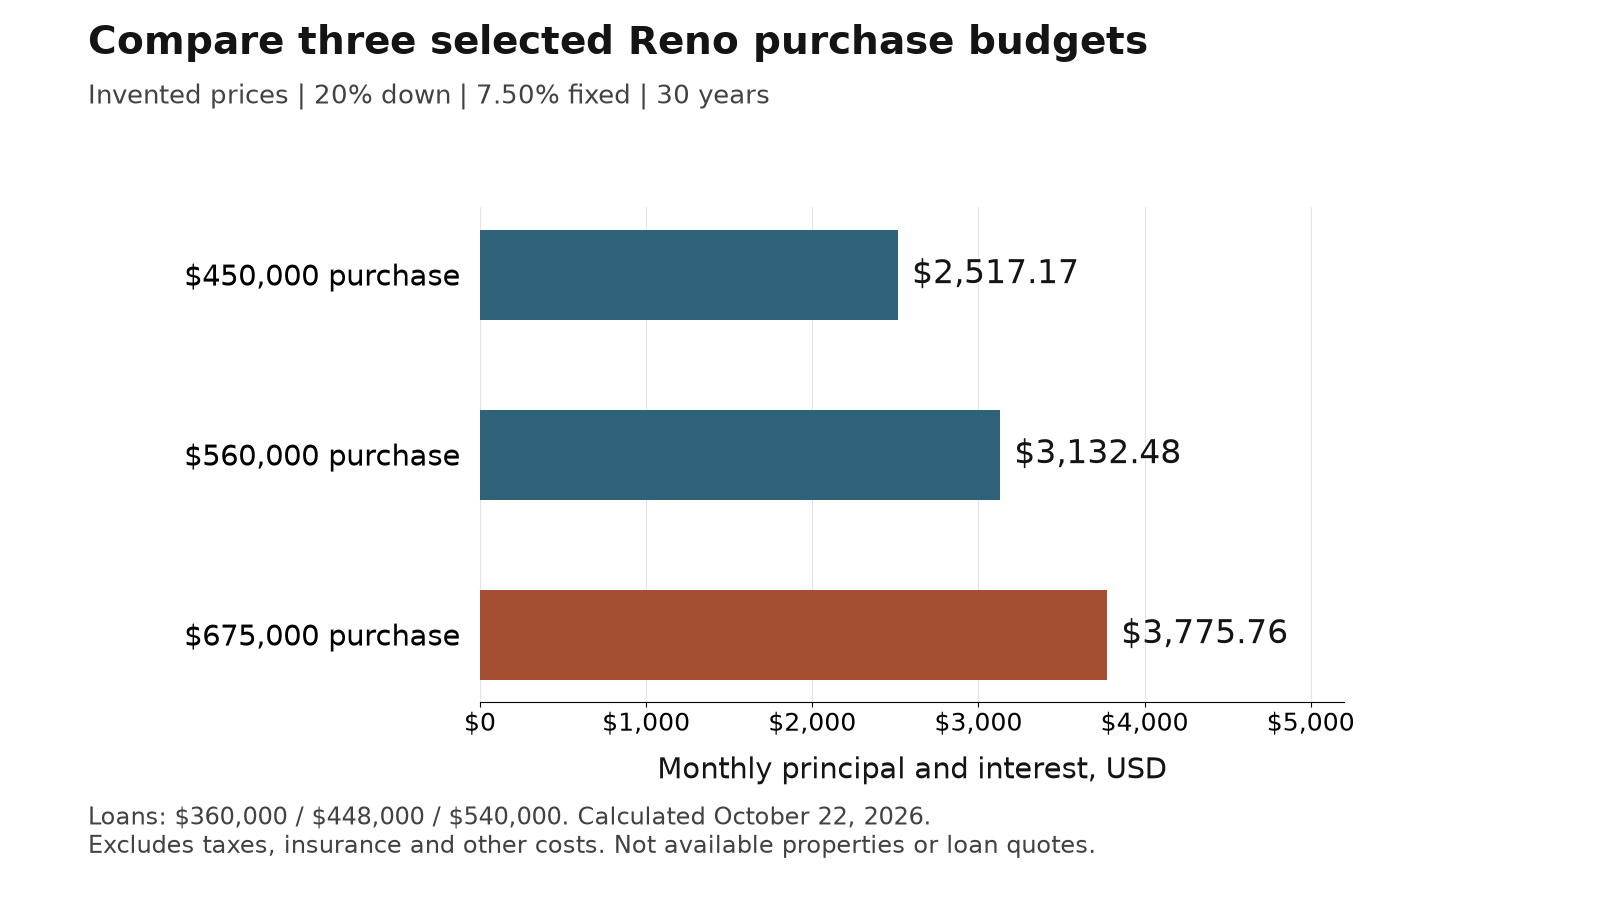
This guide uses $450,000, $560,000 and $675,000 as chosen Reno purchase budgets, not guaranteed home specifications. At an assumed 7.50% fixed rate for 30 years with 20% down, the $560,000 example has $3,132.48 monthly principal and interest. Taxes, insurance, association charges and other ownership expenses are additional. Compare actual layouts, condition, winter responsibilities, location and retained cash instead of treating a median price as a particular house.
- Keep the market period, geography and property type attached to each price statistic.
- The $560,000 middle example is a chosen budget, not today’s Reno or Reno–Sparks median.
- Compare actual homes without assuming that a price guarantees size, age, bedrooms or a community.
- Confirm who handles the road, driveway, sidewalk and other winter responsibilities at the address.
- Use actual tax, insurance and association documents to replace the example cost allowances.
- Separate loan approval, household spending and cash left after the purchase.
How we know this: Across the 9,600+ closings Nevada Real Estate Group has represented statewide — more than $4.85B in closed volume — a meaningful share sit right around the Reno-Sparks median, so we see what that budget buys every week. In my experience, buyers who name their single top priority first — newest, biggest, or best location — get far more for $560,000 than buyers who try to maximize all three at once. Public market summaries and hypothetical calculations below are identified separately; they are not presented as an analysis of those company transactions.
Which Reno Price Figure Should Guide Your Search?
According to NREG’s Reno city market report, the August 2026 single-family median sold price was $681,525 across 229 reported closings, reviewed as of October 22, 2026. This is an affiliated published city selection from the NNRMLS/Repliers feed, not an independently recomputed transaction dataset. It does not establish the value of an individual listing or every property in the broader Truckee Meadows.
According to Sierra Nevada REALTORS’ September 2026 report, the Washoe County all-residential selection had a $595,000 median across 487 closings. The report was updated October 4, 2026. That county panel includes multiple residential property types and a broader geography. Its difference from the Reno city figure is not a calculation of one month’s price movement.
| Measure | Period and selection | Amount | Decision use |
|---|---|---|---|
| NREG published Reno median | August; single-family city selection; 229 closings | $681,525 | Dated city context |
| SNR published Washoe median | September; all-residential county selection; 487 closings | $595,000 | Broader, different market context |
| This guide’s middle budget | Chosen calculation input | $560,000 | Compare financing and actual candidates |
We've represented buyers at this price point across the whole Truckee Meadows, so treat the median as a starting budget, not a house. For an offer, request relevant comparable closings and identify differences in layout, condition, lot and terms. A market midpoint cannot promise a certain bedroom count or tell you whether the target’s price is justified. Keep the property evidence separate from the broad summary.
How Do You Turn a Budget into Useful Home Requirements?
Start with the functions the home must serve: sleeping arrangements, work space, storage, parking, outdoor use and any access needs. Then distinguish features you could change later from requirements the property must meet immediately. A larger floor area does not automatically provide a better layout, and an attractive finish does not answer whether the household’s everyday routine fits.
Use the same requirement sheet at each selected budget. A $450,000 candidate is not necessarily attached, and a $675,000 candidate does not necessarily add a bedroom or a particular amount of space. Inventory and individual condition matter. Compare what is actually available instead of relying on a fixed ladder that assigns one kind of house to every price.
Record the asking price, required features, unresolved condition questions, documented monthly obligations and initial cash plan. Give each unknown a next step: an inspection, a written estimate, a record review or a question for the appropriate professional. A low total built from missing expenses is not a completed comparison.
Start with Reno homes for sale, the Reno hub and the Northern Nevada community directory. If Sparks is in the search, evaluate it as its own location and market selection. Your goal is a shortlist of specific homes that satisfy the requirements, with clear reasons for the compromises each one introduces.
What Should You Compare in South Meadows and Spanish Springs?
For candidates in South Meadows or Damonte Ranch, inspect the actual plan, lot, condition and obligations. For Spanish Springs, keep the Sparks-area location explicit rather than treating it as another Reno neighborhood. These labels help organize a search; none proves that a chosen price buys a newer home, a specified size or a particular commute.
If a builder proposal is involved, identify the selected lot, included configuration, options, completion terms and items needed after closing. A base-price advertisement can differ from the proposal for the house you want. Compare required setup and the household’s timing with an existing home that may include some of those items already.
Check how the home serves your regular destinations. A workplace, appointment or activity can make one address convenient for you without making the whole area universally convenient. Test the relevant route and schedule. Do not assume that a south-end address guarantees a quick airport trip or that every northern candidate adds the same amount of travel.
Use Reno new homes and Sparks new homes to investigate current choices. Obtain a current written offer before using a price or incentive. Compare finishes and warranties alongside inspection findings, ownership documents and cash requirements; “new” alone does not resolve every condition or cost question.
How Should You Evaluate Established Northwest and Old Southwest Homes?
For a property in Northwest Reno or Old Southwest Reno, distinguish the location you want from assumptions about condition or value. Identify the layout, storage, parking and outdoor space you would actually use. An established setting can provide something valuable to one household while leaving another with an unsuitable routine or costly work.
I steer buyers here when they want to be close to the action — Midtown, the Riverwalk, and the University of Nevada, Reno — and are comfortable trading brand-new for established. That preference still needs an address-level review. A mature landscape, older finish or renovated kitchen does not establish the condition of the roof, heating equipment, drainage or other systems.
Ask for relevant permits, service records and qualified inspections where appropriate. Separate necessary work from optional improvements and obtain realistic estimates for matters that affect the decision. Do not count a proposed conversion or alteration as an available feature until the applicable requirements and practical feasibility are understood.
According to EPA’s lead-disclosure guidance, many pre-1978 housing transactions have specific disclosure requirements, with exceptions. Obtain appropriate current guidance and documents for an older candidate; age alone does not establish a hazard at the property. The useful comparison is what the house provides after its actual findings and responsibilities have been counted, without assuming every older home is either a bargain or a repair problem.
How Do Golf and Foothill Settings Change the Questions?
For Somersett, ArrowCreek or Caughlin Ranch, separate the property from the broad community label. Determine the actual associations, applicable charges, included services and any optional club membership. A golf setting does not establish that membership is included or that the household will use the facilities enough to justify their cost.
I bring these communities into the conversation for buyers who prioritize setting and lifestyle over raw size, or who are downsizing from a larger home elsewhere. Compare that preference with the complete proposal. A smaller home with appropriate responsibilities can be useful; a similar-looking property may carry different maintenance, access or association obligations.
Inspect the features behind the view or setting: outdoor maintenance, driveway configuration, drainage, insurance availability and the way the property works through the year. No neighborhood name guarantees a particular hazard profile, future resale result or required maintenance budget. Obtain address-specific information rather than treating a premium location as proof of financial performance.
Use Reno golf homes or Reno luxury homes when those features fit the search. The Reno–Tahoe golf-community guide addresses a broader selection question; its dated pricing and membership details require current confirmation. This article does not independently verify every companion guide or establish a current home available at each chosen budget.
Who Handles Snow at the Property You Are Considering?
According to City of Reno snow and ice guidance, the city prioritizes major and collector streets and leaves private streets and related private cul-de-sacs to the responsible association or property operator. The city also explains that plowing can leave berms at driveways and sidewalks that it does not remove. Those distinctions matter when comparing the work and services a home requires.
According to Somersett Owners Association’s snow-removal page, responsibility differs among association-maintained private streets, city streets and separately contracted streets in The Village and The Vue. The page also describes homeowner responsibilities around sidewalks and plow deposits. Use that as a prompt to identify the actual arrangement for the candidate, not as a promise of when any particular street will be cleared.
Confirm the responsible party, included service, relevant trigger and what remains the homeowner’s task. Ask about the driveway and walkway as well as the road. If you will arrange help, investigate availability and terms before relying on it. No route, storm response time or actual contractor price was measured for this guide.
The official city and association pages are not identical on every plowing detail. Avoid relying on an older generalized threshold or cul-de-sac statement as a universal current rule. Confirm with the responsible operator for the actual street. A usable winter plan identifies who does what and how the household handles interruptions; it does not require pretending that a community label eliminates weather-related work.
How Do You Budget for Uneven Seasonal Work?
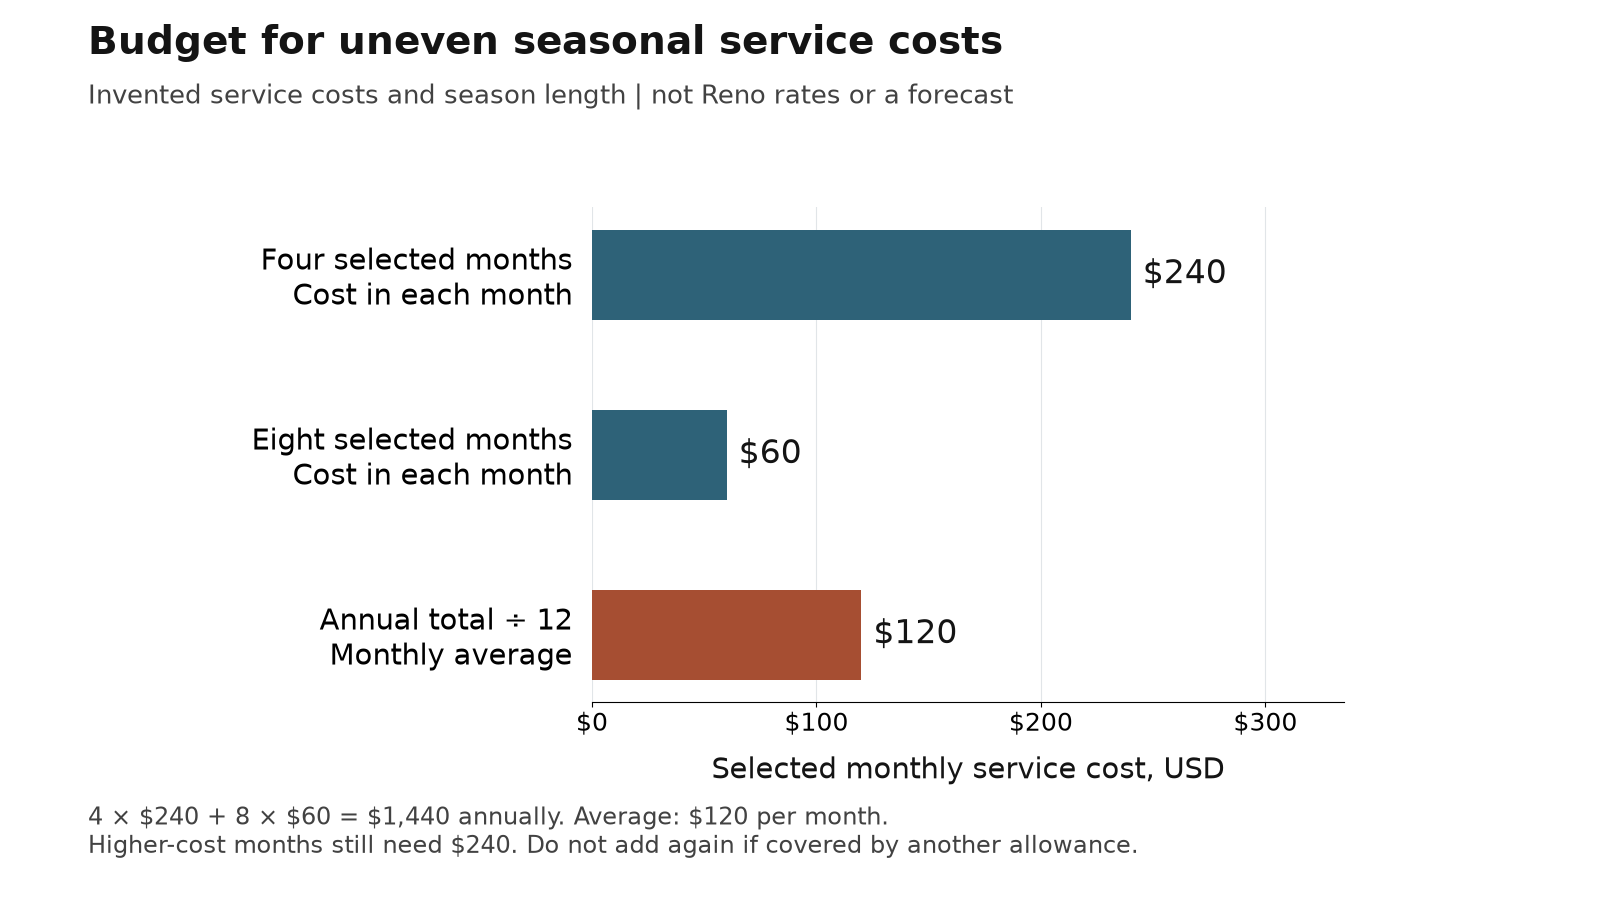
A monthly average can be useful without describing the bill in every month. In an invented example calculated as of October 22, 2026, assume four months at $240 for selected seasonal services and eight months at $60 for other selected upkeep. The annual sum is $1,440, equivalent to $120 per month. The higher-cost months still need $240 when those bills arrive.
These are selected planning inputs, not Reno snow-removal rates, utility averages or an observed weather forecast. The four-month grouping is an assumption, not a prediction of the winter season. Real charges may be per visit, contract-based or dependent on other terms, and the property may require tasks that are absent from this example.
Ask which work an association includes and which service you would otherwise arrange. Avoid paying for the same item twice in the comparison, but do not assume a broad maintenance description covers everything. A home with fewer owner tasks can still have substantial charges; a lower fee can leave more work with the household.
Keep the seasonal worksheet consistent with the broader owner budget. If these selected costs are already included in a maintenance allowance, do not add them again. The point is to match the timing and scope of real expenses with the household’s cash, then revisit the estimate after actual experience. An annual total alone can conceal a shortfall in the month when the work must be paid for.
How Do the Three Budgets Compare Under Identical Loan Assumptions?
According to Freddie Mac’s Primary Mortgage Market Survey, the national 30-year fixed average released October 22, 2026 was 7.32%. That is national context, not a Reno borrower’s quote. The examples below separately assume 7.50% fixed for 30 years with 20% down, keeping the loan terms constant to show the effect of borrowing different amounts.
| Input or result | $450,000 purchase | $560,000 purchase | $675,000 purchase |
|---|---|---|---|
| 20% down payment | $90,000 | $112,000 | $135,000 |
| Loan amount | $360,000 | $448,000 | $540,000 |
| Assumed fixed rate and term | 7.50%; 30 years | 7.50%; 30 years | 7.50%; 30 years |
| Monthly principal and interest | $2,517.17 | $3,132.48 | $3,775.76 |
No available home or lender offer is represented. Taxes, insurance, association charges and other ownership expenses are additional. A lower down payment changes the loan and may change other costs; obtain actual program comparisons instead of assuming every borrower has the same terms or requirements.
According to the CFPB Loan Estimate guide, loan terms, projected payments and closing costs each warrant review. Compare points, credits and relevant conditions alongside the rate. If the proposed price or financing changes, update both monthly costs and initial cash. The purchase should remain workable without relying on a future refinance whose availability, rate and cost are unknown.
What Does the Middle Example Cost Beyond the Loan?
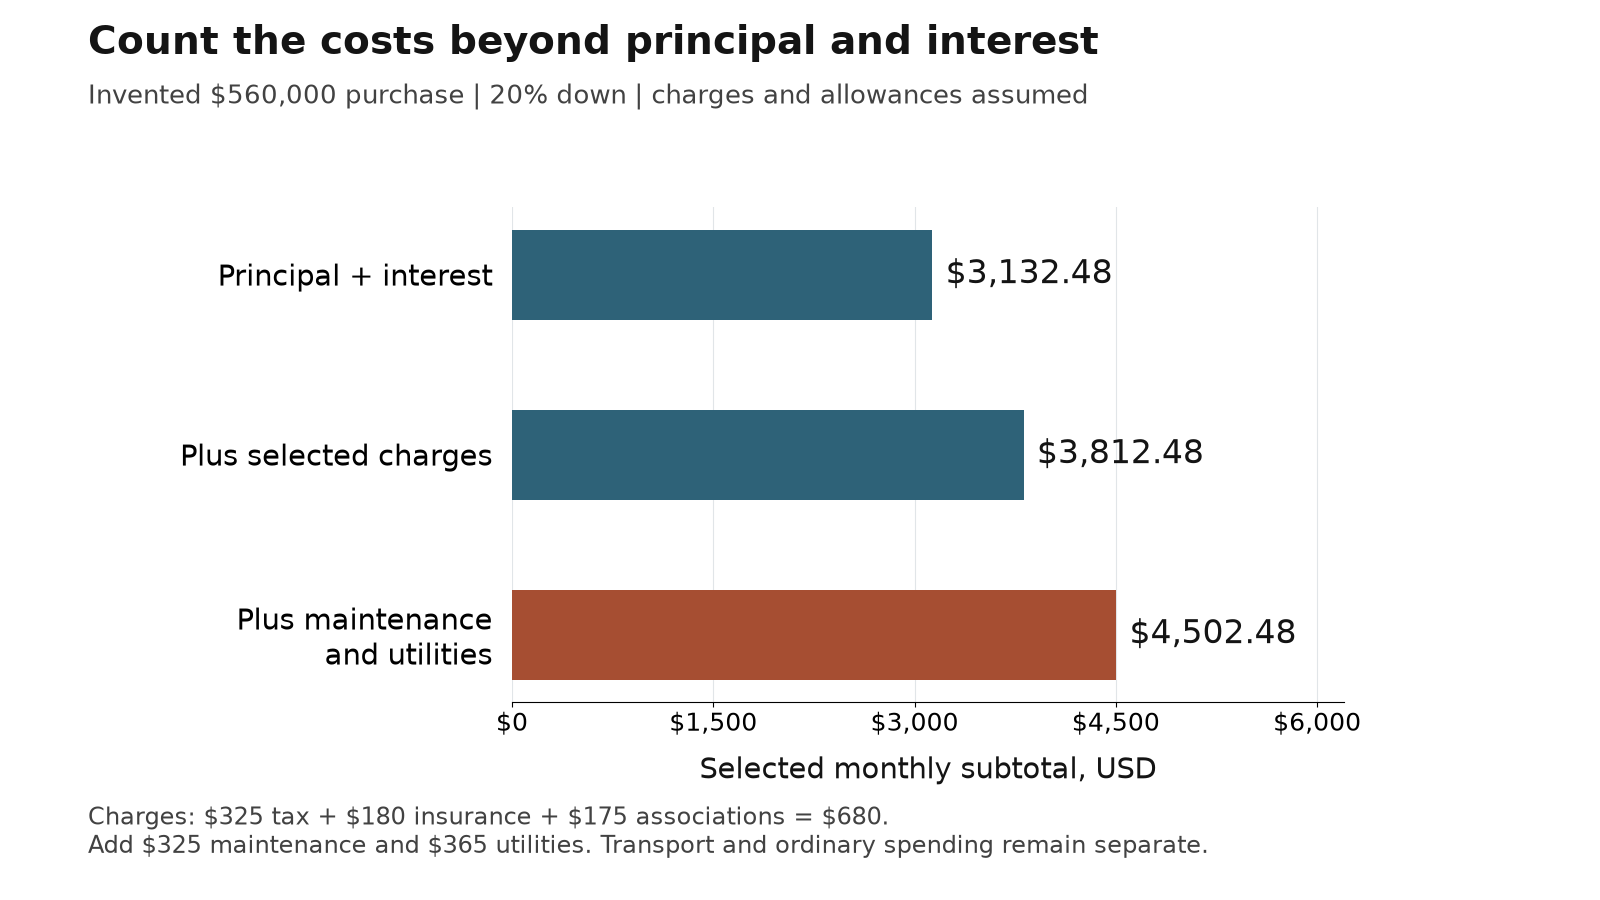
Start with $3,132.48 monthly principal and interest for the invented $560,000 purchase. Add assumed amounts of $325 property tax, $180 insurance and $175 association charges. Those selected payment components total $3,812.48. Adding $325 maintenance savings and $365 utilities produces a selected owner budget of $4,502.48 before transport and ordinary household spending.
Calculated as of October 22, 2026, these added inputs are invented allowances, not Reno averages or quotes for a particular property. Replace them with appropriate records and written proposals. Identify which items are collected through the mortgage account and which arrive separately, and check the included services before comparing two association charges.
I build a full monthly-cost model for every home we seriously consider, because two homes at the same $560,000 price can carry very differently once taxes, insurance, and HOA are layered in. Our Reno HOA-fee guide addresses that narrower document and dues question. Its dated MLS-derived amounts are not a current assessment quote for the home you are considering.
Known immediate work belongs in the initial cash plan, even if you also set money aside for future maintenance. Check heating, cooling, roof and other findings with qualified professionals as appropriate. Reno also carries real winter operating costs that a warmer market does not, so I fold heating and snow-season upkeep into the conversation. For the actual property, determine the work, responsibility and cost rather than assuming one allowance covers every situation.
How Do Income and Monthly Cash Change the Decision?
A chosen income screen can organize a comparison without determining approval. Using 30% of gross income for the selected $3,812.48 payment components gives $3,812.48 × 12 ÷ 0.30, or $152,499.20 annual gross income. Calculated as of October 22, 2026, that is a selected planning formula, not a lender standard or a statement of what all Reno buyers must earn.
Test take-home cash separately. Assume $9,000 monthly receipts, the $4,502.48 owner budget and $3,000 other spending. The remainder is $1,497.52. Another $650 monthly obligation reduces it to $847.52. Missing costs reduce it further. The example makes the household tradeoff visible without claiming that the selected remainder is appropriate for every buyer.
I always start buyers with a real pre-approval so we anchor the search to what you actually qualify for, not a guess. Compare that financing result with actual debts, reliable income, dependents’ needs and savings priorities. If income varies, examine what the proposed payment requires in a less favorable month rather than relying only on the strongest period.
A larger down payment can reduce borrowing while leaving less available cash. A smaller down payment can preserve cash while changing financing costs and requirements. Compare actual lender proposals and reserves together. Neither a chosen ratio nor a pre-approval answers every household question, and an expected raise or refinance should not be the only reason the current purchase appears manageable.
What Should You Verify About the Property’s Tax Estimate?
According to Washoe County’s tax-cap guidance, the partial abatement applies a 3% cap to qualifying owner-primary-residence tax bills, with different treatment for other properties and property new to the roll. A cap on bill growth is not a property-tax rate applied to the purchase price. Identify the parcel, tax year and status behind the figure you are given.
The county explains that it sends affidavits after ownership changes and certain other changes, and that a generated claim can leave the property at the higher general cap until a qualifying affidavit is filed. Obtain current guidance for the actual transaction. Do not assume the seller’s occupancy status automatically supplies the buyer’s required documentation or that the listing’s tax field predicts every later bill.
For a newly completed home, investigate what improvements the estimate includes and how the tax-roll treatment affects the projected amount. For any candidate, ask about separate obligations that may not appear in an association charge. Reconcile differences between a listing, lender estimate and source record rather than choosing the lowest number because it makes the budget fit.
This article does not determine a parcel’s final liability, eligibility, filing deadline or outcome. The practical result should be an identified source and a clear next step for any unresolved question. Keep that record with the property comparison so the assumed allowance is replaced before it becomes the basis of the household’s long-term plan.
How Should Insurance and Property Condition Be Reviewed?
Request a proposal for the actual address early enough to review its coverage, price, deductibles and conditions. An amount paid by the seller or used in an online calculator is not necessarily what you will be offered. If a property feature or inspection finding affects the proposal, resolve that issue with the qualified professionals handling the insurance and transaction.
According to Nevada Division of Insurance wildfire guidance, coverage questions include fire-related protection and whether additional living expenses are included. Its page addresses recovery after a fire; it does not quote coverage for a buyer. The useful purchase question is what the actual policy proposal covers and excludes, including relevant loss-of-use terms, without assuming every home or policy is identical.
Keep property-condition and insurance questions connected without treating one as a substitute for the other. An inspection does not issue an insurance contract, and a premium quote does not establish that every building system is sound. Obtain the evidence appropriate to each question and identify any work, documentation or timing required before the purchase can proceed as intended.
No individual hazard rating, insurability finding, future premium or guarantee of availability is supplied here. Do not assign the same risk or cost to every home in a named area. A sensible comparison uses actual proposals and qualified advice for the candidate, preserves unresolved issues, and avoids depending on an assumed renewal price that nobody has promised.
How Much Cash Does the Purchase Require Beyond the Down Payment?
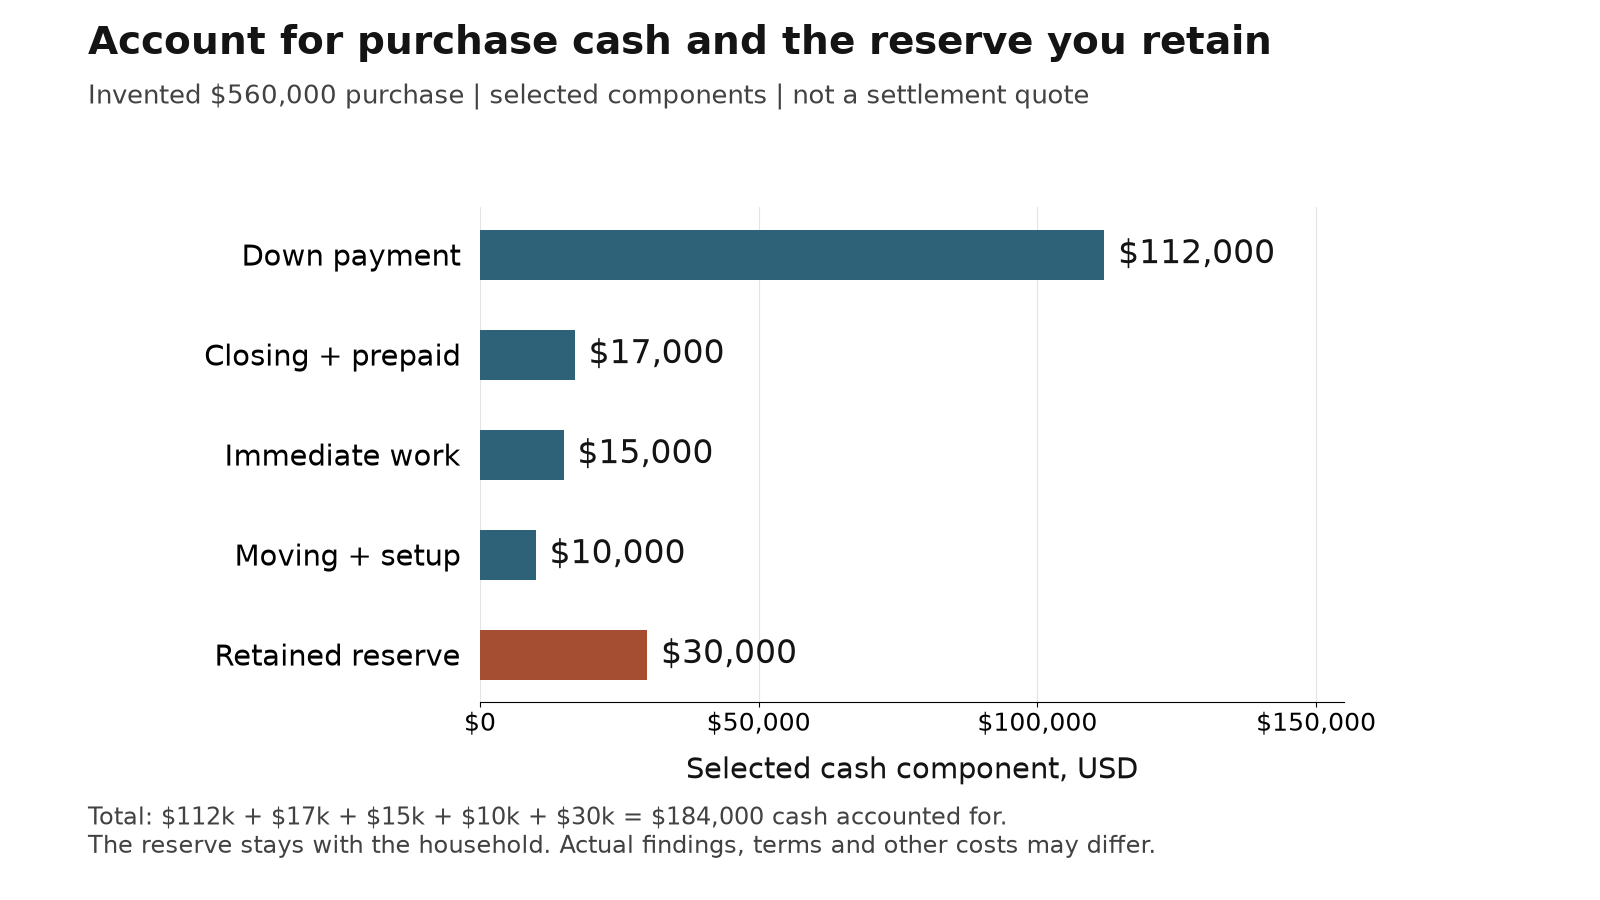
For an invented $560,000 purchase calculated as of October 22, 2026, start with $112,000 down, then assume $17,000 closing and prepaid items, $15,000 immediate work, $10,000 moving and setup, and $30,000 retained reserves. Together these selected amounts account for $184,000 cash. The retained reserve stays with the household; it is not a fee paid at closing.
| Item | Assumed amount | Evidence needed for the actual purchase |
|---|---|---|
| 20% down payment | $112,000 | Actual price and financing terms |
| Closing and prepaid items | $17,000 | Lender and settlement documents |
| Immediate work | $15,000 | Findings, estimates and timing |
| Moving and setup | $10,000 | Household-specific plan |
| Retained reserve | $30,000 | Household and property needs |
| Cash accounted for | $184,000 | Selected items only; other costs may apply |
The amount reserved for work is not an inspection conclusion or a promise that it will cover the actual findings. Separate necessary work from optional projects, and avoid treating an emergency reserve as unlimited funding for both. Compare when deposits, charges and work are due with the contract and settlement documents rather than assuming every payment occurs on closing day.
If a sale funds the purchase, coordinate that sequence with the Reno seller resources and transaction team. Include potential housing overlap, storage and moving. Expected proceeds are not available funds until the transaction provides them. A lower-priced home can require more immediate cash if its condition or timing creates obligations that a different candidate avoids.
How Should You Compare New Construction with Resale?
In my experience, buyers who prioritize a move-in-ready modern home lean new, while buyers who want space and a close-in location lean resale. I've toured both sides of this trade many times in the Truckee Meadows, and the deciding factor is almost always which compromise you can live with daily. The comparison still needs to use actual properties and written terms rather than a promise that either category is always larger, easier or less expensive.
For a builder proposal, identify what the price includes, what the household must add, the expected completion terms and the conditions attached to any incentive. Compare financing proposals consistently. A credit restricted to a particular lender or option may affect a different part of the purchase than a simple price reduction.
For a resale, review condition, included items, required work and timing. Recent replacements may reduce some near-term tasks while leaving other questions open. A cosmetic update is not proof of every system’s condition, and an older finish does not make a home unsuitable if the underlying findings and budget work for the household.
Compare both choices through the same monthly and initial-cash worksheets. Confirm that the location, essential features and expected timing fit. The article does not guarantee appreciation or assume a growing regional economy prevents price declines. A useful purchase should make sense for the household and property evidence without depending on a promised future sale or a universal new-versus-resale rule.
How Should Commute, Timing and Negotiation Affect the Shortlist?
Test the actual route to the destinations you use at relevant times, with attention to parking, required stops and weather interruptions. A neighborhood description does not measure your trip. If school assignment is material, confirm the address and applicable year with the district rather than assuming a community name establishes enrollment. No route timing, school assignment or broadband service was verified for an individual address here.
Use relevant comparable closings and the target’s current circumstances for negotiations. The county report’s days-to-contract measure and the city report’s list-to-close measure answer different questions; neither predicts when your offer will be accepted or your loan will close. Do not turn an all-year “balanced market” label into an automatic instruction to waive or demand particular terms.
In my experience, buyers who are pre-approved and clear on their priorities can act within a day or two of the right home hitting the market, which is often the difference between winning and losing a well-priced Reno house in the busy season. That is why I front-load the preparation before we ever tour. Prompt evaluation should still include resolving material property and financing questions.
I keep a live read on which area is offering the most at any given time. This article nevertheless does not present a newly evaluated current listing sample or identify a specific bargain. Discuss contingencies, credits, dates and their consequences with the professionals handling the transaction. Revise the comparison when new information changes the costs or the household’s ability to use the home as intended.
What Should Decide Between the Final Candidates?
The most expensive mistake I see is shopping on price alone and ignoring the all-in monthly cost. Write down each candidate’s strongest useful feature and most important compromise, then compare layout, findings, documented obligations, daily routine and retained cash. An advantage that the household does not need may not justify the extra cost or responsibility.
Keep unknowns visible on the final sheet. Identify the evidence needed to resolve each one and whether the choice depends on a favorable answer. A precise-looking total is not reliable when an important input is missing. Loan approval, monthly cash and the initial reserve should support the same purchase rather than giving three incompatible answers.
The two markets are closely linked, so I shop both for value depending on your priorities. Use Sparks homes for sale when that location fits, while keeping each property’s own facts and geography clear. Spanish Springs is not a substitute label for Reno’s North Valleys, and neither location guarantees more home per dollar for every candidate.
Set the search to your actual budget, using the selected figures here only to understand the method. As the lead brokerage serving Northern Nevada, Nevada Real Estate Group does this every week for buyers at exactly this price point. Call our Reno team at (775) 277-2120 or contact us to compare actual candidates against the features, costs and responsibilities that matter to your household.
Frequently Asked Questions
What is the median Reno home price in 2026?
Use a dated measure with its geographic and property-type selection. The August Reno single-family figure and September Washoe all-residential figure above describe different populations. Neither is an all-year Reno–Sparks value or a valuation of your target home. Compare relevant recent closings before deciding on an offer.
What does $560,000 buy in Reno?
It depends on the actual homes available, their location, layout, condition and obligations. This guide uses $560,000 as a chosen budget and does not guarantee a bedroom count, size, age or neighborhood. Compare the particular property’s useful features and full ownership costs before treating it as a fit.
Is Sparks always better value than Reno?
There is no universal answer for every household or property. Compare equivalent current candidates, their condition, costs and daily-use requirements. Keep Spanish Springs and other Sparks-area locations geographically distinct, and do not assume that a lower asking price or larger floor area automatically produces a better purchase.
What is the payment on the $560,000 example?
With 20% down, the assumed loan is $448,000. At 7.50% fixed for 30 years, monthly principal and interest are $3,132.48. Property charges and other expenses are additional. The broader owner budget uses invented allowances that must be replaced with actual records and proposals.
Does an association fee include all snow removal?
Do not assume it does. Identify who maintains the actual street and what remains the homeowner’s responsibility around driveways, sidewalks and plow deposits. Public-street, private-street and separately contracted services can differ within a broad community. Confirm the applicable arrangement, timing and included work for the address.
Does the 3% tax cap mean tax equals 3% of the price?
No. Washoe County describes a partial abatement limiting tax-bill increases for qualifying properties, with exceptions and documentation requirements. It is not a purchase-price tax rate. Review the actual parcel, tax year and status and obtain current guidance for the transaction instead of calculating from a listing headline.
Should I use every available dollar for the down payment?
Compare actual financing terms with the cash needed for closing, immediate work, moving and retained reserves. A larger down payment reduces borrowing but also reduces cash available for other needs. The appropriate balance depends on the household and property; no invented example here establishes the right reserve for everyone.
Does a foothill or new-construction home guarantee appreciation?
No. Future prices depend on the property and market conditions, among other factors. Review current evidence, costs, responsibilities and the way the home fits your use. A setting, warranty, regional employer or community name is not a guarantee of future value, an easy sale or a lower-cost refinance.
Which Sources Inform This Reno Budget Guide?
Sources were reviewed as of October 22, 2026. NREG’s Reno city report is an affiliated published single-family selection. Sierra Nevada REALTORS’ September report provides the separately scoped Washoe all-residential panel. These are published summaries, not a new audit of individual transactions. No asking-price or home-size sample was collected for this guide.
Washoe County tax-cap guidance, City of Reno snow guidance and Somersett snow information support specific responsibility questions. Nevada Division of Insurance wildfire guidance and EPA lead-disclosure guidance identify matters for appropriate document review; no individual policy, hazard or legal outcome was verified.
Freddie Mac PMMS supplies national rate context and the CFPB Loan Estimate guide supports financing comparisons. Payment, household, seasonal and cash worksheets are original calculations with disclosed assumptions, not lender offers, contractor prices, client results or proof of available homes at the selected budgets.
The cover is conceptual and the charts illustrate those examples. Dated companion guides require their own current review, and inaccessible general insurance content was not treated as verified guidance. Keep the period, selection and assumptions attached when using a number. The final choice requires current address-specific evidence and a household plan that can accommodate the obligations the purchase creates.
Nevada Real Estate Group · Chris Nevada · License S.181401 · (775) 277-2120.