There is no single salary that makes every Sparks household comfortable. Start with your actual rent or mortgage, work schedule, childcare and take-home pay. The dated county benchmark below provides context, while the household worksheets show how to compare a specific lease or purchase with your available income.
A useful Sparks income plan connects a real home to a real worksite. A job advertised in the Reno area can involve a different shift, entrance and trip than another job at the same hourly pay. A lower advertised rent also loses its advantage if mandatory fees, transportation or childcare use the difference. Below, public benchmarks stay separate from deliberately hypothetical budgets so you can replace each assumption with a quote or a pay stub.
To estimate the salary you need in Sparks, compare reliable take-home pay with a complete household budget. The February 15, 2026 Washoe County living-wage model reports $51,212 before taxes for one adult without children, but excludes several costs of comfort and financial resilience. In the rental illustration below, $2,200 in monthly housing costs corresponds to $88,000 gross income under a chosen 30% screen; that screen is neither a universal requirement nor lender approval.
- Use Washoe County's dated basic-needs model as context, then price the actual Sparks address.
- Separate gross salary, reliable hours and take-home deposits before comparing homes.
- Include utilities, fees, transportation, care, debt and reserves alongside housing.
- Compare job sites and shift times; a metro wage average does not describe a particular offer.
- Keep moving and purchase cash separate from the recurring monthly budget.
The Sparks cost-of-living guide explains address-level expenses; this guide focuses on the income needed to carry them.
What does the current Washoe County income benchmark tell you?
According to the Living Wage Institute's Washoe County page, accessed October 22, 2026, the model was updated February 15, 2026. Its annual income before taxes is $51,212 for one adult without children, $92,866 for two adults with one working and two children, and $125,631 for two adults with both working and two children. The two-adult annual figures are household totals; the hourly column for two working adults is expressed per worker. Mixing those units would overstate or understate the comparison.
These are modeled basic needs across Washoe County. They are not city medians, advertised salaries, a survey of NREG clients or promises that a given family will be comfortable. The model's methodology and FAQ explain its assumptions and exclusions, including savings and emergency expenses. Your actual household can differ materially in housing, care and health costs.
Use the benchmark to identify questions, then replace assumptions with your own documents. A parent with an actual childcare quote, an employee with unusually costly benefits and an owner with a paid-off home should not all use the same salary target. Read the household category carefully before comparing your income to it. The useful result is a list of costs to investigate, not a pass/fail label on the household or an assurance that a home is affordable.
How do you turn a job offer into dependable monthly income?
Start with the pay structure. A stated annual salary, an hourly wage, overtime, a temporary hiring bonus and a shift differential are different inputs. Ask which hours and supplements are guaranteed, when benefits begin and whether the employer's written offer specifies the same work location as the job advertisement. Do not commit recurring housing costs against a bonus that may never recur.
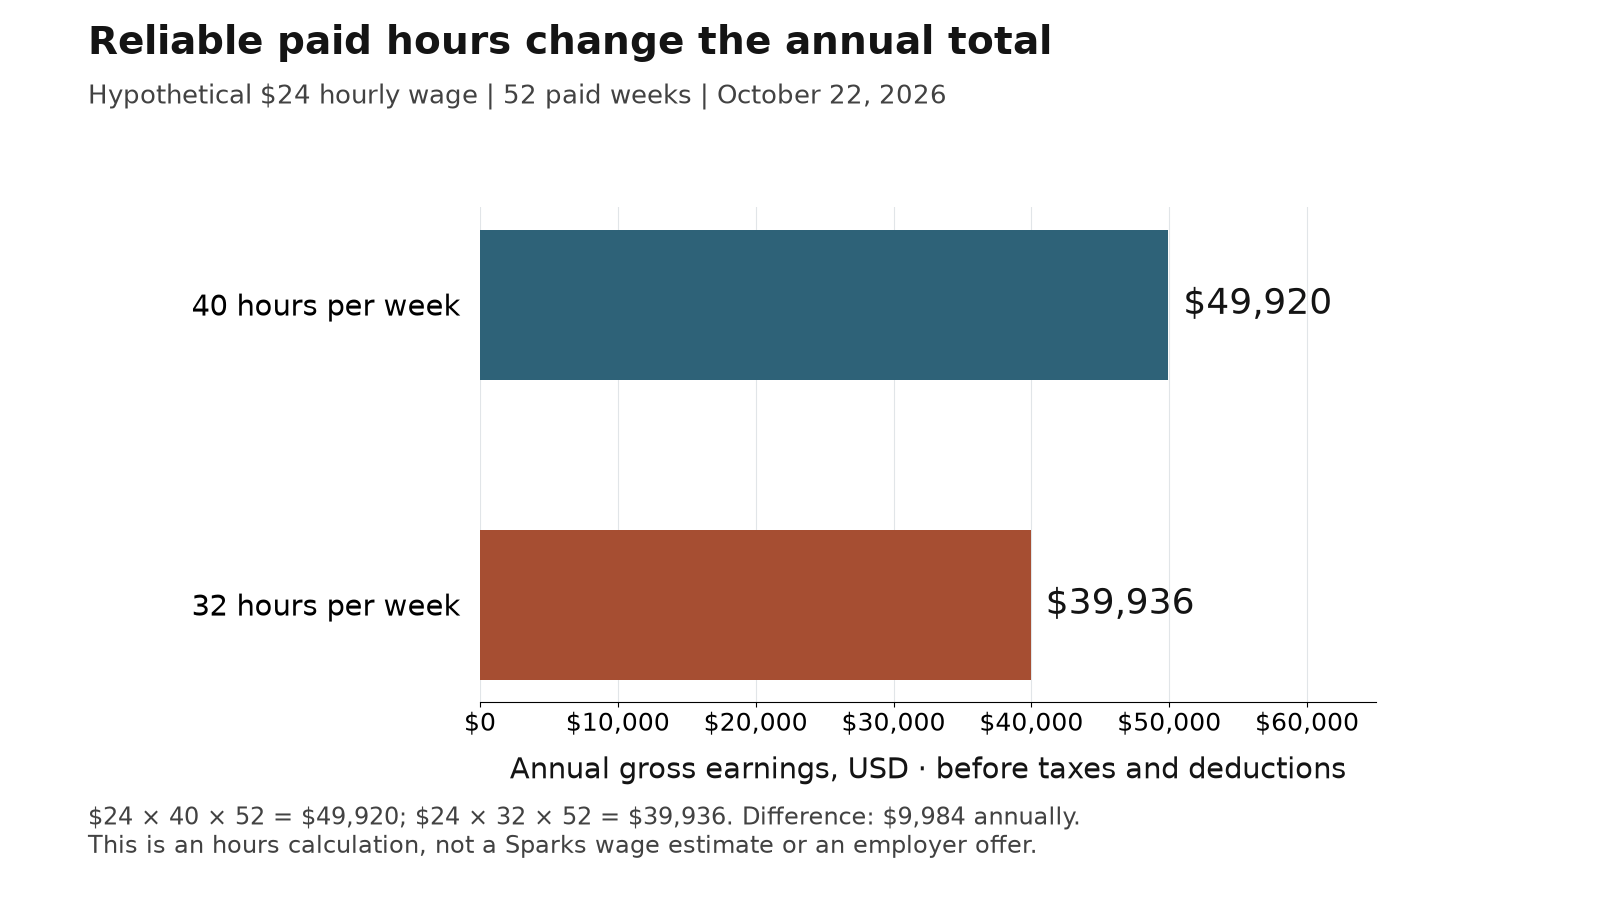
For an illustration, $24 an hour for 40 paid hours every week over 52 weeks produces $49,920 before taxes. At 32 paid hours, the same wage produces $39,936, a $9,984 annual difference. This is arithmetic, not a Sparks wage estimate or an assumption about a particular employer. Paid leave, unpaid gaps and overtime rules can change actual earnings. A monthly budget based on the higher schedule needs a fallback if the lower schedule is possible.
Next use payroll estimates or recent deposits to establish take-home pay after withholding and benefit deductions. Gross annual income divided by twelve is useful for comparing stated salaries; it is not the cash available to spend. If you are paid every two weeks, write down the actual deposit dates and bill dates rather than treating every month as identical. For variable earnings, compare ordinary months and a weaker month. The household that can pay the lease only during peak overtime has a different risk than one whose regular schedule covers essential costs.
What salary would support a Sparks rental?
First collect the advertised base rent and the full lease cost. Ask about required recurring charges, utilities, parking, pet terms and any concession that expires. Keep refundable deposits and other move-in cash separate from monthly spending. A promotion can make the first payment look attractive while the regular payment after it ends is materially higher.
Consider an invented rental with $1,900 base rent, $210 utilities, $25 renters insurance and $65 required recurring fees: total monthly housing is $2,200. Choosing to compare that housing total with 30% of gross income produces an annual screen of $88,000: $2,200 × 12 ÷ 0.30. Looking only at the $1,900 rent would produce $76,000 under the same screen, missing the effect of the other costs. Neither figure is a current Sparks market rent or a landlord's application standard.
A gross-income percentage is only an initial comparison. It does not know your debt, childcare, health expenses or savings priorities, and different landlords have their own criteria. Finish the take-home budget even if the advertised rent meets your chosen ratio. If you are comparing an apartment near a worksite with a larger rental farther away, price both transportation plans before choosing. A roommate arrangement also needs explicit responsibility for utilities, deposits and the lease if one person leaves; splitting the advertised rent alone is not a complete shared budget.
What does a single adult's monthly budget look like in Sparks?
The following worksheet, prepared as of October 22, 2026, deliberately uses assumptions. It is not a measurement of what Sparks residents spend, and its income is not inferred from a gross salary using an unspecified tax rate. Assume actual take-home deposits total $4,600 monthly. The purpose is to show the relationship between those deposits and the obligations the household chooses, not to announce a new universal salary range.
| Item | Assumed monthly amount | Evidence to obtain |
|---|---|---|
| Complete rental housing | $2,200 | Lease, utility allocation, insurance and recurring fees |
| Food | $450 | Your actual household spending |
| Transportation | $350 | Route, insurance, vehicle or transit costs |
| Health spending | $225 | Costs not already deducted from take-home pay |
| Debt payments | $200 | Current minimum obligations |
| Other spending | $175 | Phone, clothing and other selected needs |
| Savings and irregular-expense allocation | $400 | Your chosen goals and known future bills |
| Total allocations | $4,000 | Sum of the rows above |
| Remaining from $4,600 take-home | $600 | Before any omitted obligations |
The $600 remainder is a result of these assumptions, not an independent emergency fund. An additional $350 expense leaves $250. Check that you have not counted payroll-deducted insurance twice, and add costs missing from this illustration. A low debt payment, different health plan or shared housing could change the outcome substantially; so could an expensive vehicle repair. Evaluate the revised budget before deciding whether a more expensive home fits. A positive remainder matters only if the worksheet includes the bills you will actually face.
How much income would a Sparks home purchase require?
A purchase needs both a monthly financing calculation and cash to complete the transaction. Ask for a property-specific estimate covering principal, interest, taxes, insurance, mortgage insurance when applicable, and association charges. Include maintenance and utilities in household planning even when they are outside the lender's quoted payment. According to the CFPB's Loan Estimate guide, the form identifies payment components and cash-to-close information. Use it when checking a listing's simplified calculator.
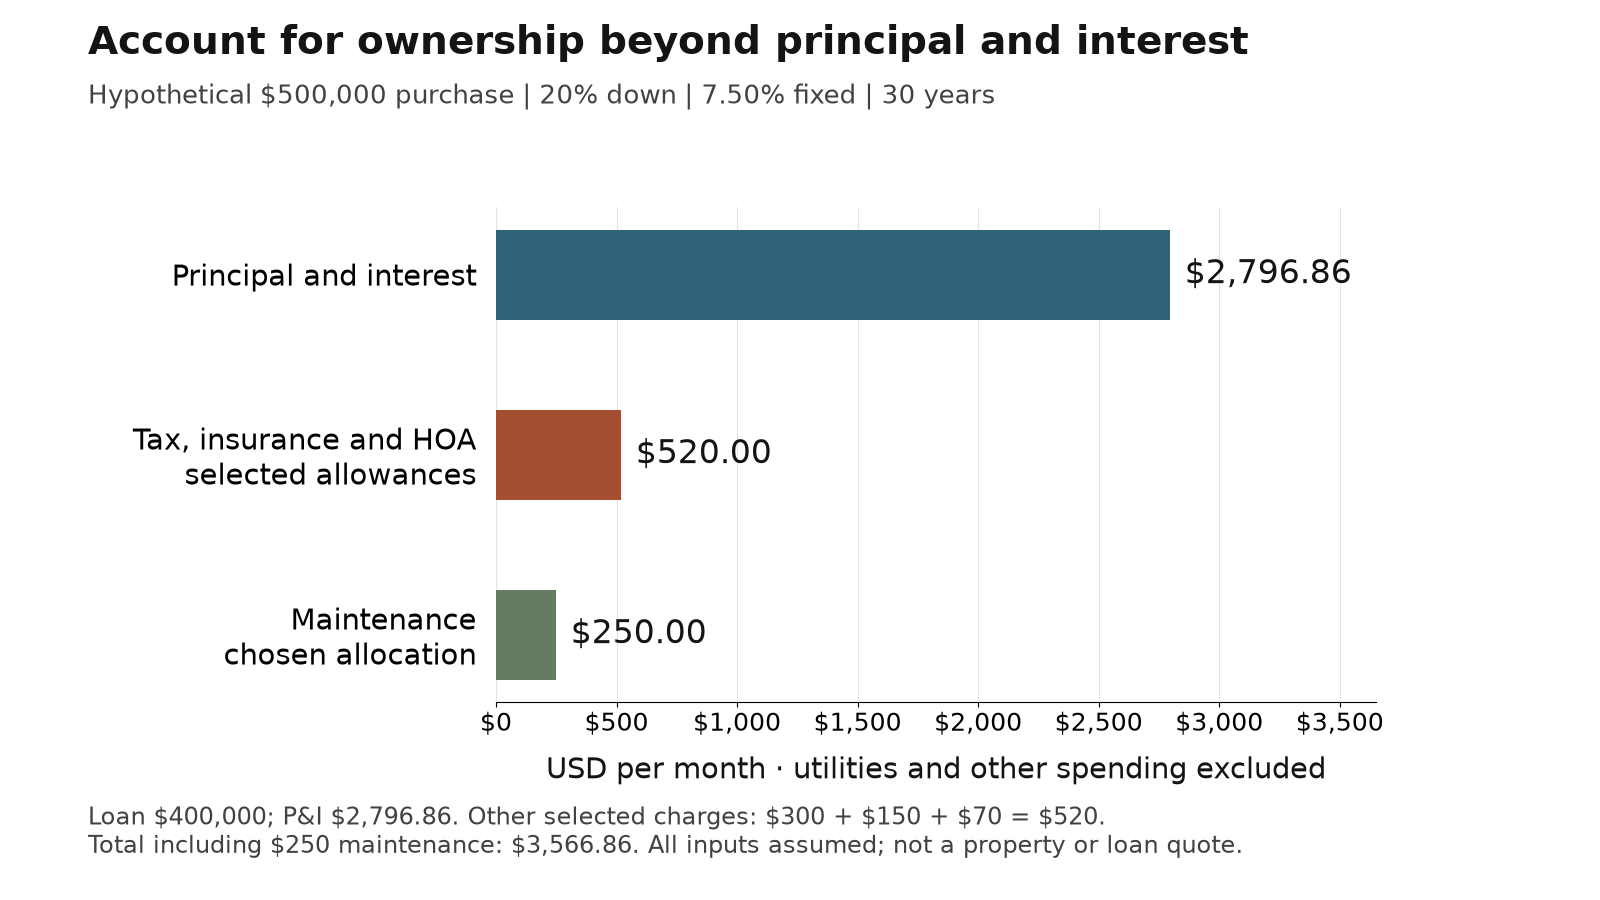
Here is a hypothetical purchase prepared as of October 22, 2026, not a claim about Sparks' median price: a $500,000 home, 20% down and a $400,000 loan over 30 years at an assumed 7.50% fixed interest rate. Principal and interest are $2,796.86 monthly. Add assumed $300 property tax, $150 homeowners insurance and $70 HOA dues for $3,316.86. Add a separate $250 maintenance allocation and selected housing costs become $3,566.86 before utilities. Every nonloan input needs an address-specific check; the assumptions do not establish a tax rate, insurance premium or association obligation.
According to Freddie Mac's PMMS, the national 30-year fixed average was 7.32% as of October 22, 2026. The example deliberately uses 7.50%, not that survey average as a personal offer. At a chosen 30% gross-income screen, the $3,316.86 payment corresponds to $132,674.40 annually. This calculation excludes the maintenance allocation and is not approval or a definition of comfort. Compare the complete household budget and actual lender terms before adopting a price ceiling.
What changes when children or a second income enter the budget?
Build the household schedule alongside the dollars. Childcare depends on actual ages, hours, provider availability and school calendars. A second job may increase deposits while also adding care, commuting and meal costs. It can still materially improve the budget, but subtract those new expenses before assigning its entire paycheck to a larger mortgage.
For example, an assumed additional $2,500 in monthly take-home pay minus $1,300 care, $250 travel and $150 other work-related spending leaves $800 for the household. That is a transparent scenario, not a local childcare quote or a claim about a typical family's second income. If care is unavailable for the actual shift, the proposed job-and-home combination may not work even when the arithmetic is positive. Confirm availability and the backup arrangement before signing either commitment.
The worksheet below uses the separate ownership illustration and a deliberately assumed $9,000 household take-home amount. It keeps care visible instead of hiding it in a broad family-income range. The Living Wage Institute FAQ is useful for understanding why basic-needs categories differ by family structure; your own circumstances still determine the bill. A home that works while one adult provides care may need a new budget when both adults work. Conversely, the end of a particular childcare expense does not automatically remove every school-related or transportation cost.
| Allocation | Monthly amount | What to verify |
|---|---|---|
| Selected ownership costs including maintenance | $3,566.86 | Loan, tax, insurance, HOA and repair planning |
| Food | $900 | Household spending records |
| Transportation | $700 | Both workers' schedules and routes |
| Health costs | $450 | Costs outside payroll deductions |
| Childcare | $1,400 | Actual provider quote and availability |
| Debt | $250 | Statements and repayment terms |
| Utilities and other selected spending | $350 | Address and household bills |
| Additional savings and irregular expenses | $600 | Goals separate from maintenance above |
| Total | $8,216.86 | Before omitted obligations |
| Remaining | $783.14 | $9,000 minus $8,216.86 |
Why can lender approval differ from a comfortable income?
A lender evaluates a particular loan application. Your household must also manage expenses and goals that are not all represented by underwriting ratios. According to the CFPB, debt-to-income ratio is monthly debt payments divided by gross monthly income, and limits vary across lenders and loan products. It is not the same as housing divided by take-home pay.
Suppose counted monthly debt is $3,600 and gross monthly income is $8,000. The ratio is 45%. If counted debt falls to $3,200 with the same income, it becomes 40%. These examples explain the denominator and arithmetic; they do not establish an approval cutoff. A lender may treat particular income or obligations differently under the relevant program, and a ratio alone does not describe credit, reserves, property condition or the rest of the application.
The CFPB's affordability guidance also directs buyers to their wider finances. Bring your complete budget to the conversation. You may choose a payment below what a lender approves so that an ordinary repair or a reduction in paid hours does not force borrowing. If paying off a debt improves the ratio, check the cash remaining afterward as well: a better ratio and an empty reserve account are different tradeoffs, not an automatic improvement in every part of the decision.
How should Sparks workers compare wages and job locations?
Use the written offer first, then dated occupational data for context. According to BLS, its May 2025 Reno metro wage estimates show mean hourly pay of $31.02 overall, $25.56 in production, $23.35 in transportation and material moving, and $51.36 for healthcare practitioners and technical occupations. These are broad occupational averages, not starting salaries, vacancies or city-only statistics. The release, published June 18 and reissued June 24, 2026, defines the metro as Lyon, Storey and Washoe counties.
That geographic scope matters for a Sparks housing search. Do not assume an offer described as “Reno-area” is close to every Sparks neighborhood, or that different jobs at an industrial site have the same wage. Ask for the specific entrance, shift start, parking process and any employee transportation arrangement. A day shift and an overnight shift can require different childcare and travel plans even at the same address.
Compare benefits, reliable hours and commute costs alongside headline pay. A modestly higher wage with uncertain hours or expensive dependent coverage can produce less usable household income. If you are considering work east of the city, test the actual trip to the employer's site instead of assigning a universal commute time to the Tahoe-Reno Industrial Center. Read the Reno job-market guide for the wider employment decision; this income worksheet does not certify hiring availability or predict an employer's growth.
Can transportation change which home fits your salary?
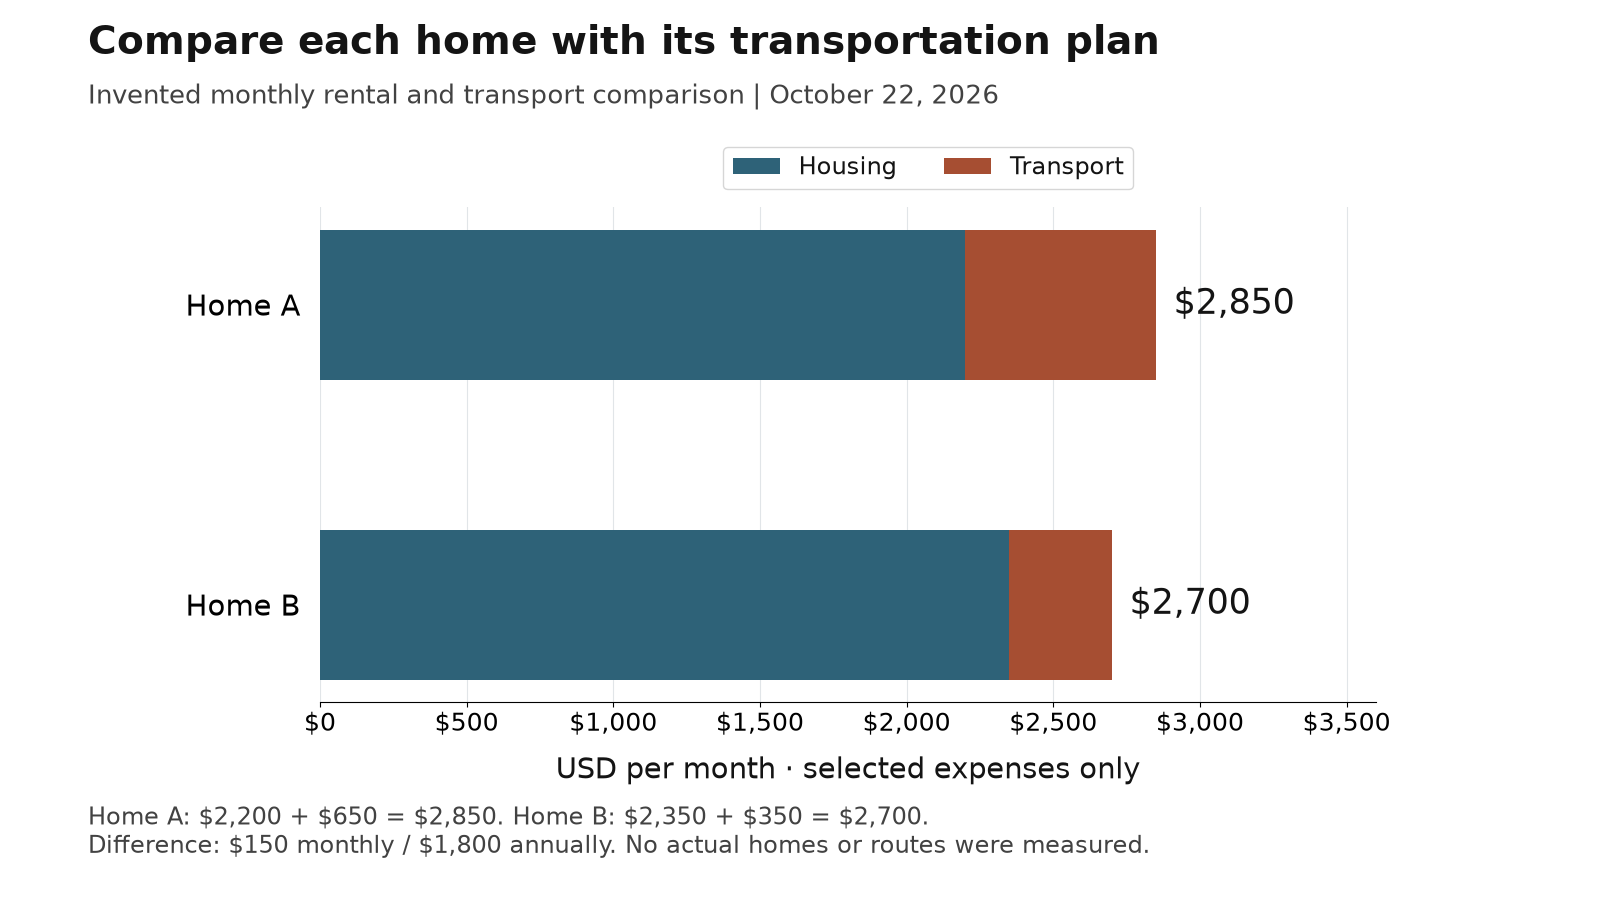
Yes. Compare a home and its transportation plan as a pair. For two invented rentals, Home A has $2,200 in housing costs and $650 transportation, totaling $2,850 monthly. Home B has $2,350 housing and $350 transportation, totaling $2,700. The more expensive home has a $150 lower selected monthly total, or $1,800 over twelve months. These are chosen inputs, not measured commute costs or a recommendation for a particular neighborhood.
According to RTC Washoe's fares and passes page, published regular fares are a single ride at $2, a day pass at $3, a seven-day pass at $14.50 and a 31-day pass at $65, as of October 22, 2026. Eligibility and payment rules matter. A posted pass price does not establish that service reaches a worksite or operates when your shift ends. Check the actual route, walking connection, transfers and holiday schedule before replacing a vehicle budget with a transit allowance.
For a car, include the costs you will incur rather than fuel alone: financing when applicable, insurance, maintenance, parking and the effect of the distance driven. Confirm any employer shuttle directly; do not assume that a benefit described for another site or employee category applies to your job. A second adult's travel can also change the comparison. Keeping the two complete plans side by side prevents a lower housing price from obscuring a more expensive daily routine.
How should you budget for winter and irregular expenses?
Build an annual calendar as well as a monthly worksheet. Request available utility history for the home, understand which services the lease includes and ask what equipment you are responsible for maintaining. A low bill from one mild month does not establish annual cost. Heating, cooling, vehicle upkeep and recreational spending can arrive at different times, so an annual average alone can conceal a difficult cash-flow month.
For a simple planning example, setting aside $100 each month accumulates $1,200 over twelve months for a known future expense. This is not a claim about a typical Sparks winter bill or an adequate repair reserve. Use the actual quote and due date. If the expense is due before twelve deposits have accumulated, the plan also needs existing cash. Keep known costs separate from funds intended for genuinely unexpected events.
Stress-test income and spending independently. The illustrated ownership household has $783.14 remaining after its selected allocations. If take-home pay falls by an assumed $800 while those costs stay fixed, the worksheet becomes negative by $16.86. That is a warning to revise the plan, not evidence that all households need a particular reserve amount. Compare a smaller housing commitment, more reliable income or a different move date before relying on future overtime. Do not count the same savings balance as a down payment, repair fund and protection against lost income at once.
Does moving from California automatically increase take-home pay?
According to the Nevada Department of Taxation, Nevada does not impose an individual income tax. That is a useful distinction, but it does not determine the amount deposited from a particular paycheck. Federal taxes, payroll deductions, benefits and other obligations still affect cash available to the household. A relocation that changes salary or dependent coverage needs a new payroll estimate rather than a generic annual savings claim.
California also distinguishes residence and income sourcing. According to the Franchise Tax Board guidance for part-year residents and nonresidents, California-source income can remain relevant after a move. Do not assume a Nevada mailing address resolves work performed elsewhere, business income or other cross-state facts. Obtain advice based on the actual arrangement before spending an assumed tax saving.
The honest caveat is that California salaries are often higher, so the move can mean a pay adjustment; but in my experience the lower cost of living and tax savings more than offset it for most households. For your decision, compare your own before-and-after deposits and expenses; that experience statement is not a calculation of your tax outcome. Keep a move-year scenario separate from the first full year after relocation. The Reno relocation guide covers broader move planning that also helps households evaluating Sparks.
Is Sparks always less expensive than Reno or Carson City?
A city label does not price a particular home. Compare homes of similar type and condition, the actual financing or lease terms, required fees and the travel each address creates. A smaller older property, a larger recently built home and a condo with substantial shared expenses answer different requirements. A headline city median cannot establish what the same household would spend at each address.
Many of my clients shop both Reno and Sparks before deciding, and value-focused families consistently land in Sparks. Start that comparison with your own measurable priorities: maximum total monthly spending, required bedrooms, acceptable maintenance work and the route to a named worksite. Explore Reno, Sparks and Carson City without assuming one city wins every category. If a lower purchase price needs more immediate repair cash or a longer trip, carry those differences into the worksheet.
For Sparks-area choices such as Spanish Springs, Wingfield Springs or the Sparks Marina area, inspect the actual address and governing documents. Confirm school assignments and any services relevant to your household directly rather than treating a neighborhood reputation as a budget fact. For newer homes use the Northern Nevada new-construction hub; the Southern Nevada construction market is not evidence of available Sparks inventory. Compare effective costs after written incentives, and ask which charges continue after any promotion ends.
How much cash should you have before moving or buying?
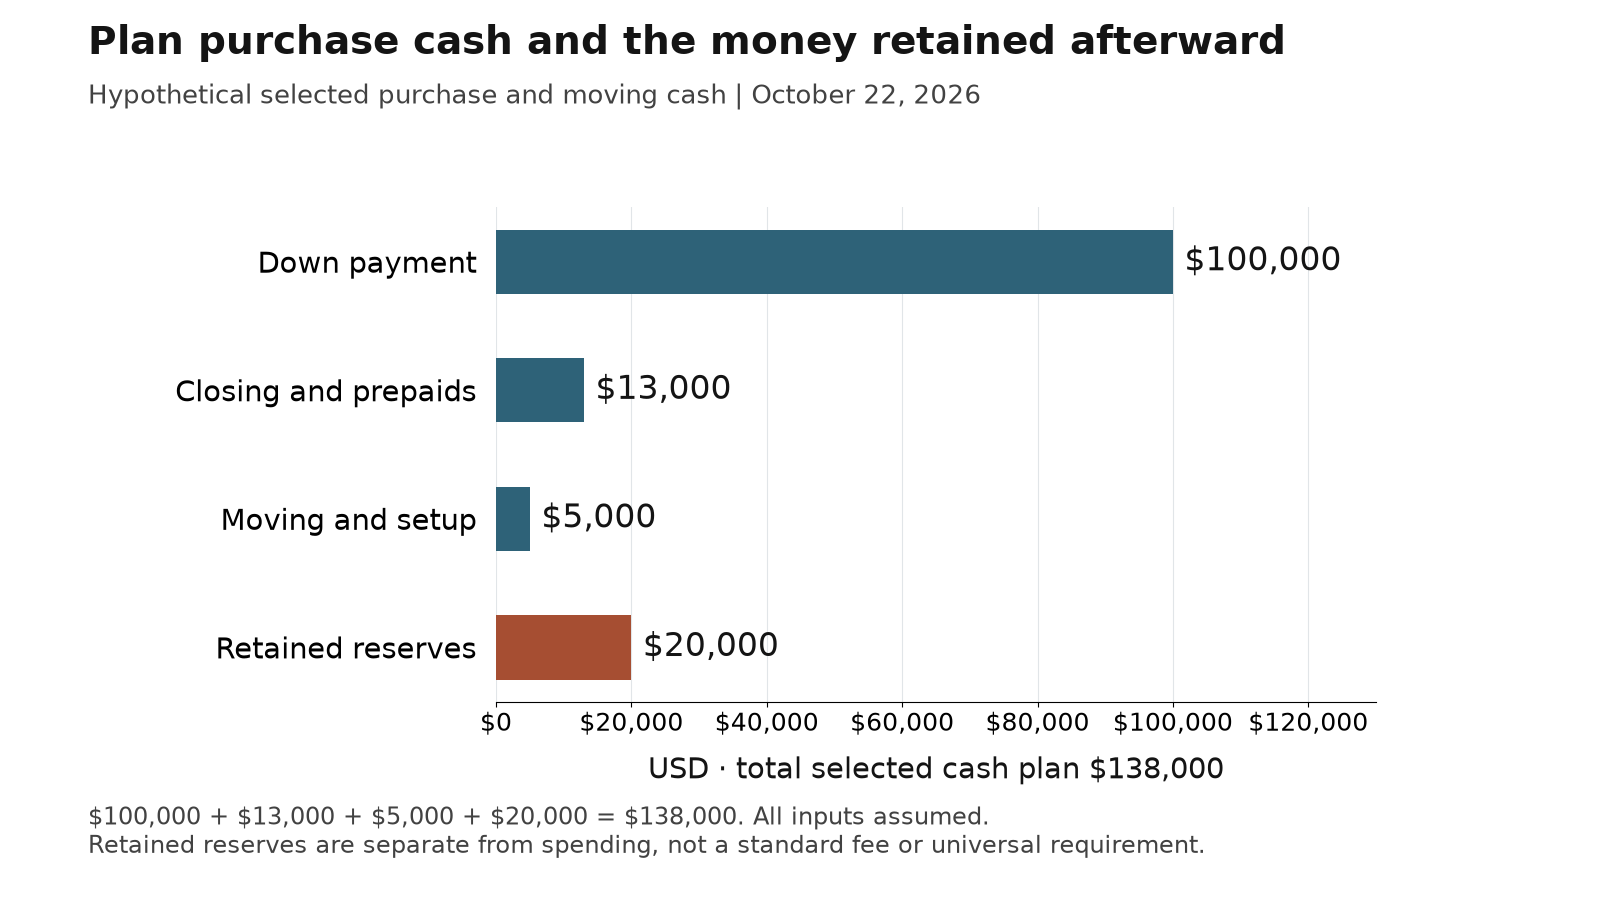
Separate closing cash, relocation spending and the money you want to retain afterward. In the $500,000 purchase illustration, 20% down is $100,000. Add assumed $13,000 closing and prepaid costs, $5,000 moving and setup, and $20,000 retained reserves: the planned cash total is $138,000. Those assumptions are neither a standard fee schedule nor a recommended reserve for every buyer. Replace them with lender documents, moving quotes and your own obligations.
The CFPB Loan Estimate guide helps separate estimated cash to close from the monthly payment. Ask what must be paid before closing, what is already credited and what could still change. Avoid adding a deposit again if it is already included in a net cash-to-close calculation. A buyer using a lower down payment must also recheck the resulting loan terms, monthly costs and remaining cash rather than assuming only one line changes.
Renting first, which I often recommend for out-of-state buyers testing a neighborhood, requires its own documented move-in plan. Obtain the first payment, deposit and required fee amounts from the actual lease offer; check whether you must carry an old home or lease at the same time. If you are selling to fund the move, seller resources can help organize timing questions. Do not treat estimated sale proceeds as available cash before the sale closes or ignore the possibility that temporary housing and storage may be needed between transactions.
How do you turn a monthly budget into a Sparks home search?
Set a monthly spending limit from dependable take-home pay and the obligations you will actually carry. Then compare rent or financing options against that limit. Keep a separate cash limit for the move and purchase. If the two limits point to different price ranges, address both before touring homes that would require spending the reserve you meant to keep.
I tell relocating clients to decide how they will handle housing first — rent, buy, or arrive with equity — and then build the rest of the budget around it. Many of my relocating clients rent for six to twelve months first to test a neighborhood and experience a Northern Nevada winter, then buy — a smart, low-risk move. A rental plan still needs its lease terms, total cost and next move considered; it is not a guarantee that buying later will cost less.
Use a compact decision sheet for each shortlisted home. Record the evidence date so an expired insurance quote, old loan offer or changed shift does not silently remain in the comparison. If one option fails a requirement, identify the specific cost or feature that causes the problem. That makes the next search more productive than repeatedly increasing a generic salary target.
| Decision | Evidence | Condition that changes the choice |
|---|---|---|
| Can reliable income cover the home? | Pay structure, deposits and complete monthly budget | Hours, benefits, debt or care costs change |
| Does the work trip fit? | Actual entrance, shift, route and travel costs | Different worksite or unavailable transport |
| Is the purchase affordable beyond the mortgage? | Loan Estimate, tax, insurance, HOA and maintenance review | Revised terms, property condition or new obligations |
| Is the move funded? | Cash-to-close, relocation quotes and retained cash plan | Delayed sale, overlapping housing or upfront repairs |
What should you verify before making the commitment?
Reconcile the final documents with the worksheet. For a lease, confirm recurring charges, concessions, the deposit and the move-in date. For a purchase, confirm financing terms, insurance availability, property expenses and inspection findings. For a job change, confirm the worksite, starting schedule, benefit timing and first expected payroll. A plan assembled from separate optimistic assumptions can fail when those dates are placed on one calendar.
Across the more than 9,600 transactions Nevada Real Estate Group — the #1 real estate team in the state — has closed, Sparks is consistently where value-focused buyers land when Reno feels like a stretch. The public benchmarks and hypothetical calculations in this guide are separately identified; they are not a study of those transactions. Use them to prepare specific questions about your intended home and work arrangement.
Bring the income plan, household priorities and actual quotes to a conversation about Sparks homes, or contact our team at (775) 277-2120. The next useful action is a property comparison within your two limits: sustainable monthly spending and available cash. If the evidence changes, update the budget before increasing a commitment. A home that fits the first payment but leaves no workable response to an ordinary change in hours or expenses deserves another look.
Frequently Asked Questions
What salary do you need to live in Sparks in 2026?
There is no universal comfort salary. The Living Wage Institute's February 15, 2026 Washoe County model reports $51,212 before taxes for one adult without children. It is a county basic-needs reference, not a Sparks quote or a savings plan. Use your actual housing, care, transport, debt and take-home pay to establish the household's target.
Is $24 an hour enough to live in Sparks?
At an assumed 40 paid hours weekly for 52 weeks, $24 an hour produces $49,920 before taxes; at 32 hours it produces $39,936. Whether either works depends on the full budget and actual take-home pay. Compare reliable hours, benefits and housing rather than treating the hourly rate alone as an affordability answer.
What income supports a $1,900 Sparks rental?
A chosen 30% gross-income screen gives $76,000 annually for $1,900 rent alone. In this guide's hypothetical example, utilities, insurance and fees bring housing to $2,200, giving an $88,000 screen. Those are illustrative calculations, not current rent quotes, landlord criteria or proof that the remaining household budget works.
What salary do you need to buy a $500,000 Sparks home?
With an assumed 20% down, 30-year loan at 7.50%, and selected tax, insurance and HOA inputs, this guide calculates a $3,316.86 monthly payment. A chosen 30% gross-income screen gives $132,674.40 annually. Maintenance, utilities and other spending still matter; obtain actual financing and property costs before using that screen.
Does the county living-wage figure include savings?
The model is a basic-needs reference with exclusions described in its methodology and FAQ, including savings and emergency expenses. It should not be relabeled a comfort threshold. Choose the matching household category and then add your own goals, debt, irregular bills and actual costs before deciding what income the household needs.
Will living in Sparks give me a short industrial-work commute?
Confirm the employer's exact site entrance and your shift. A metro job label does not establish travel time from a particular home, and a transit fare does not establish service to the worksite. Compare the actual route, parking, transportation costs and childcare schedule before choosing a home on the assumption of a short trip.
Does Nevada's tax system guarantee a larger paycheck after moving?
Nevada does not impose individual income tax, but your salary, federal withholding, benefits and other obligations still determine take-home pay. California-source income and move-year facts can also matter. Use an employer payroll estimate and advice for your particular arrangement rather than a universal dollar amount of expected tax savings.
Should you rent before buying in Sparks?
Renting can provide time to evaluate a location and work routine, but it has lease, moving and possible overlap costs. Compare the complete rental plan with the purchase's monthly obligations and upfront cash. The better choice depends on your timing, finances and actual properties, not an assumption that either path always costs less.
What evidence and assumptions support this guide?
Reviewed October 22, 2026. The county income model is dated February 15, 2026; BLS wages describe May 2025 and retain that historical scope; the national mortgage reference is the October 22 PMMS release. Transit fares were checked against RTC's published page. Each linked source sits beside the claim it supports.
All household budgets, hours illustrations, home comparisons and cash totals are explicitly chosen examples. Loan principal and interest use the standard monthly amortization calculation; the housing screens multiply monthly cost by twelve and divide by the selected 30% share. They are not observed NREG client outcomes, market medians, loan offers or approval rules. Dollar totals use the displayed rounded monthly payment. Taxes, insurance, maintenance, care and travel require actual household and property evidence.
Sources include the Living Wage Institute through MIT, BLS, CFPB, Freddie Mac, RTC Washoe, Nevada Department of Taxation and California FTB. The inherited company and experience statements remain distinct from that public research. This guide does not verify an individual tax result, inspection condition, school assignment, job vacancy or future price. Recheck consequential inputs when the employer, lease, property, financing or move date changes; the date on this article does not keep a separate quote valid indefinitely.